


Learn Why The Bull Case For Boston Scientific Stock Could Change Following Segment Reorganization
- Boston Scientific appointed Joseph M. Fitzgerald as future COO and reorganized its operations into three reportable segments, aligning leadership, business units and regions under a new structure effective January 1, 2027.
- The new Interventional Therapies, Rhythm Solutions and MedSurg segments group businesses by procedure type and care setting, which could sharpen capital allocation, spotlight underperforming areas and change how investors assess Boston Scientific's earnings mix.
- We will now look at how Boston Scientific's new segment structure might influence the existing investment narrative around earnings expectations.
Scan how Boston Scientific's reshuffle compares with other device makers retooling for growth by running your filters against our curated list of 33 healthcare AI stocks
Boston Scientific Investment Narrative Recap
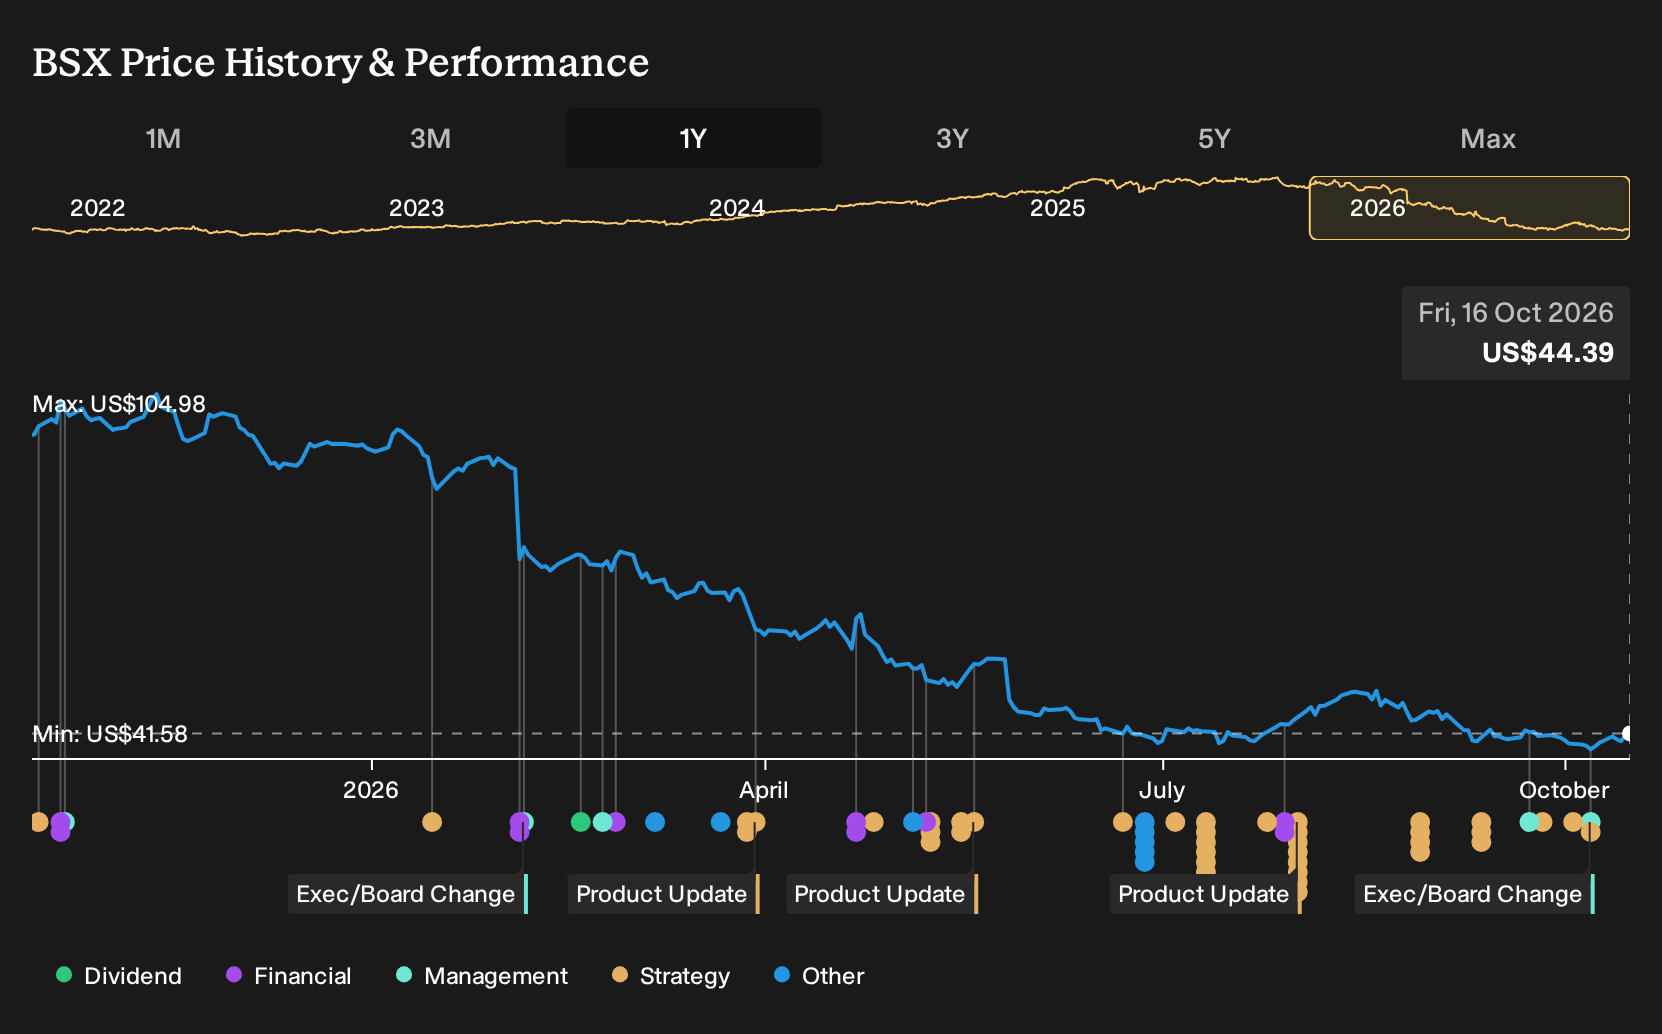
To own Boston Scientific, you need to be comfortable with a medical device group that is leaning into restructurings, acquisitions and new platforms while some cardiac businesses stay soft. The near term swing factor is whether core areas like Interventional Cardiology and MedSurg keep offsetting flat Electrophysiology and WATCHMAN activity as the firm works through cyberattack disruption.
The biggest current risk is execution. Management is committing to a large restructuring, heavier capital spending and the roughly US$14.5b Penumbra deal, while already managing higher debt and lower recent share returns. The COO transition and new segment structure look important for coordination, but do not change those financial and integration hurdles overnight.
The creation of the Interventional Therapies, Rhythm Solutions and MedSurg segments is the clearest operational link to the current catalyst mix. Boston Scientific is trying to line up leadership and P&L accountability with procedure types, care settings and upcoming products like FARAPULSE, WATCHMAN and future interventional launches that sit inside these new groupings.
For you as a shareholder, the question is whether this redesign helps or hinders delivery on the existing earnings and margin story while Penumbra, MiRus and the restructuring program roll through. Cleaner disclosure by segment could make it easier to track if Interventional Therapies and MedSurg are offsetting any Rhythm Solutions pressure and if cost savings are actually showing up.
Boston Scientific's current analyst narrative points to revenues of US$24.4b and earnings of US$4.4b by 2029, based on an assumed 5.1% yearly top line expansion and a move from US$3.7b of earnings today to that 2029 consensus level, which is about a US$0.7b increase in profit.
Uncover why Boston Scientific's fair value indicates a 35% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Boston Scientific’s more aggressive growth path for Electrophysiology and WATCHMAN. Before this COO and segment reshuffle, that bullish camp was modelling revenue of about US$28.0b and earnings of roughly US$4.7b by 2029. You can compare that to the baseline and decide which storyline feels closer to your own view, knowing both were shaped before this news and may evolve as the new structure is implemented.
Explore 6 other Boston Scientific fair value estimates, including one that suggests as much as 123% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Boston Scientific research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Boston Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Scientific's overall financial health at a glance.
Looking for more Boston Scientific investment ideas?
If this Boston Scientific reshuffle has you rethinking where capital goes next, it may help to broaden the search. A few focused screens can surface very different types of opportunities that fit your risk tolerance and time horizon.
- If stability and capital preservation matter most to you, check companies with resilient earnings profiles by running the 32 resilient stocks with low risk scores.
- For investors looking for quality at a sensible entry point, scan the value focused 33 high quality undervalued stocks.
- If reliable cash payouts are a priority, filter for companies with stronger income potential through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com