


American Water Works Company (AWK) Could Be 5% Undervalued On Infrastructure Upgrades
Recent updates at American Water Works Company (AWK) center on fresh infrastructure spending, including a $470,000 pipe replacement in West Virginia and a federally backed wildfire resilience project in California.
The fresh infrastructure work at American Water Works Company is landing against a modestly positive share price backdrop, with a 1-day share price return of 1.43% and a 7-day share price return of 4.70% at a recent level of $134.94.
Short-term momentum looks steady rather than explosive, since the 30-day share price return is down 2.05% and the 90-day share price return is down 0.13%, while the year-to-date share price return is 3.55%.
For investors watching the bigger arc, total shareholder return has declined 3.61% over the past year but delivered a 25.36% gain over three years. The 5-year total shareholder return is down 14.51%, suggesting the market is still weighing long-running capital spending and regulatory outcomes against income and dividend expectations.
Scan American Water Works Company alongside a curated 32 resilient stocks with low risk scores that also focuses on heavy infrastructure spending and regulated revenue for potentially steadier compounding through capital project cycles.
Bulls point to American Water Works Company’s regulated model and ongoing projects as a foundation for resilience. Skeptics focus on the muted long-term returns. Given these differing views, the key question is how the current valuation markers align with each perspective.
Most Popular Narrative: 4.6% Undervalued
At a last close of $134.94, American Water Works Company is trading a little below the most widely followed fair value estimate of $141.45, which anchors the story in a measured valuation gap rather than a deep discount.
Persistent population growth and urbanization across key U.S. states are still expected to support organic customer additions alongside new system takeovers. This can widen American Water Works Company’s revenue base as more households and businesses are billed for regulated water and wastewater services.
See why 35 investors see American Water Works Company as 5% undervalued.
Result: Fair Value of $141.45 (UNDERVALUED)
Still, the American Water Works Company story can fray if its roughly US$48b capital plan encounters regulatory pushback or if merger integration costs erode expected earnings.
Find out about the key risks to this American Water Works Company narrative.
Another View: What Multiples Say About American Water Works Company
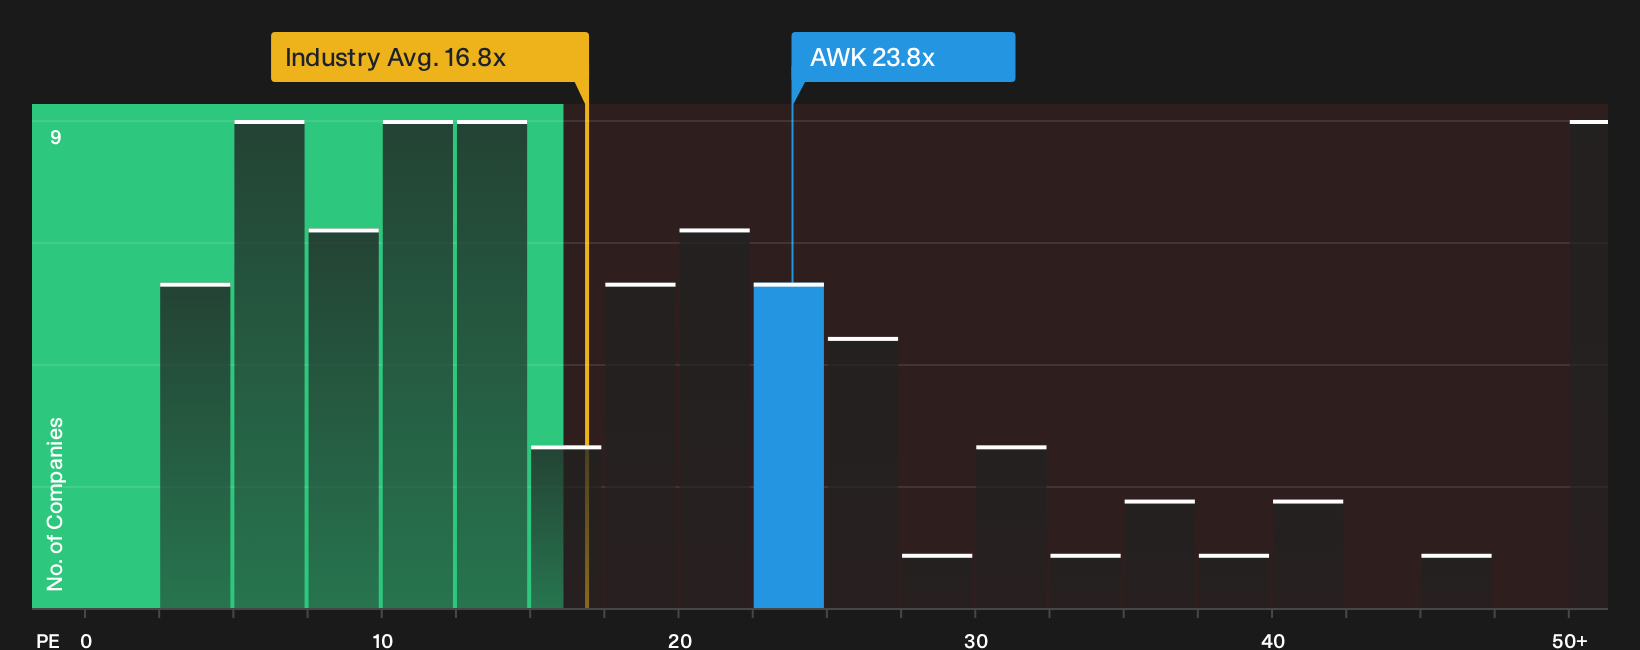
Our fair value estimate of $141.45 paints American Water Works Company as modestly undervalued. The picture changes when using a straightforward P/E lens. At 23.8x earnings versus a fair ratio of 20.8x, and above the global water utilities average of 16.8x and peer average of 22x, the stock looks expensive. That pricing gap raises a simple question: Are investors paying up for quality or just paying up?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around American Water Works Company can feel confusing, so move quickly from headline takes to your own view by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond American Water Works Company?
If you stop with American Water Works Company, you might miss opportunities that fit your goals even better. Use the screener to widen your opportunity set intelligently.
- Target potential mispricings by scanning a focused universe of 33 high quality undervalued stocks that pair solid fundamentals with prices that sit below many investors’ radar.
- Prioritize resilience by filtering for a list of solid balance sheet and fundamentals (25 results) so you can concentrate on businesses with stronger financial footing when conditions get tougher.
- Stay ahead of the crowd by reviewing a 20 high quality undiscovered gems that highlights quality companies before attention and expectations potentially build.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com