


Denali Therapeutics (DNLI) Looks Undervalued On Paper, Where Does Fair Value Really Sit?
Short term price moves and recent performance
Denali Therapeutics (DNLI) recently closed at US$17.61, with the share price down about 4% on the day and weaker over the past week and month.
Returns have also declined over the past 3 months, while the year to date move and 1 year total return remain positive. This presents a mixed picture for recent holders.
Across the past year, Denali Therapeutics has combined a weaker 3 month share price return with a modestly positive 1 year total shareholder return. This suggests recent selling pressure has cooled earlier momentum as investors reassess both future growth potential and perceived risk around its pipeline and valuation.
Spot under-pressure biopharma stories like Denali Therapeutics while they are still resetting expectations by scanning the 20 high quality undiscovered gems with similar fundamentals and under-the-radar sentiment shifts.Denali Therapeutics now trades near US$17, with analyst targets and intrinsic estimates sitting meaningfully higher on average. The next step is to work out where fair value plausibly sits within that range.
Most Popular Narrative: 50% Undervalued
On the most followed narrative, Denali Therapeutics carries an implied fair value of about $35.44 against a last close of $17.61. This puts the current share price well below that reference point and raises a clear question about whether the blood brain barrier platform and rare disease portfolio are being fully credited.
The enzyme transport vehicle franchise targets multiple lysosomal storage disorders where biologics are already an accepted treatment class. Denali Therapeutics expects each program to represent several hundred million dollars or more in potential annual market opportunity, which can influence long term revenue diversification and earnings resilience.
See why 1 investors see Denali Therapeutics as 50% undervalued.
At the same time, Denali Therapeutics is still unprofitable, reported a loss of $511.5 million, and only generated about $3.6 million of revenue in the first full quarter from AVLAYAH out of the roughly $3.6 million trailing figure. As a result, the implied upside in this framework leans heavily on forecasts that revenue can compound quickly while margins move from deep losses toward the 16.9% industry level used in the narrative. That path also assumes analysts remain comfortable with a very rich 134.7x P/E on the projected $63.9 million of earnings by 2029. This is well above the 17.3x multiple cited for the broader US biotech group and highlights how much optimism is embedded in the long term story, even if the stock currently trades at a discount to the narrative fair value.
Result: Fair Value of $35.44 (UNDERVALUED)
Still, the Denali Therapeutics story can change quickly if AVLAYAH prescriptions plateau in that small Hunter syndrome pool, or if Alzheimer’s trials run into delays or weak data.
Find out about the key risks to this Denali Therapeutics narrative.
Another View on Denali Therapeutics Valuation
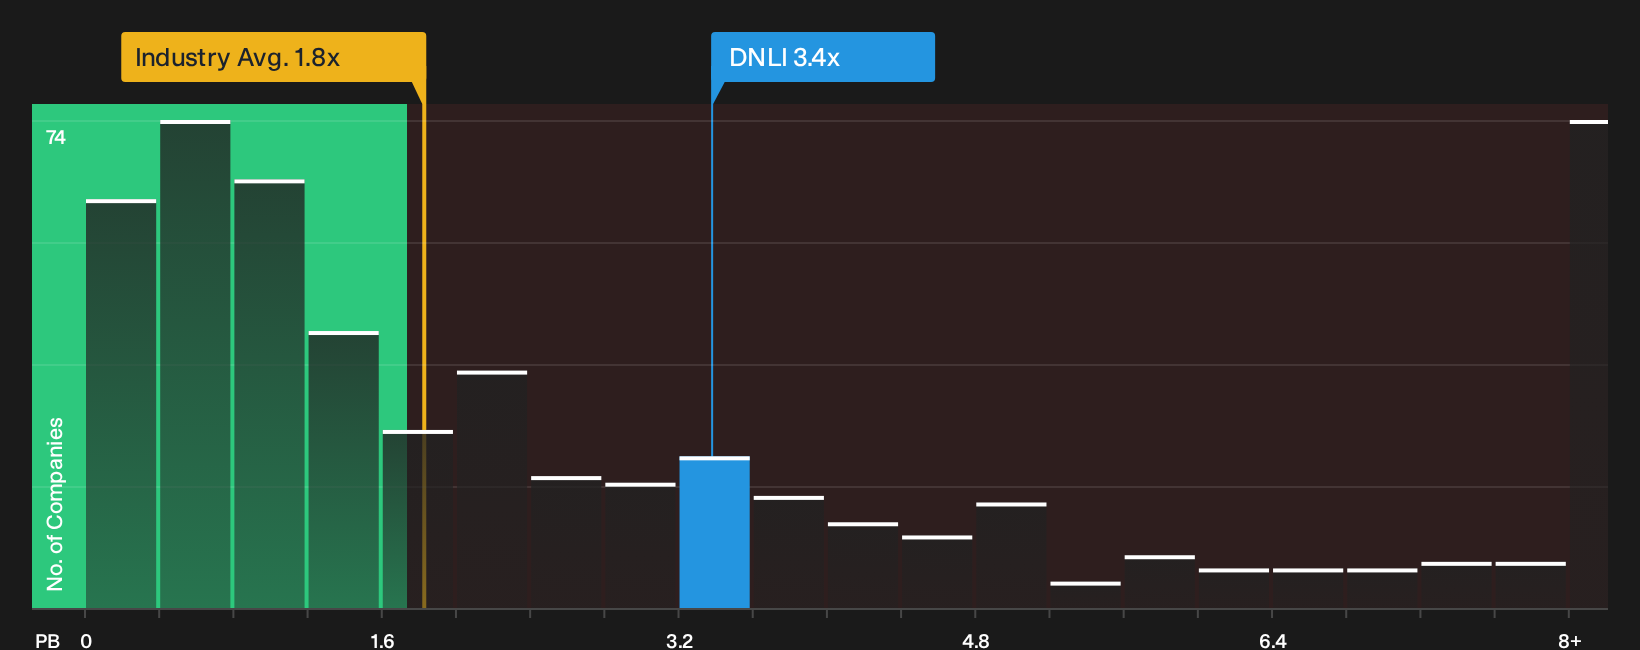
The analyst narrative presents Denali Therapeutics as roughly 50% undervalued relative to a fair value of $35.44. A simpler check using the P/B ratio tells a different story. DNLI trades at 3.4x book value versus 1.9x for the wider US Biotechs group and 4.6x for closer peers. This points to richer pricing than the sector, even if it appears cheaper than similar stocks. For an investor, that gap suggests both potential upside if peers remain the reference point and potential downside if the wider industry becomes the main comparison, so which reference feels more realistic to you over time?
To see how those book value signals translate into practical valuation checks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Denali Therapeutics can feel confusing, so move quickly, review the full data set, and weigh both the 1 or more concerns and the 1 or more positives for yourself by checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Denali Therapeutics?
You have seen how complex Denali Therapeutics can be, so do not stop here. Put that curiosity to work by scanning fresh opportunities with clear data on your side.
- Target potential mispricings by running your filters across 33 high quality undervalued stocks, so you are not leaving possible bargains on the table.
- Prioritize resilience in choppier markets and focus on companies with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Shift attention toward under-the-radar stories with strong fundamentals before the crowd catches on by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com