


Capricorn Metals (ASX:CMM) Could Be 26% Undervalued On Rising Cost Concerns
Rising operating costs at Capricorn Metals (ASX:CMM) have become the main talking point after fresh commentary questioned whether current earnings fully support its premium P/E multiple relative to other metals producers.
Recent trading has been choppy for Capricorn Metals, with a 1-day share price return of 4.42% lifting the stock to A$14.42 after a 30-day share price return that fell 3.35%. Over the same period, the 90-day share price return gained 22.72%, and the 3-year total shareholder return reached just over 3x, suggesting longer term momentum remains intact while near term moves reflect shifting views on cost risk and the current P/E premium.
Spot opportunities beyond Capricorn Metals by comparing how other gold producers are priced on earnings and costs in our curated 36 elite gold producer stocks.For Capricorn Metals, a choppy share price, rising costs and a premium P/E now pull in opposite directions. Is most of the return already in the rear-view mirror, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 26% Undervalued
Capricorn Metals is being framed as undervalued, with a narrative fair value of A$19.52 compared with the last close at A$14.42. This places the current premium P/E debate in the context of a much larger free cash flow and production story.
The updated Mt Gibson pre feasibility study outlines a 19.25 year mine life with production ramping to about 260,000 ounces per year and an estimated A$12 billion in pre tax free cash flow from 3.5 million ounces of production, which can materially influence future operating cash flow and net profit.
See why 6 investors see Capricorn Metals as 26% undervalued.
Result: Fair Value of A$19.52 (UNDERVALUED)
Still, the Capricorn Metals story can quickly look different if Mt Gibson development slips on timing or costs, or if investors become reluctant to pay a premium P/E.
Find out about the key risks to this Capricorn Metals narrative.
Another View: What Multiples Say About Capricorn Metals
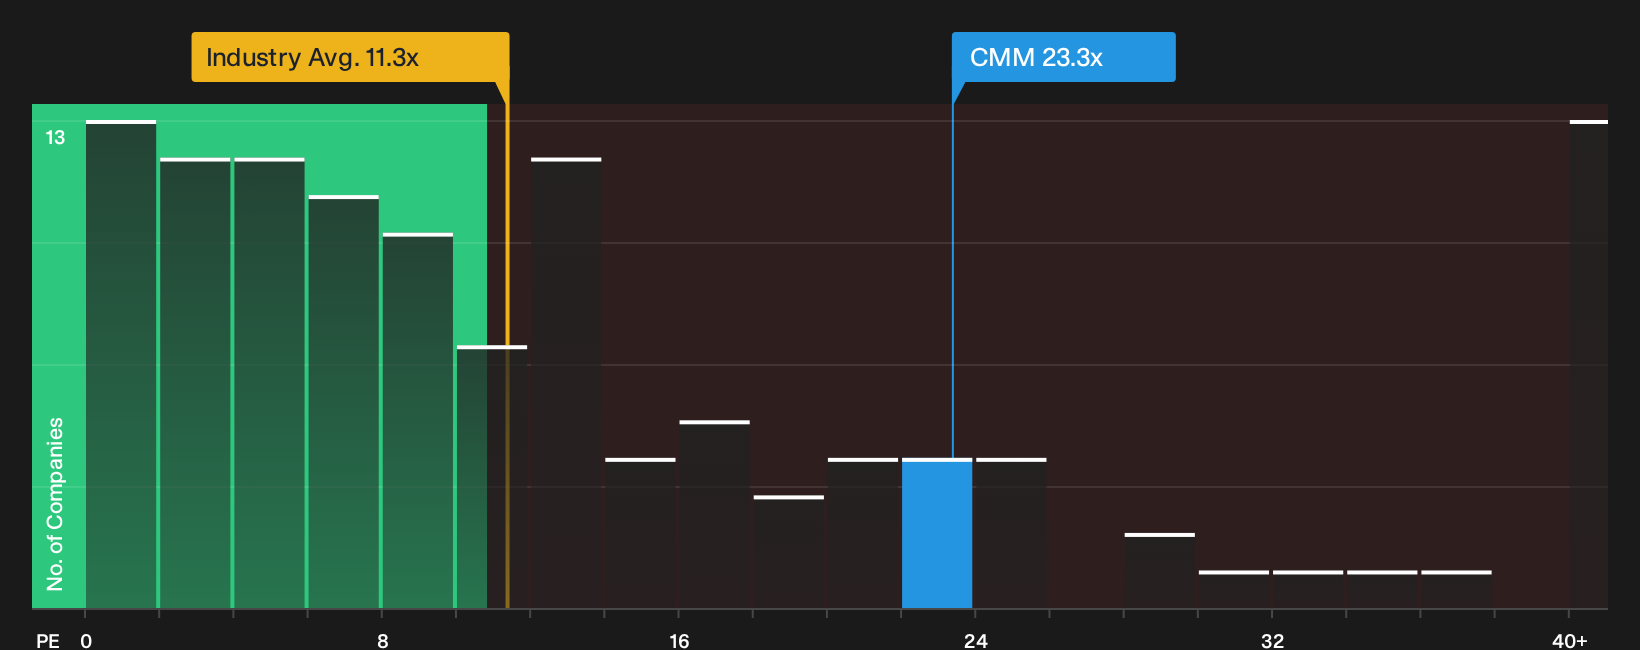
There is a very different message when you stop looking at fair value estimates and focus on what the market is actually paying for Capricorn Metals today. On a P/E of 23.3x, the stock trades above both its own fair ratio of 21.3x and the Australian Metals and Mining industry on 10.6x. That premium can be read as confidence in the growth story or as valuation risk if expectations cool.
For investors weighing that gap between P/E and fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether the optimism around Capricorn Metals really stacks up for you? Take a moment to test the numbers yourself, weigh the narrative against the risks, and then review the 4 key rewards.
Looking for more investment ideas beyond Capricorn Metals?
If Capricorn Metals has sharpened your focus on valuation and risk, do not stop here. Use a few minutes today to scan fresh ideas that match your style.
- Target value first and hunt for mispriced quality through the 4 high quality undervalued stocks.
- Prioritise resilience and stress test your downside by running your filters through the 6 resilient stocks with low risk scores.
- Spot rising opportunities early and search for future leaders with the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com