


How Investors Are Reacting To Lennar (LEN) Earnings Miss
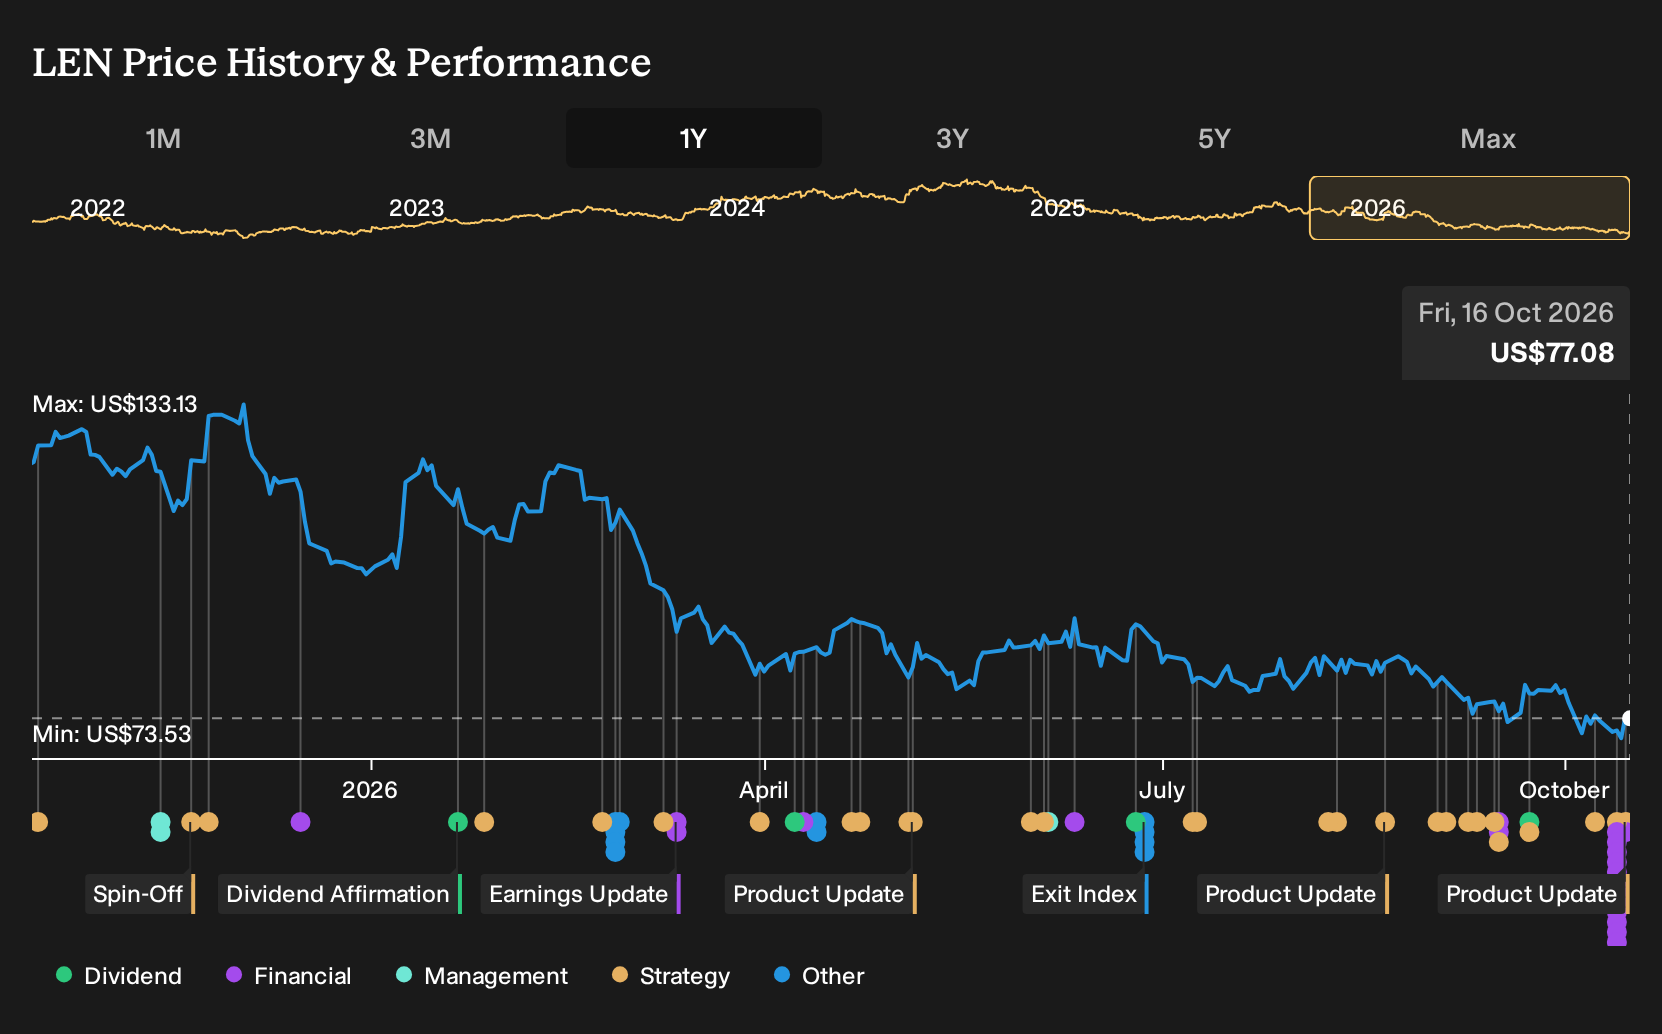
- Lennar reported weaker than expected Q3 fiscal 2026 results, with both adjusted earnings and revenue missing estimates and full year home delivery guidance reduced in the face of softer housing demand and elevated mortgage rates.
- The earnings shortfall and guidance cut highlight pressure on Lennar's volume focused model, as affordability challenges and demand softness test its ability to keep build costs, incentives and cycle times aligned with prior efficiency ambitions.
- We will now look at how Lennar's earnings miss and reduced delivery outlook could reshape the broader investment narrative around the business.
Lennar Investment Narrative Recap
To stay comfortable as a Lennar shareholder, you need to believe the asset light, volume driven model can still work despite softer housing demand, higher mortgage rates and thinner margins. The near term swing factor is whether Lennar can keep homes affordable enough, through product mix and incentives, to hold sales pace without eroding profitability further.
The biggest risk right now is affordability worsening, which could pressure already lower net margins and test its reduced 2026 delivery target. The latest results and guidance cut reinforce that risk rather than changing it. They keep the focus squarely on execution, cost discipline and capital allocation decisions over the next few quarters.
The clearest operational development tied to this story is Lennar’s October 2026 debt issuance. The firm settled US$300m of 5.700% Senior Notes due 2029 and US$300m of 5.950% Senior Notes due 2032, both guaranteed by certain subsidiaries and issued under its existing indenture structure.
That fresh US$600m of fixed rate funding gives Lennar more room to keep building communities like The Foundry in downtown Las Vegas and Foxwood in Alabama while it deals with weaker demand and lower margins. For you, the question is whether using higher cost debt for general corporate purposes keeps returns attractive if affordability or land costs worsen from here.
What The Latest Lennar Forecasts Assume
Lennar's current analyst narrative points to US$40.6b in revenue and US$2.7b in earnings by 2029, based on an assumed 8.3% yearly revenue growth rate and an earnings increase of about US$1.4b from US$1.3b today.
Uncover why Lennar's fair value is assessed as being in line with its current price.
Exploring Other Perspectives
One alternate view focuses on demand, not efficiency. The most bearish analysts think Lennar’s new communities like The Foundry will struggle to offset affordability pressure. They were only penciling in revenue of about US$35.7b and earnings of roughly US$1.1b by 2029, far below consensus. That gap shows how widely opinions differ and invites you to review both sets of assumptions with fresh eyes after this earnings miss.
Explore 4 other Lennar fair value estimates, including one that suggests as much as 27% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lennar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lennar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lennar's overall financial health at a glance.
Looking For More Lennar Investment Ideas Beyond Housing
Once you have a view on Lennar, it can help to widen the lens and compare it with other companies that line up better with your own risk, income and quality preferences. The Simply Wall St Screener lets you filter by fundamentals rather than headlines so you can build a watchlist that actually fits how you want to invest.
- If you care most about financial strength and staying power, start with a list of solid balance sheet and fundamentals (25 results) that combine sturdy balance sheets with solid underlying fundamentals.
- For readers hunting for mispriced opportunities, scan a 33 high quality undervalued stocks that pair healthy cash generation with what looks like room for the market to reassess them.
- If reliable income is your priority, focus on companies in the 8 dividend fortresses that aim to balance higher yields with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com