


Did Rent Deferrals Just Shift Blue Owl Capital (OWL) Investment Narrative?
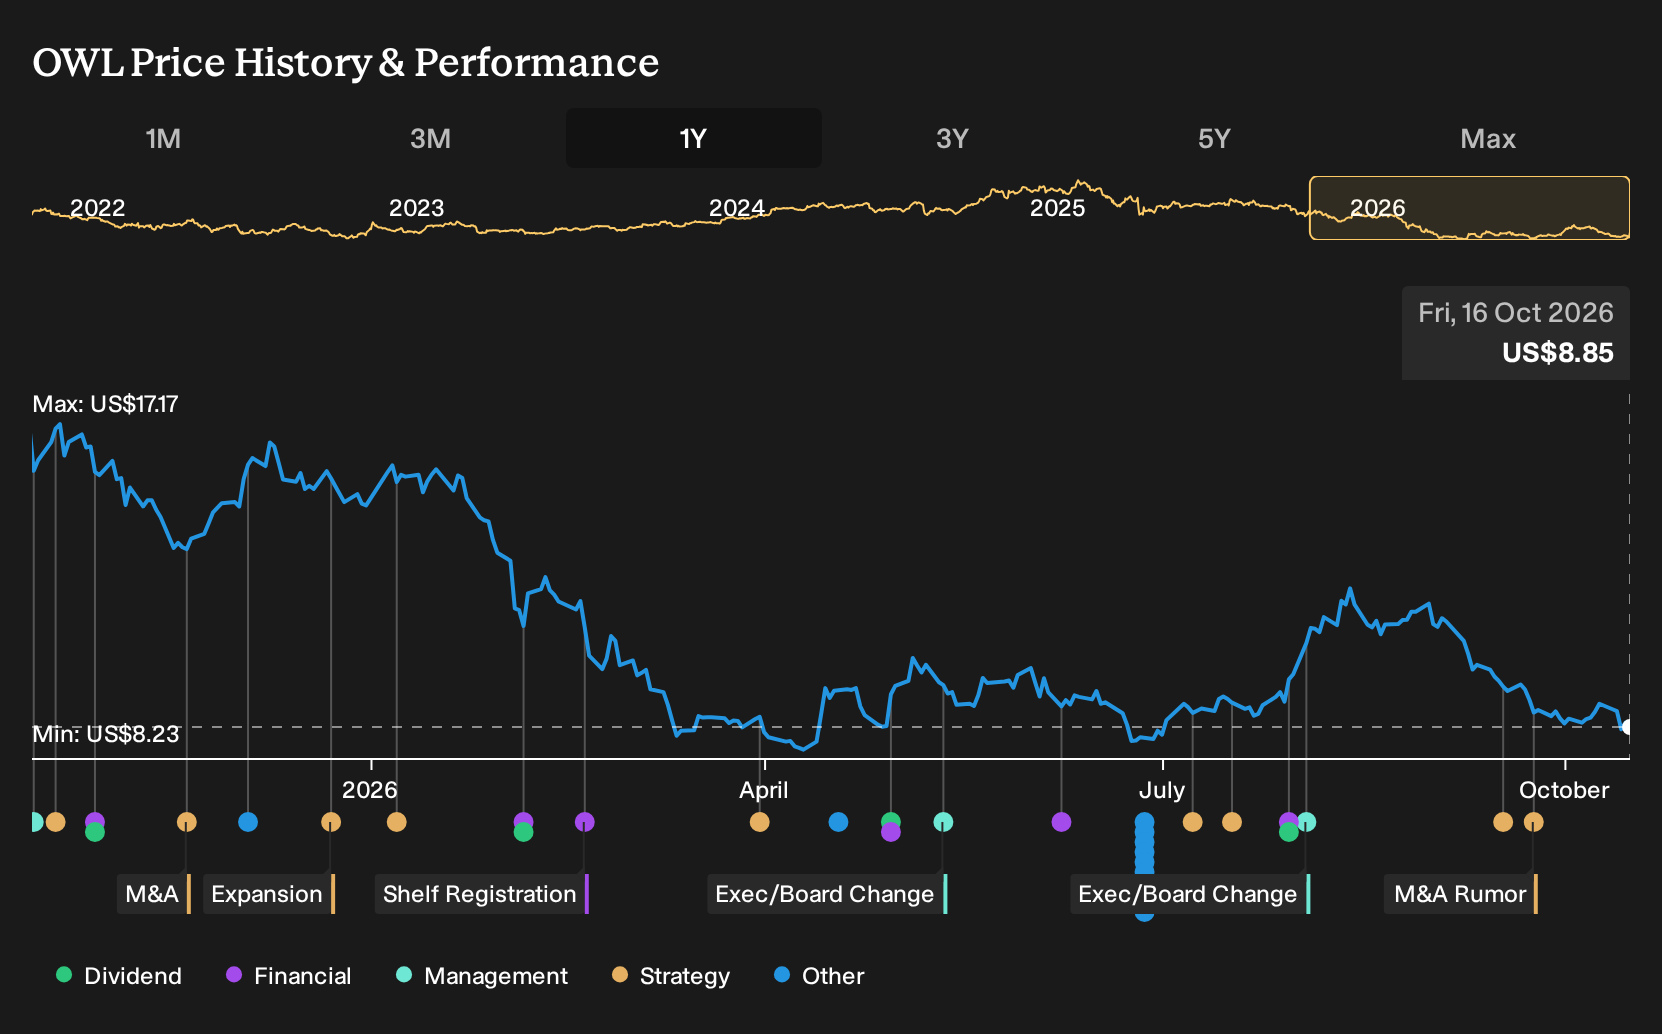
- Blue Owl Capital has increased its focus on AI oriented data center and digital infrastructure assets, even as Oracle’s past force majeure notice on the Jupiter project defers roughly US$147 million to US$180 million of rent for up to three years.
- The combination of rising AI infrastructure exposure and delayed Jupiter cash inflows sharpens attention on how Blue Owl Capital manages contract timing, tenant risk and real assets execution.
- This analysis examines how Blue Owl Capital's investment narrative is affected by heavier AI data center exposure and delayed Jupiter cash flows.
Blue Owl Capital Investment Narrative Recap
To own Blue Owl Capital, you need to be comfortable with an asset manager that leans hard into permanent capital, private credit and real assets, including a sizable AI data center footprint. The near term story revolves around converting undeployed capital into fee paying assets while keeping fundraising steady despite recent softer flows and capped withdrawals in some vehicles.
The Jupiter rent deferral and wider AI infrastructure push put execution risk in real assets in sharper focus but do not alter the core earnings engine in the short run. The biggest current swing factor is whether fee paying AUM grows faster than any redemption pressure, while the key risk sits in project delays and liquidity concerns feeding through to sentiment and revenue.
The Oracle force majeure on Project Jupiter is the disclosure that matters most here. Around US$147 million to US$180 million of rent is now pushed out for up to three years, which slows expected cash inflows from that asset and delays some real estate economics that investors had been watching closely.
That pause lands right as Blue Owl Capital increases its AI infrastructure exposure through a digital infrastructure real estate vehicle. The focus now is on pacing. Watch how quickly management replaces delayed Jupiter economics with other fee generating deployments, how concentrated tenant risk becomes in the AI data center book and whether these assets deepen or dilute the firm’s broader fundraising and margin ambitions.
Blue Owl Capital's narrative projects US$3.5b revenue and US$847.0m earnings by 2029. This assumes 5.8% yearly revenue growth and an earnings increase of about US$766.1m from US$80.9m today.
Discover how Blue Owl Capital's fair value suggests a 42% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate angle on Blue Owl Capital puts far more weight on data center execution risk. The most pessimistic analysts were already using slower 4.7% revenue growth and a lower US$3.4b revenue path by 2029, paired with a 9.3x P/E. Those views came before the Jupiter and AI infrastructure headlines, so opinions may evolve.
Explore 7 other Blue Owl Capital fair value estimates, including one that suggests as much as 88% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Blue Owl Capital research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Blue Owl Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Blue Owl Capital's overall financial health at a glance.
Looking For More Ideas Beyond Blue Owl Capital?
If the Blue Owl Capital story has you thinking more broadly about where to put fresh capital to work, casting a wider net with a structured search can help you compare risk, quality and income potential side by side.
The Simply Wall St Screener lets you scan the market using clear filters so you can line up different opportunities against the same criteria and decide which ones deserve deeper research.
- For investors who want quality businesses that the market may be overlooking, start with a basket of 20 high quality undiscovered gems and see which ones justify a place on your watchlist.
- If capital protection and balance sheet strength sit high on your checklist, narrow the field using a 32 resilient stocks with low risk scores that prioritises resilience over excitement.
- Income focused investors can sift for consistency and yield by running a screen built around 8 dividend fortresses that meet your preferred payout profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com