


Parker-Hannifin (PH) Has Investors Looking Closer After Its Latest Update
Parker-Hannifin (PH) drew fresh attention after its Aerospace Systems segment reported 13.3% organic revenue growth in fiscal Q4 2026, along with an all-time high aerospace backlog of US$8.5 billion and positive fiscal 2027 sales guidance.
Recent trading hints at steady enthusiasm building around Parker-Hannifin, with the share price up 4.85% over the past month and a year-to-date share price return of 7.76%, alongside a much stronger 1-year total shareholder return of 32.41% and a very large 5-year total shareholder return of 242.87% that reflects how investors have been reacting to the Aerospace Systems momentum and the pending CIRCOR acquisition.
Scan other aerospace and industrial momentum stories alongside Parker-Hannifin by checking the hand-picked 41 power grid technology and infrastructure stocks that could benefit from similar long-cycle infrastructure demand.
After a run that pushed Parker-Hannifin toward US$1,000 a share on aerospace strength and optimistic guidance, the real tension now is simple: Does it make more sense to step in at this price or wait for a cheaper entry point as the valuation resets?
Most Popular Narrative: 17% Undervalued
The most followed view on Parker-Hannifin pegs fair value at about $1,163 per share, above the last close of $963.34. That gap rests heavily on how the business leans into higher margin, longer cycle platforms.
The enlarged portfolio of longer cycle, higher margin businesses, including Aerospace, Engineered Materials and Filtration, now represents about 65% of pro forma sales and includes recently added filtration assets. This can increase the share of recurring and aftermarket revenue and support more stable earnings and cash generation across economic cycles.
See why 46 investors see Parker-Hannifin as 17% undervalued.
Result: Fair Value of $1,163 (UNDERVALUED)
Still, the Parker-Hannifin story depends on organic demand growing faster than the recent 3.2% pace, and on its premium valuation holding up if expectations are tested.
Find out about the key risks to this Parker-Hannifin narrative.
Another View: Parker-Hannifin Looks Expensive On Earnings
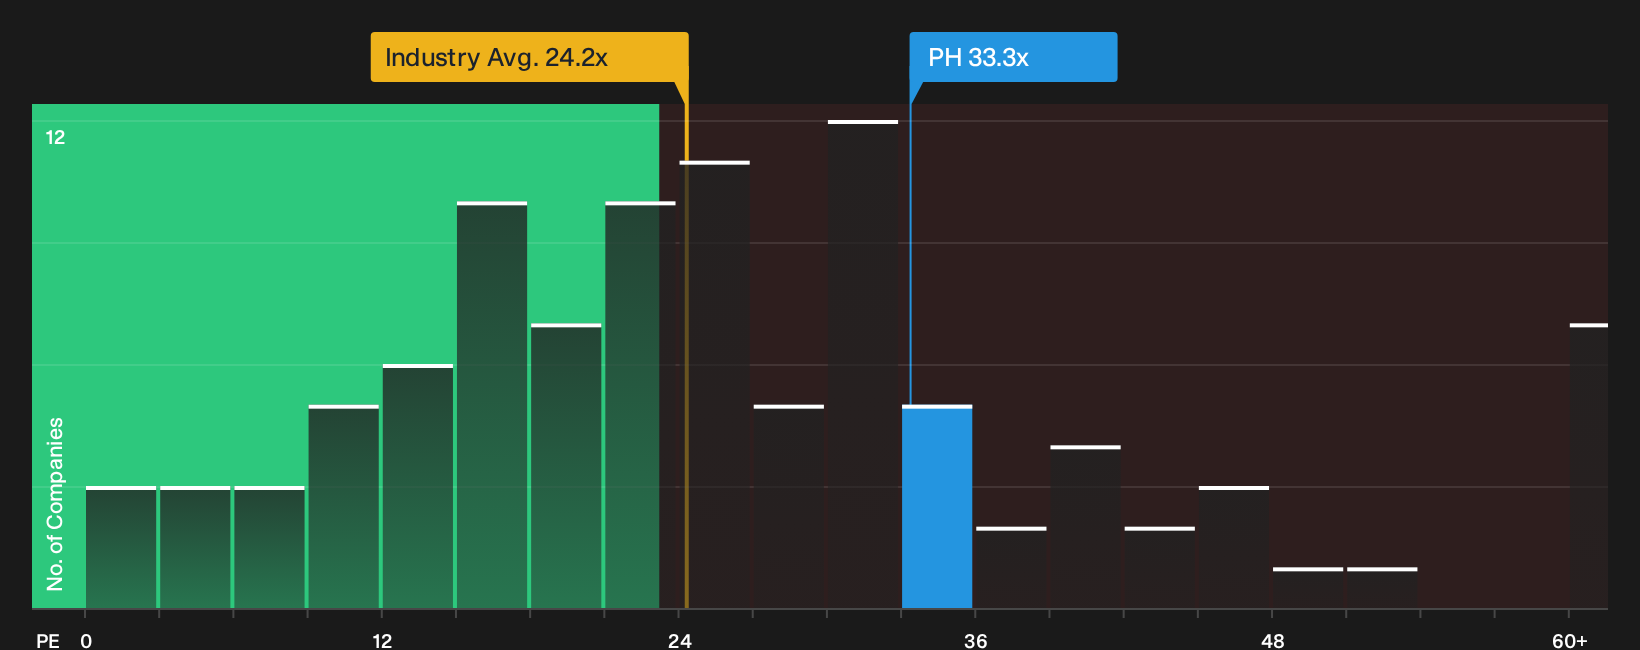
Step away from fair value models for a moment and just look at what people are paying for Parker-Hannifin today. The shares trade on a P/E of 33.3x, compared with 24.2x for the wider US Machinery group, 24.3x for closer peers, and a fair ratio estimate of 29x. That gap points to meaningful rerating risk if expectations cool, so are you comfortable paying up for this quality, or would you rather wait for the multiple to compress?
To see how this price tag stacks up against the underlying numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals on Parker-Hannifin leave you split, move quickly, review the data yourself, and consider both the potential upside and the risk flags. Start by checking the 2 key rewards and 2 important warning signs.
Looking for more Parker-Hannifin style investment ideas?
If Parker-Hannifin has you thinking bigger about portfolio quality, do not stop here. Broaden your watchlist now, or risk missing stronger opportunities elsewhere.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that may hold up under tougher conditions.
- Hunt for quality at a potential discount by reviewing a focused 33 high quality undervalued stocks that filters for both fundamentals strength and pricing appeal.
- Spot early-phase opportunities before they gain wider attention by checking a hand-picked 20 high quality undiscovered gems that screens for robust business quality hiding off the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com