


Zscaler (ZS) Stock Still Looks Undervalued Despite Its 33% Five Year Slump
Zscaler has been through a rough patch for long term holders, and the recent swings now put a sharper spotlight on whether the current share price lines up with the cash flows the business is expected to produce. With AI security in focus and new partnerships in play, the question is how much of that story is already embedded in the valuation.
- Over the past 5 years, Zscaler shares have declined 32.6%, which puts extra weight on whether the underlying cash generation profile supports rebuilding investor confidence from here.
- Management is leaning hard into AI driven security and broader platform partnerships, which can influence how quickly revenue converts into cash and how much investment is needed to support that plan.
- Prefer to judge Zscaler on sales? See why Zscaler's 10.1x P/S tells a different valuation story.
The issue now is whether Zscaler's current market price is justified by its cash flows when assessed using a Discounted Cash Flow (DCF) view.
If Zscaler's recent swings have you reassessing risk and reward, a focused screen of other AI exposed software stocks can be a useful second reference point via 37 AI small caps.
Does Zscaler Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here values Zscaler based on the cash it is expected to produce for shareholders over time. Latest twelve month free cash flow sits at about $805.9 million, and the projections used in the model assume that this pool of cash continues growing rather than shrinking.
Those cash flow estimates climb into the low single digit billions of dollars by the early 2030s, which reflects a business that continues to scale rather than simply hold steady. Because Zscaler recently reaffirmed long term free cash flow margin goals while AI security spending remains in focus, the DCF output is meaningfully above the current $207.38 share price. This gap indicates that the market is still pricing in execution and governance risks despite the ambitious ARR targets. Find out what Zscaler could be worth using our Discounted Cash Flow (DCF) estimate.
The Zscaler Narrative: What Would Justify Today's Price?
Narratives for Zscaler pick up where the DCF puzzle leaves off and outline what path for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today's price on Simply Wall St's Community page. Each scenario links a fair value to a clear storyline around Zscaler's potential catalysts and key risks so you can monitor which version of events appears to be unfolding over time.
Community views on Zscaler are split between those who see the current price as leaving room for more AI driven ARR, and those who think expectations already look full.
Bull case: 11% undervalued
"Z Flex customers show about 30% higher ARR uplift than others, which supports larger multi year commitments and can help operating margins..."
Discover why this Narrative puts Zscaler at 11% undervalued.
Bear case: 21% overvalued
"Management plans to “invest aggressively” to pursue what it describes as a large market and to extend into areas like agentic operations and AI security..."
Explore why this Narrative puts Zscaler at 21% overvalued.
The Zscaler share price is only one piece of the investment story
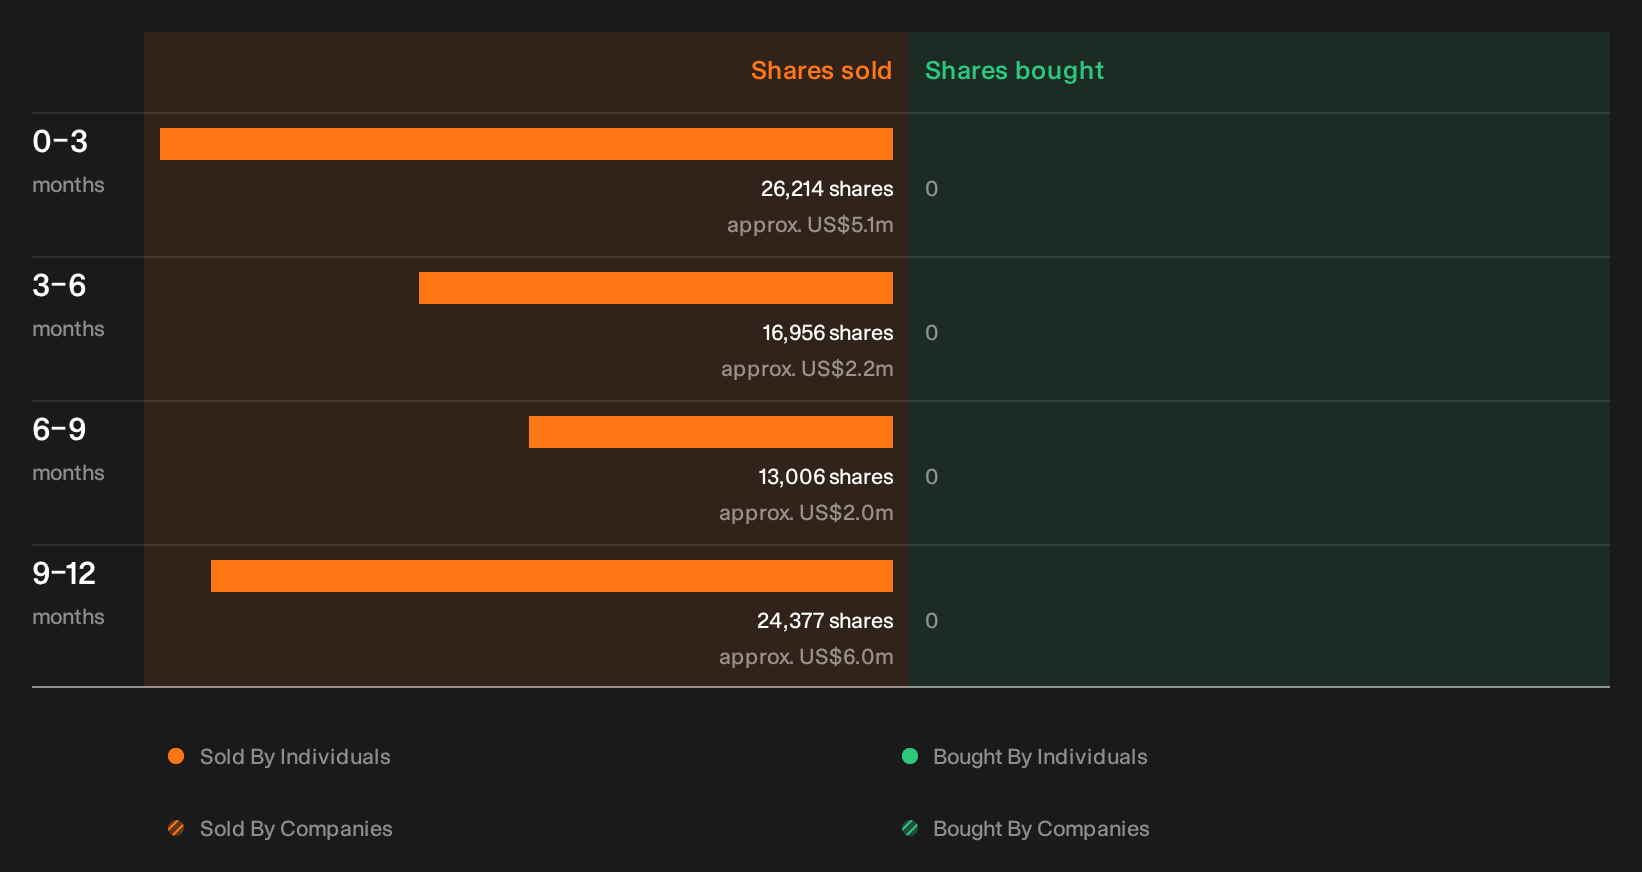
Valuation work sets the stage, but recent share sales by people inside Zscaler can hint at very different motivations and risk perceptions, and the specific sellers, sizes and context are still for you to review. See the recent insider selling flagged for Zscaler.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com