


Does Debt Refinancing Change The Bull Case For Live Nation Entertainment (LYV)?
- Live Nation Entertainment has issued US$730 million of 7.125% senior notes and €600 million of 6.125% senior notes, both due 2032, with guarantees from key restricted subsidiaries and plans to redeem its 6.500% senior secured notes due 2027.
- The refinancing reshapes Live Nation Entertainment's debt profile by swapping secured 2027 obligations for longer dated unsecured bonds, which can influence interest costs, covenant flexibility, and how much cash stays available for venue investment and ticketing technology.
- We will now examine how Live Nation's multi currency refinancing and planned 2027 note redemption could influence its broader investment narrative.
Live Nation Entertainment Investment Narrative Recap
To own Live Nation Entertainment, you need to believe live events can keep drawing fans and brands while the firm scales its venue footprint and Ticketmaster platform. The key near term swing factor is execution on that growth plan while still loss making at the net income line. This refinancing mainly affects funding, so it does not meaningfully change that operating catalyst.
The biggest near term risk is still regulatory pressure on Ticketmaster, not the maturity profile shift. Legal proceedings and open ticketing requirements could affect pricing, venue contracts, and fee bearing ticket volumes. Higher coupon debt simply makes strong cash generation and disciplined capital allocation more important if those pressures intensify.
The most relevant announcement here is the multi currency senior notes offering due 2032, which Live Nation Entertainment plans to use to redeem its 6.500% senior secured notes due 2027. That move extends maturities and transitions a chunk of borrowing from secured to unsecured, while keeping guarantees from key restricted subsidiaries in place.
For you as a shareholder, the link to catalysts is indirect but real. Large venue and technology projects, along with expansion in underpenetrated markets, rely on steady access to capital. At the same time, Ticketmaster faces ongoing regulatory risk and Live Nation reports all liabilities from higher risk funding sources, so balance sheet choices matter for how resilient that growth story can be if legal or operating conditions tighten.
Live Nation Entertainment's current analyst story points to revenue of US$34.4b and earnings of US$996.6m by 2029, built on expected top line growth of 9.4% a year and a swing in earnings of roughly US$1.25b from today’s US$258.0m loss to that 2029 profit level.
Uncover why Live Nation Entertainment's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
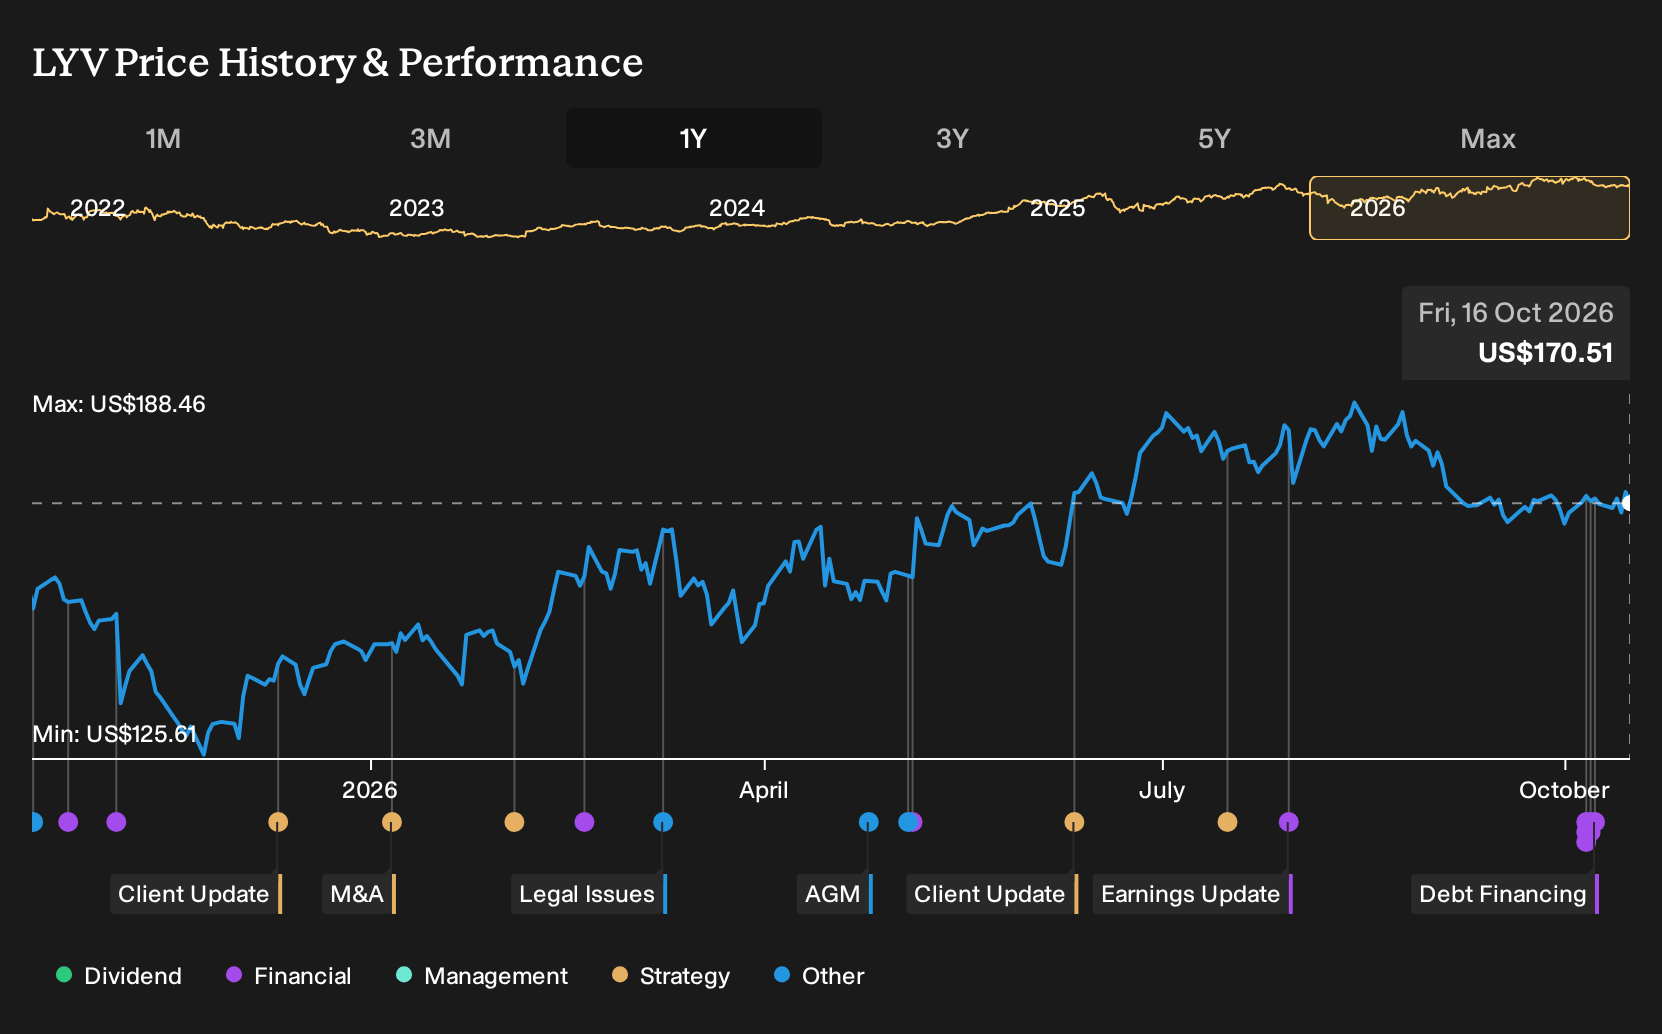
The two fair value estimates from the Simply Wall St Community cluster between about US$169 and US$202, which leaves room for very different conclusions on Live Nation Entertainment. Those contributors formed their views before the new multi currency 2032 notes. You now need to weigh that fresh interest cost and regulatory overhang against those prior forecasts, and explore alternative viewpoints.
Explore another Live Nation Entertainment fair value estimate, including one that suggests up to 18% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Trust your own analysis and go with your instincts.
- A great starting point for your Live Nation Entertainment research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Live Nation Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Live Nation Entertainment's overall financial health at a glance.
Looking for more investment ideas beyond Live Nation Entertainment?
Once you have a view on Live Nation Entertainment, it can help to compare that thesis with other businesses that fit different balance sheet, income, or risk profiles. The Simply Wall St Screener gives you a quick way to line up those contrasts and pressure test where you really want your money working.
- For investors who want staying power to matter as much as upside, focus on companies with strong finances and conservative funding by starting with this 32 resilient stocks with low risk scores.
- If you care most about getting quality at a price that looks reasonable on fundamentals, sort through our fundamentals led 20 high quality undiscovered gems.
- When reliable cash generation and cleaner leverage ratios rank high on your checklist, begin with a curated list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com