


Do Higher Mortgage Rates Change The Bull Case For Sun Communities Stock (SUI)?
- Recent commentary points to higher mortgage rates near three year highs. This is making it harder for first time buyers to qualify for traditional home purchases, which is pushing some demand toward more affordable housing options provided by Sun Communities.
- This shift in affordability pressure highlights how Sun Communities’ manufactured housing and RV communities can capture households priced out of FHA financed single family homes. This may affect site demand, occupancy mix and long term portfolio planning.
- The focus also turns to how Sun Communities’ investment narrative could be influenced by affordability pressure pushing renters toward manufactured housing communities.
Sun Communities Investment Narrative Recap
To own Sun Communities, you need to believe that persistent U.S. housing affordability pressure keeps interest strong for manufactured housing and RV sites, even as traditional homebuying slows under higher mortgage rates. In the short term, the key variable is how effectively management converts that demand into steady occupancy and rent, without leaning too hard on price in already stretched household budgets.
The biggest operational risk still sits in execution. Rebalancing the RV mix between transient and annual guests, integrating tech across the platform, and managing a high debt load all matter more than the latest rate headline. The fresh Hold view from Argus does not materially change those near term priorities.
The Argus rating update that pegs Sun Communities at High for management and financial strength, with a Medium industry subrating and Low growth score, is the most relevant new datapoint. It reinforces the idea that the balance sheet and day to day operations are viewed as solid, even if near term growth expectations are more muted.
For catalysts, that matters because the core story still leans on housing affordability pressure, Park Holidays divestiture plans, and tech upgrades in the RV network, rather than rapid top line expansion. The Argus stance effectively highlights the trade off you are weighing: strong management and balance sheet discipline on one side, and RV mix risk, past governance issues, and slower revenue growth assumptions on the other.
Sun Communities’ current analyst narrative points to revenues of US$2.3b and earnings of US$493.8m by 2029, with earnings moving from US$136.5m today to that 2029 consensus level. This implies roughly a 3.6x increase in profit and a flat revenue line over the period.
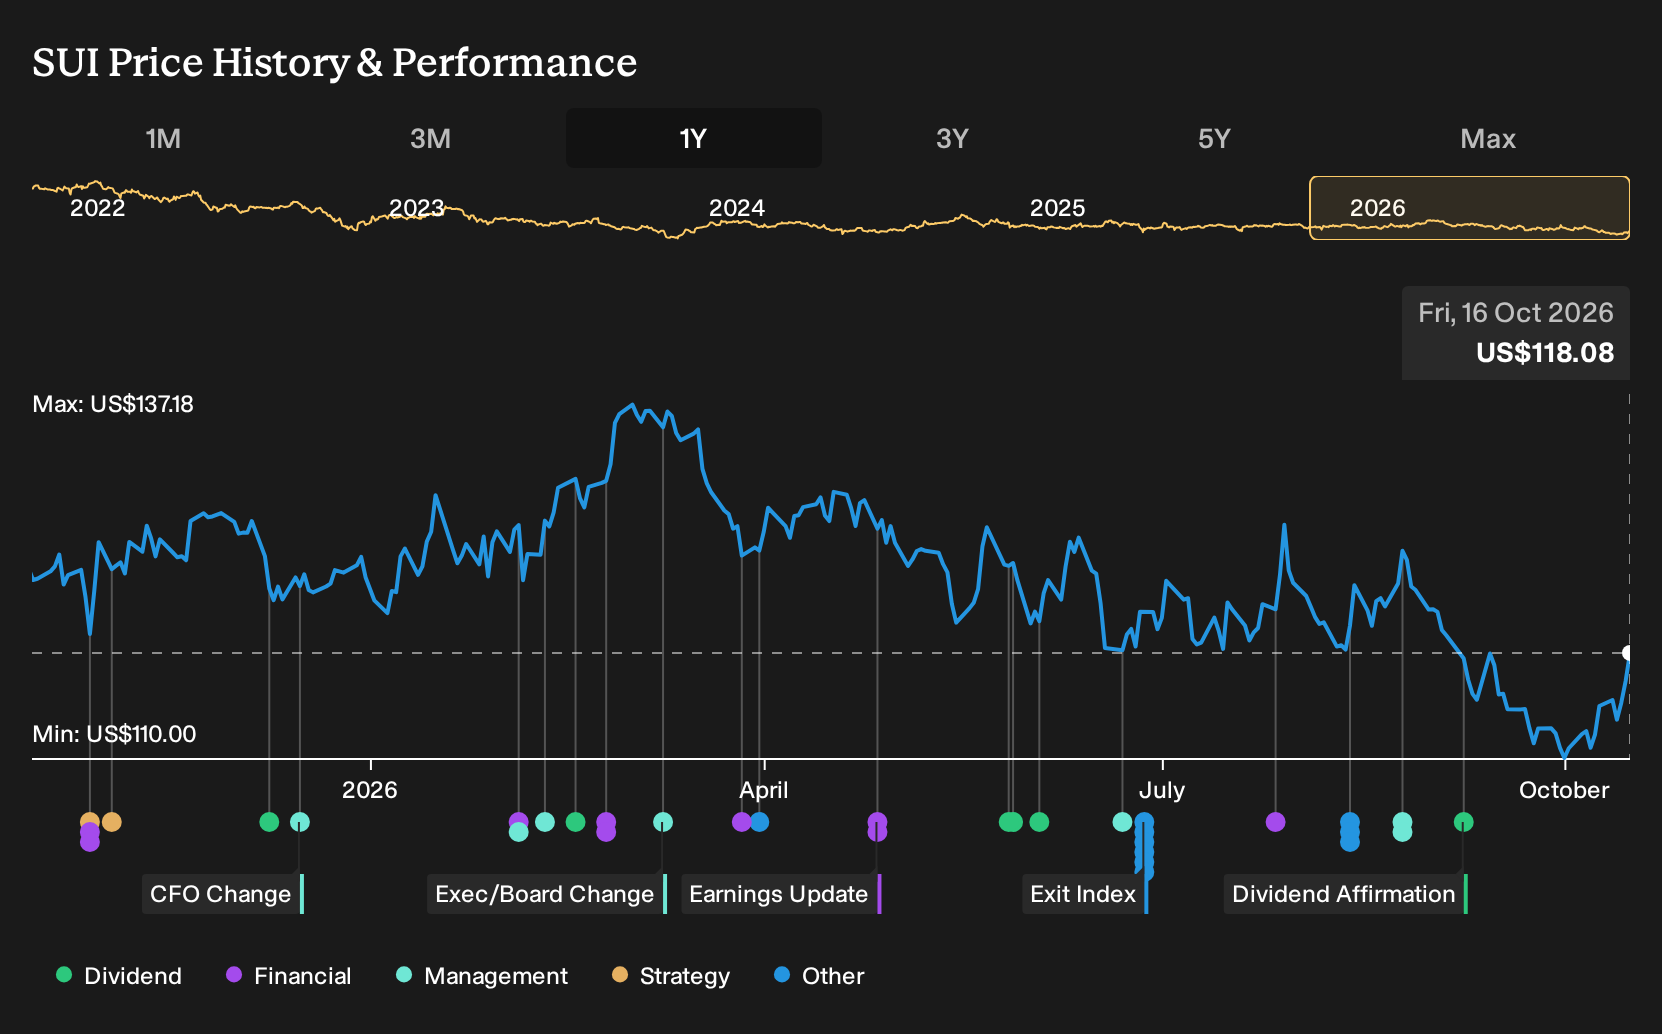
Uncover how Sun Communities' fair value indicates an 18% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
The Simply Wall St Community only provides two fair value views for Sun Communities, yet they already stretch from about US$139 to more than US$207. That gap shows how widely opinions can differ. When you compare those retail forecasts with RV mix risk and the pending Park Holidays sale, you see why exploring multiple angles really matters.
Explore another Sun Communities fair value estimate, including one that suggests as much as 75% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Sun Communities research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sun Communities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Sun Communities' overall financial health at a glance.
Looking for more investment ideas beyond Sun Communities?
If the Sun Communities story has you thinking about affordability, balance sheet strength, or different risk profiles, it can help to scan a wider field of opportunities using the Simply Wall St Screener.
- For investors hunting for companies that combine quality with room for a potential re-rating, start with a curated set of 20 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation and smoother sleep matter more than excitement, consider a 32 resilient stocks with low risk scores that filters for businesses with more resilient risk profiles.
- For those who care most about financial resilience and cleaner balance sheets, review a list of solid balance sheet and fundamentals (25 results) that highlights companies with stronger fundamentals supporting their capital structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com