


Engie (ENXTPA:ENGI), Why Is It Getting Fresh Attention Today?
Engie (ENXTPA:ENGI) has just expanded its low carbon story by pairing a planned biomethane facility in Le Havre with new battery storage projects stretching from Poland and Romania to Spain, Belgium, Portugal, the UK and the Netherlands.
Engie shares now trade at €23.42. The recent biomethane partnership with CMA CGM and the run of battery storage deals come as the 1-day share price return of 0.90% and 7-day share price return of 2.95% sit against a 90-day share price decline of 12.81%. The 1-year total shareholder return of 25.17% and 5-year total shareholder return of 184.96% point to momentum that has built over a longer horizon even as shorter term sentiment has cooled.
Scan a hand-picked set of European energy and infrastructure players that are pushing into storage and low carbon projects through our 41 power grid technology and infrastructure stocks
Short term sentiment on Engie has cooled even as its biomethane and storage build out gathers pace. Is the recent share price dip enough of an entry, or does patience still price that growth story more sensibly?
Most Popular Narrative: 23% Undervalued
Engie’s most followed narrative puts fair value at €30.54, which sits well above the recent €23.42 close and frames today’s weakness as a valuation gap built on grids, storage and long-term power contracts.
Expansion of regulated electricity networks, including the acquisition of UK Power Networks with a March 2025 regulated asset value of £9.2b and an expected 2026 EBIT contribution of €0.6 to 0.8b, is shifting Engie’s earnings mix toward more visible, inflation linked cash flows that can support net income.
See why 97 investors see Engie as 23% undervalued.
Result: Fair Value of €30.54 (UNDERVALUED)
Still, high economic net debt of about €60b and softer Renewables & Flex Power EBIT could both weaken the Engie narrative if these trends persist.
Find out about the key risks to this Engie narrative.
Another View On Engie’s Valuation
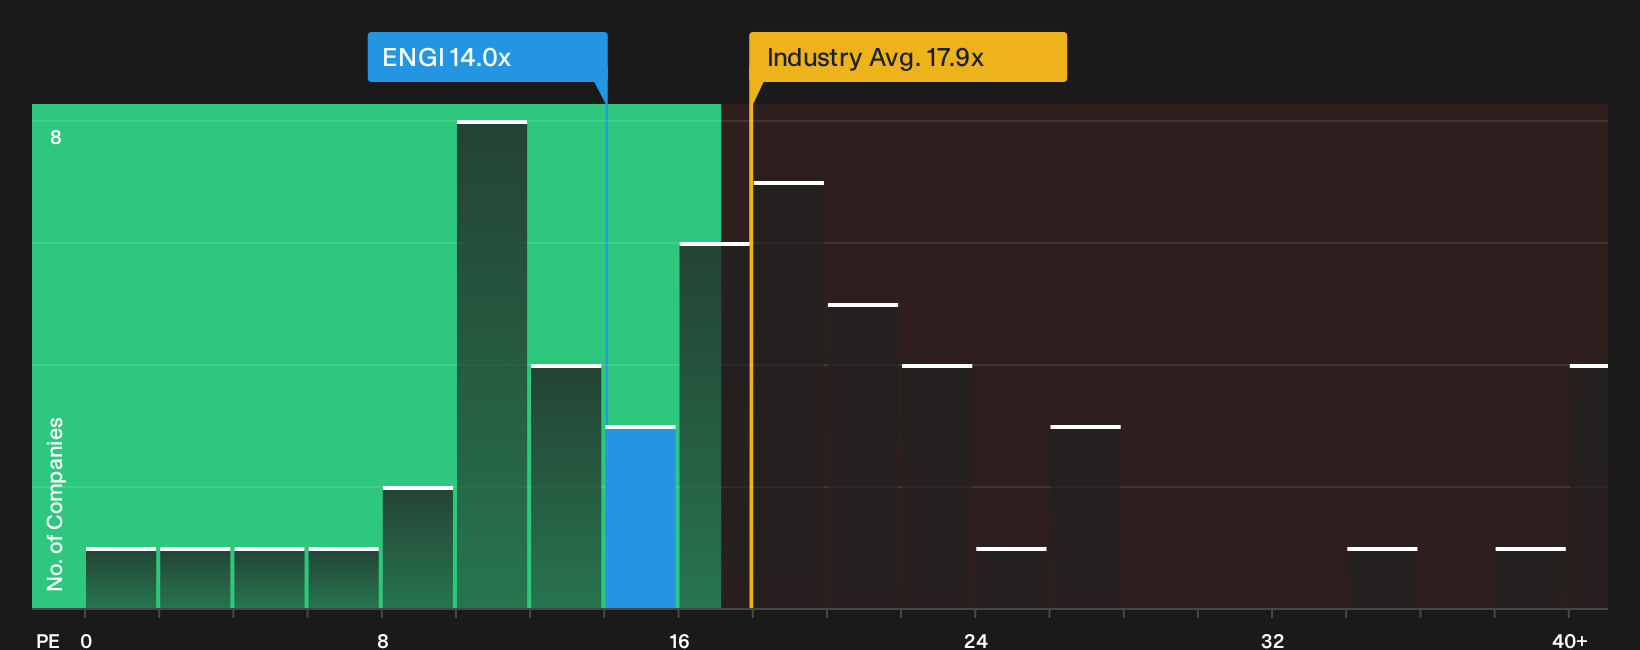
Analysts frame Engie as undervalued on a P/E of 14x versus a peer average of 18.9x and a fair ratio of 17.3x. That gap suggests the market is asking for a discount despite Engie’s 6.7% forecast revenue growth and 8.4% expected earnings growth. Is that caution justified, or is sentiment overshooting the debt and margin risks?
To stress test this against a different yardstick, focus on how the current P/E compares with that fair ratio and the wider Integrated Utilities group. Then decide whether the discount looks like a margin of safety or a warning sign in your own framework. See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Engie for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Engie today. For a sharper view, explore the full picture of both risks and rewards through the 4 key rewards and 2 important warning signs.
Looking for more Engie-like investment ideas?
If Engie has sharpened your focus on pricing, cash flows and risk, do not stop here. The next opportunity you research now could be the one you are most glad you did not ignore later.
- Target resilient balance sheets and dependable fundamentals by scanning the list of solid balance sheet and fundamentals (203 results).
- Hunt for mispriced quality where fundamentals and valuation line up using the 618 high quality undiscovered gems.
- Focus on steadier profiles and controlled downside by checking companies in the 233 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com