


Is It Smart To Buy Elecon Engineering Company Limited (NSE:ELECON) Before It Goes Ex-Dividend?
Elecon Engineering Company Limited (NSE:ELECON) stock is about to trade ex-dividend in three days. The ex-dividend date is two business days before a company's record date in most cases, which is the date on which the company determines which shareholders are entitled to receive a dividend. The ex-dividend date is important because any transaction on a stock needs to have been settled before the record date in order to be eligible for a dividend. Thus, you can purchase Elecon Engineering's shares before the 21st of October in order to receive the dividend, which the company will pay on the 13th of November.
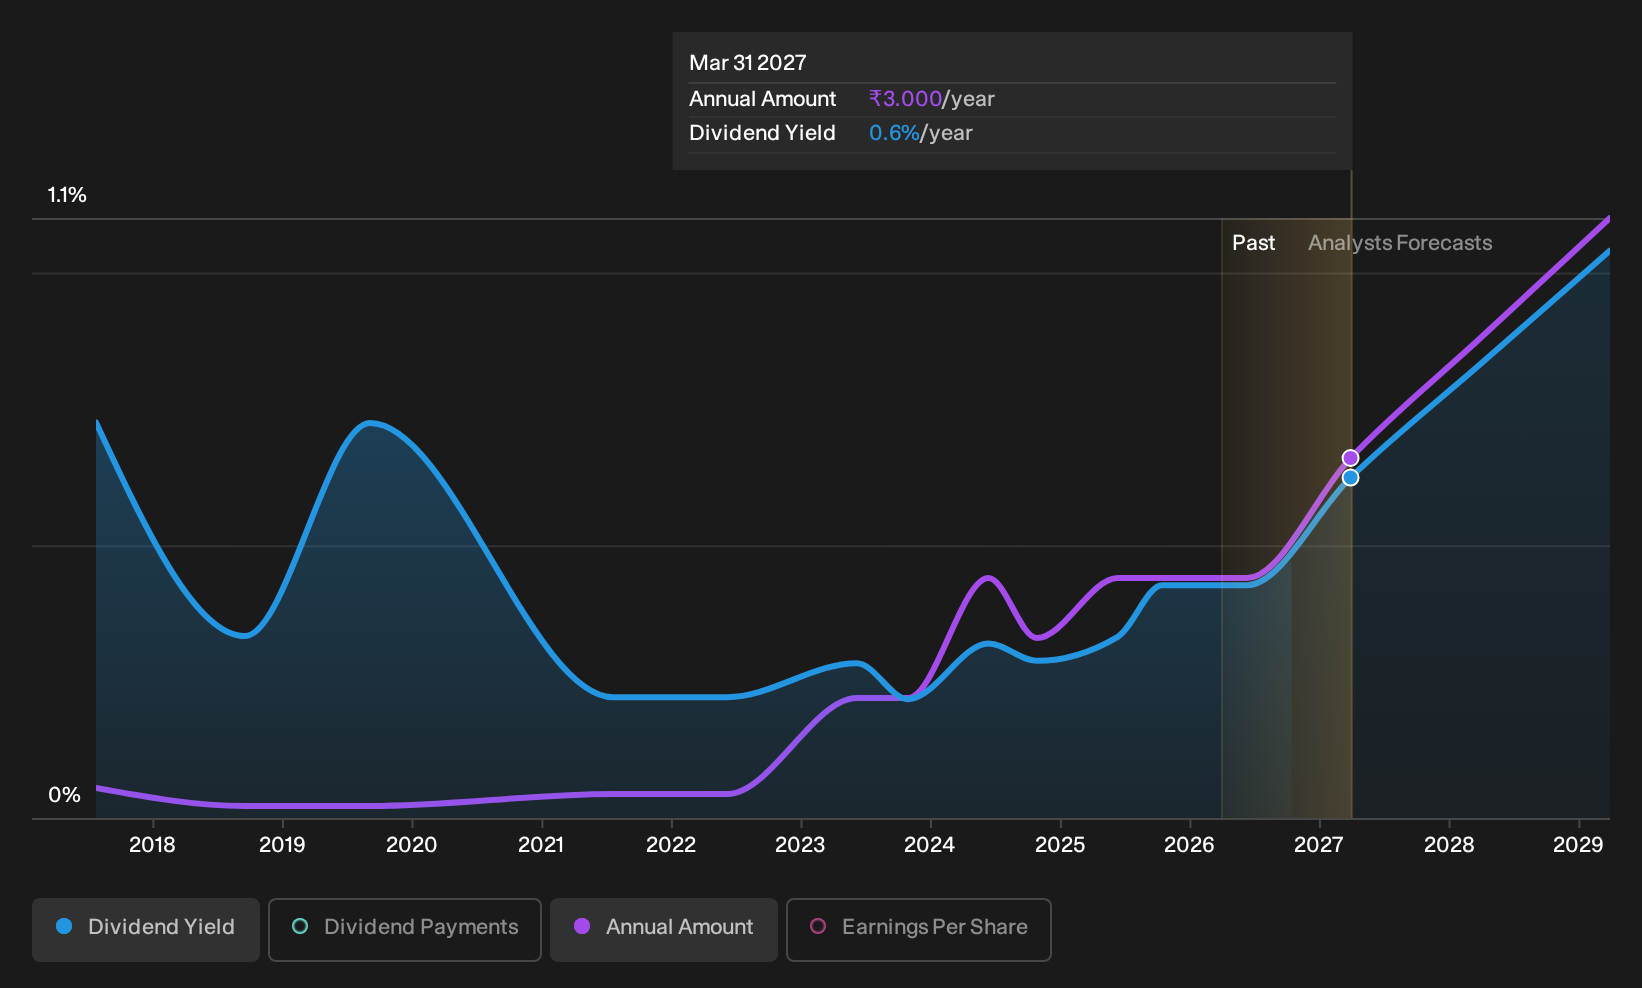
The company's next dividend payment will be ₹0.50 per share. Last year, in total, the company distributed ₹2.00 to shareholders. Last year's total dividend payments show that Elecon Engineering has a trailing yield of 0.4% on the current share price of ₹480.35. If you buy this business for its dividend, you should have an idea of whether Elecon Engineering's dividend is reliable and sustainable. As a result, readers should always check whether Elecon Engineering has been able to grow its dividends, or if the dividend might be cut.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. Elecon Engineering is paying out just 14% of its profit after tax, which is comfortably low and leaves plenty of breathing room in the case of adverse events. That said, even highly profitable companies sometimes might not generate enough cash to pay the dividend, which is why we should always check if the dividend is covered by cash flow. It paid out 18% of its free cash flow as dividends last year, which is conservatively low.
It's positive to see that Elecon Engineering's dividend is covered by both profits and cash flow, since this is generally a sign that the dividend is sustainable, and a lower payout ratio usually suggests a greater margin of safety before the dividend gets cut.
See our latest analysis for Elecon Engineering
Click here to see how much of its profit Elecon Engineering paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. Investors love dividends, so if earnings fall and the dividend is reduced, expect a stock to be sold off heavily at the same time. That's why it's comforting to see Elecon Engineering's earnings have been skyrocketing, up 34% per annum for the past five years. With earnings per share growing rapidly and the company sensibly reinvesting almost all of its profits within the business, Elecon Engineering looks like a promising growth company.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. In the last 10 years, Elecon Engineering has lifted its dividend by approximately 14% a year on average. Both per-share earnings and dividends have both been growing rapidly in recent times, which is great to see.
To Sum It Up
Has Elecon Engineering got what it takes to maintain its dividend payments? Elecon Engineering has grown its earnings per share while simultaneously reinvesting in the business. Unfortunately it's cut the dividend at least once in the past 10 years, but the conservative payout ratio makes the current dividend look sustainable. It's a promising combination that should mark this company worthy of closer attention.
On that note, you'll want to research what risks Elecon Engineering is facing. Every company has risks, and we've spotted 2 warning signs for Elecon Engineering you should know about.
If you're in the market for strong dividend payers, we recommend checking our selection of top dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.