


Rambus Stock In Focus After New AI Server Power Chip Launch
- Rambus has released a new power management IC for LPDDR6 SOCAMM2 server memory modules, now sampling to lead customers and aimed at future accelerated AI infrastructure that prioritizes power efficiency, compact form factors and precise module level control.
- This PMIC extends Rambus' LPDDR based server module roadmap and more tightly integrates its companion chips into AI focused data center architectures, where tokens per watt is a key design constraint.
- We will now look at how Rambus' LPDDR6 SOCAMM2 PMIC, aimed at AI servers, could influence the broader investment narrative.
Rambus Investment Narrative Recap
Rambus appeals to investors who believe AI and data center workloads will keep pulling in faster, denser memory and supporting chips, and that this specialist can convert that demand into durable cash generation. The key near term swing factor remains how efficiently Rambus ramps its companion chips while keeping gross margins from drifting further down from the low 60% range.
The biggest risk still sits with margin pressure, supply bottlenecks in OSAT and DRAM that Rambus expects through 2027, and any escalation of the antitrust investigation. The new LPDDR6 SOCAMM2 PMIC helps the product roadmap, but on its own it does not materially change those short term constraints.
The fresh LPDDR6 SOCAMM2 PMIC announcement ties directly into one of the key catalysts for Rambus, namely a larger role in AI focused server memory modules on top of its LPDDR5X SOCAMM2 chipset. That keeps the story centered on expanding the product mix beyond traditional DDR5 interface chips and into higher content, higher value companion silicon.
For you as a shareholder, the question is whether Rambus can execute on this broader chipset roadmap while managing legal and supply risks. Record revenue of US$207.4 million and guidance for further sequential gains suggest operational momentum, but tighter margins and capacity limits still shape how much of the AI build out actually shows up in earnings.
Rambus' current analyst narrative points to forecast revenue of US$1.2b and projected earnings of US$474.9 million by 2029, based on an assumed 17.4% yearly revenue growth rate and an earnings increase of about US$235.2 million from current earnings of US$239.7 million.
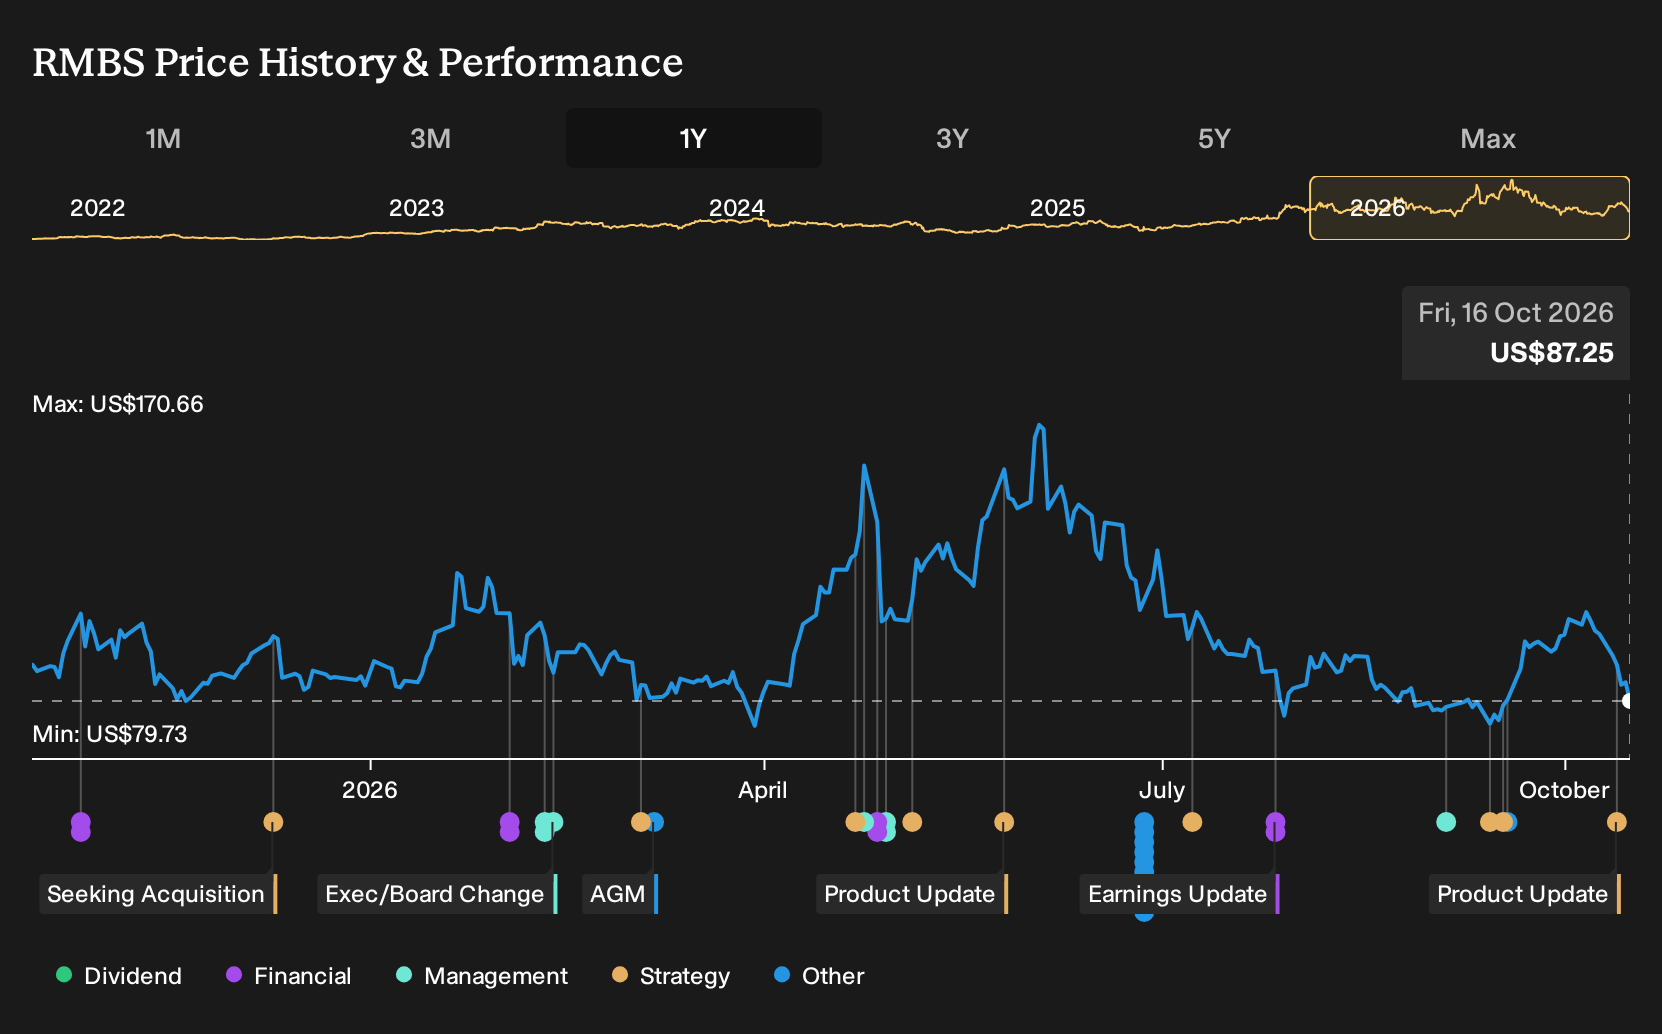
Uncover how Rambus' fair value indicates a 69% potential upside to its current price, a discount that could narrow quickly if sentiment changes.
Exploring Other Perspectives
One alternate view focuses on execution risk for Rambus around complex products like SOCAMM2 rather than on broad AI demand. The most cautious analysts were modeling revenue at about US$1.1b and earnings of US$391.9 million by 2029, well below consensus. That gap shows how sharply opinions can diverge. Consider exploring several viewpoints before deciding how this new PMIC might reshape the story.
Explore 2 other Rambus fair value estimates, including one that suggests as much as 63% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rambus research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rambus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rambus' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rambus?
If the Rambus story has sharpened your thinking around AI infrastructure and cash generation, it can be useful to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you scan a wide universe of stocks through that same fundamentals first lens.
- For investors hunting for smaller companies with stronger financial profiles, consider a curated 14 elite penny stocks with strong financials that have already cleared basic balance sheet and earnings quality checks.
- If value and quality matter most to you, focus on a 33 high quality undervalued stocks that pairs robust fundamentals with prices that sit below fair value estimates.
- For readers who care more about resilience than rapid gains, filter for a 32 resilient stocks with low risk scores that aims to prioritize steadier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com