


RealReal (REAL), What Is Behind The Fresh Attention On The Stock?
RealReal (REAL) just overhauled its borrowing by signing a new US$150 million senior secured term loan and a US$25 million revolving credit facility that replaces higher cost notes and pushes secured debt maturity out to 2033.
RealReal now trades at US$10.39, with a 7 day share price return of 6.56% and a 30 day share price gain of 9.83%. However, the share price is still down 34.24% year to date, while the 3 year total shareholder return is more than 7x. This suggests the recent refinancing news and the rollout of the Ask TRR AI shopping agent are being considered alongside an already volatile longer term record as sentiment rebuilds from earlier declines.
Scan how other AI driven retailers and resale platforms are pricing in balance sheet shifts by jumping into our curated list of 20 high quality undiscovered gems alongside RealReal's latest refinancing story.
RealReal now trades well below both analyst targets and some intrinsic value estimates, and the refinancing bounce has only closed part of that gap. Given this, where does a reasonable fair value anchor actually sit as you weigh the spread?
Most Popular Narrative: 40% Undervalued
Analysts following RealReal see a fair value of $17.25 against the latest $10.39 close. The refinancing news therefore sits inside a wider upside story that rests on steady revenue growth and margin repair over time.
Continuous investment in AI-driven automation (Athena and other initiatives) is delivering ongoing reductions in processing costs per unit and streamlining authentication, enabling scalable operational efficiencies that lower unit costs and support sustained margin expansion and improved EBITDA.
See why 7 investors see RealReal as 40% undervalued.
Result: Fair Value of $17.25 (UNDERVALUED)
Still, the RealReal story can break if revenue growth slows toward the lower end of management’s 8% to 12% range, or if commission rates keep slipping.
Find out about the key risks to this RealReal narrative.
Another View: RealReal Looks Expensive On Sales
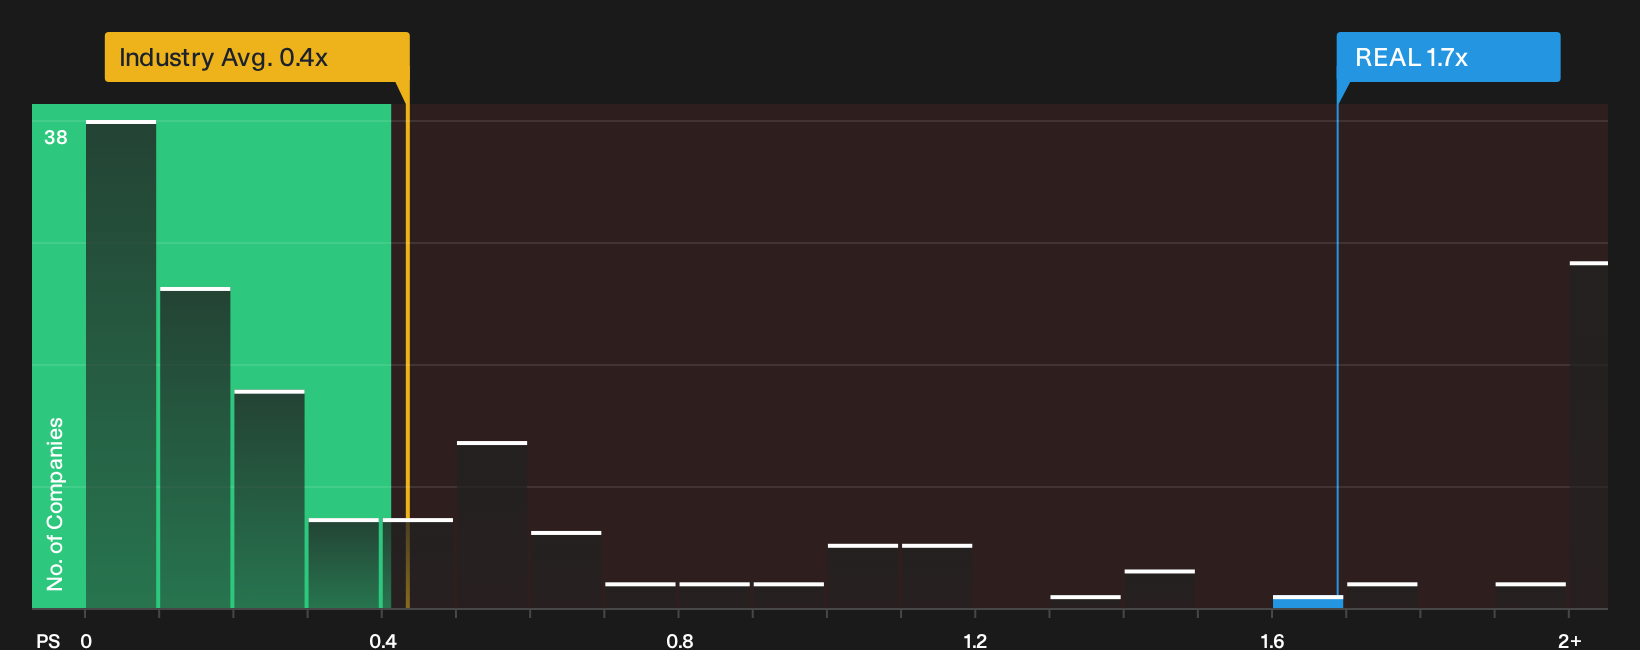
The analyst narrative pegs RealReal at a fair value of $17.25, yet the market is already assigning a rich sales tag. The stock trades on a P/S of 1.7x compared with a fair ratio of 1.4x and peers closer to 1.2x, while the wider US Specialty Retail group sits near 0.4x.
This gap means you are paying a premium sales multiple for a business that is still loss making, even as one model points to upside. The key question is whether that extra P/S markup still feels comfortable once you weigh execution risk and balance sheet pressure against the growth story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around RealReal’s refinancing and valuation only matter if you can weigh them yourself, so move quickly through the full breakdown of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond RealReal?
Do not stop your research with RealReal alone. The best opportunities rarely sit in one ticker, and the next idea often comes from a fresh angle.
- Target potential mispricings by scanning across 33 high quality undervalued stocks that pair solid fundamentals with price tags that may not fully reflect their financial profile.
- Anchor your watchlist in resilience by working through a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with stronger financial footing.
- Balance risk and reward by filtering for 32 resilient stocks with low risk scores that can help smooth out volatility across your broader portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com