


What Laureate Education Holders Bought Into
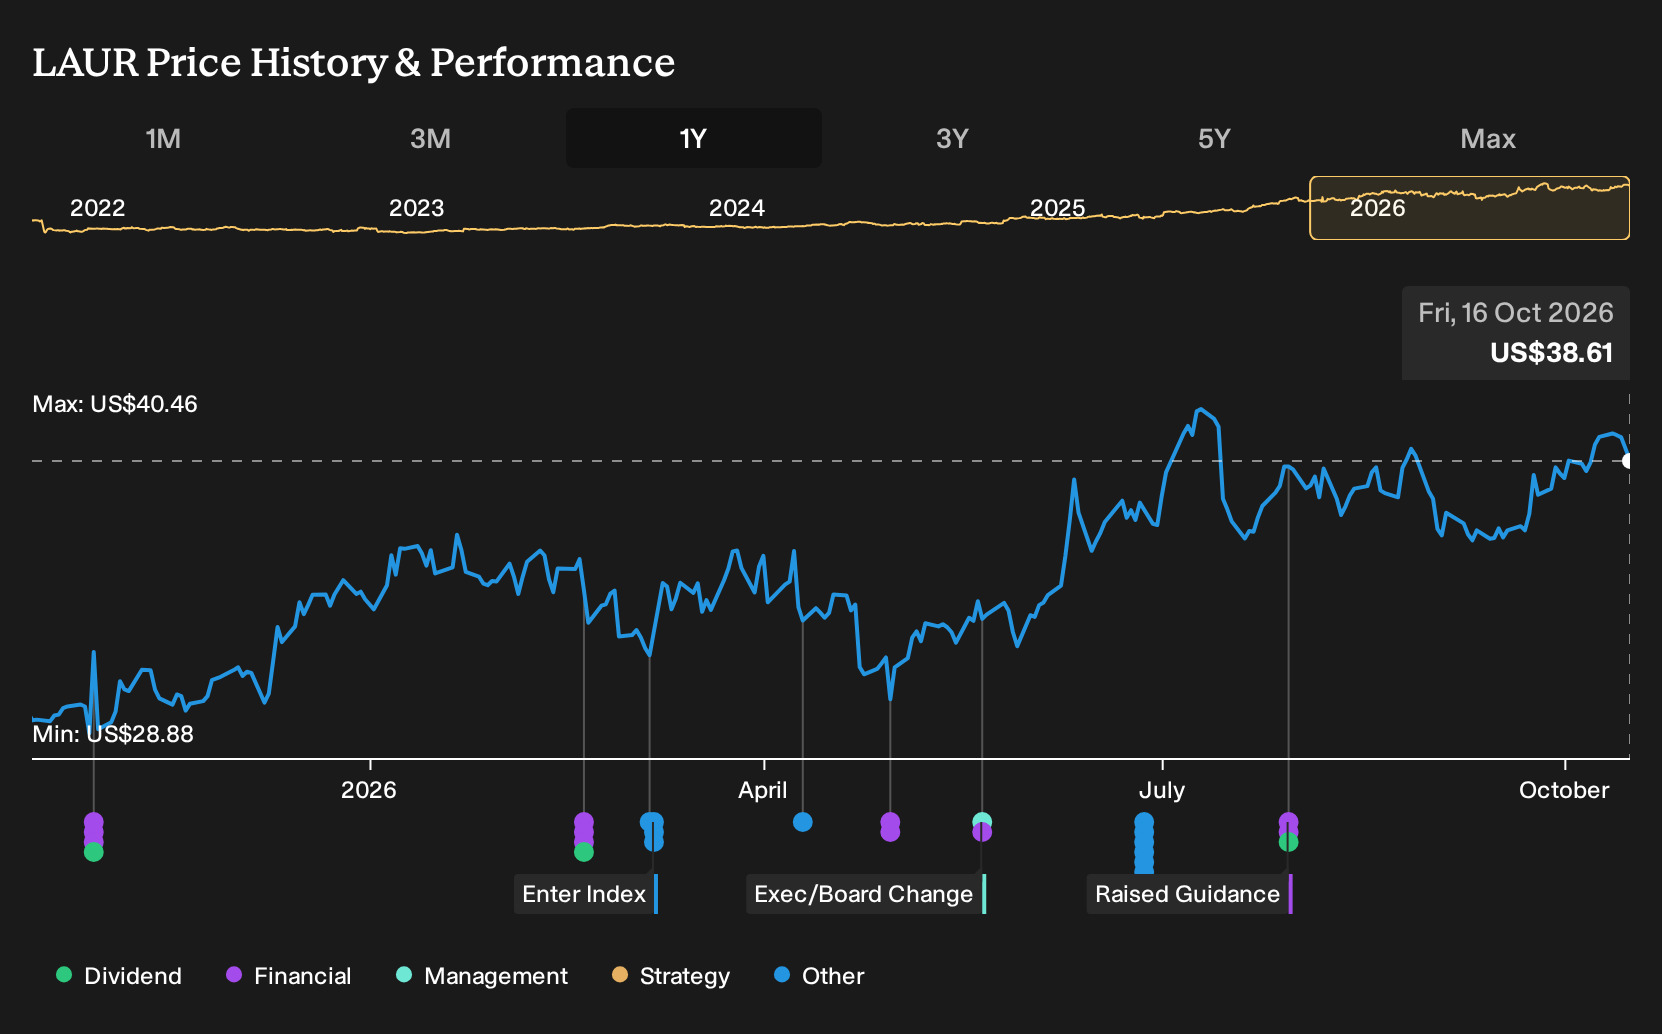
If Laureate Education was sitting on your watchlist instead of in your portfolio over the past year, the outcome may sting a little. Investors who held Laureate Education over the past year are up 31.5%, including dividends. That move sits against a backdrop of rising digital enrollments, fresh campuses in Mexico and Peru, and heavier share buybacks. The real question is whether earlier conviction in working adult upskilling could have helped you spot this before it played out.
If the move has made Laureate Education harder to judge, start where the gap is still open and scan 33 high quality undervalued stocks.
The Two Laureate Education Stories Investors Had To Weigh
The shares cost US$29.35 at the start of the period, and Laureate Education came with two very different stories attached to that price.
On the optimistic side, the bull camp saw a Fair Value of US$31, a notional target based on digital programs for working adults driving stronger enrollment and pricing across Latin America.
The cautious view put Fair Value at US$26, assuming shrinking youth demographics, heavier capital spending needs, and rising EdTech competition would restrain long term growth.
What The Results Changed For Laureate Education
Laureate Education’s Q2 2026 update showed revenue of US$615.9 million and net income of US$137.1 million, both higher than Q2 2025, with net margin rising from 18.1% to 22.3%. That combination of higher sales and a fatter margin leaned toward the optimistic case that digital programs, campus expansion, and buybacks could all support stronger economics.
The useful takeaway is simple. When a thesis hangs on operating leverage, do not just watch enrollment headlines. Track whether net margin, not just revenue, is moving in the direction the story promised.
What Today's Laureate Education Price Already Assumes
At US$38.61, Laureate Education now trades above where this Narrative places Fair Value, based on concerns around how efficiently earnings turn into cash and how fully new campuses and online programs are used.
A buyer today is effectively assuming solid execution on online scaling and campus utilisation. How does the risk of weaker free cash flow conversion test that belief?
"Adjusted EBITDA margins are guided to expand and conversion to unlevered free cash flow is guided at around 50%. Prior commentary on low free cash flow margins and projected only modest near term improvement suggests that any stumble in execution could expose structurally weaker cash generation, limiting room for buybacks and weighing on earnings per share."
One Narrative disagrees with today's price. → See where this Narrative says Laureate Education should trade
Looking Past Laureate’s Classrooms
Laureate Education highlights degrees and campuses, but your next step may differ.
Working adults in online programs still need places to stay during exams or residencies. Travelers on longer trips also look for flexible bookings that feel more like home.
Another platform concentrates on bundling those stays, experiences, and related services into a single marketplace.
It earns money by facilitating bookings instead of owning properties outright.
Its digital tools and rapid product testing support constant refinement, and as flexible stay habits evolve, that experimentation cycle may quietly shape what comes next.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 27% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com