


Meitu (SEHK:1357) Rolls Out Music Ads On A Fair Value Story That Still Divides Views
Meitu (SEHK:1357) is back in focus after its MVLAND unit rolled out Music Ads, a tool that turns basic product images and selling points into short, music-led video spots for social platforms.
At a share price of HK$3.58, Meitu has seen short term pressure, with the 7 day share price return down 5.17% and the 30 day share price return down 6.16%. The year to date share price return has fallen 51.82%, while the 5 year total shareholder return is 120.88%, which points to long term holders still being ahead even as recent momentum has faded.
Scan beyond Meitu and see how other AI driven content and advertising players are positioned with the hand picked 39 profitable AI stocks that aren't just burning cash list.
Meitu now trades at a steep discount to both analyst targets and one intrinsic value estimate, while the share price has slid hard this year. Is that gap compensating for risk, or reflecting problems the market sees first?
Most Popular Narrative: 54% Undervalued
Meitu's most followed narrative points to a fair value of HK$7.72 versus the last close of HK$3.58, putting a wide gap between the price and that assessment while recent returns have been weak.
Successful integration of advanced AI features (AI Wardrobe, AI Flash, and RoboNeo) has significantly improved user engagement and willingness to pay, demonstrated by a 45.2% year-on-year revenue growth in the core Photo, Video, and Design (PVD) segment and a rising subscription rate, pointing to higher future ARPU and improved gross margins.
See why 6 investors see Meitu as 54% undervalued.
Result: Fair Value of HK$7.72 (UNDERVALUED)
Still, rising competition in AI imaging and Meitu's reliance on third party models could undercut pricing power and squeeze the profit story that investors are betting on.
Find out about the key risks to this Meitu narrative.
Another View: What Meitu’s P/E Is Telling You
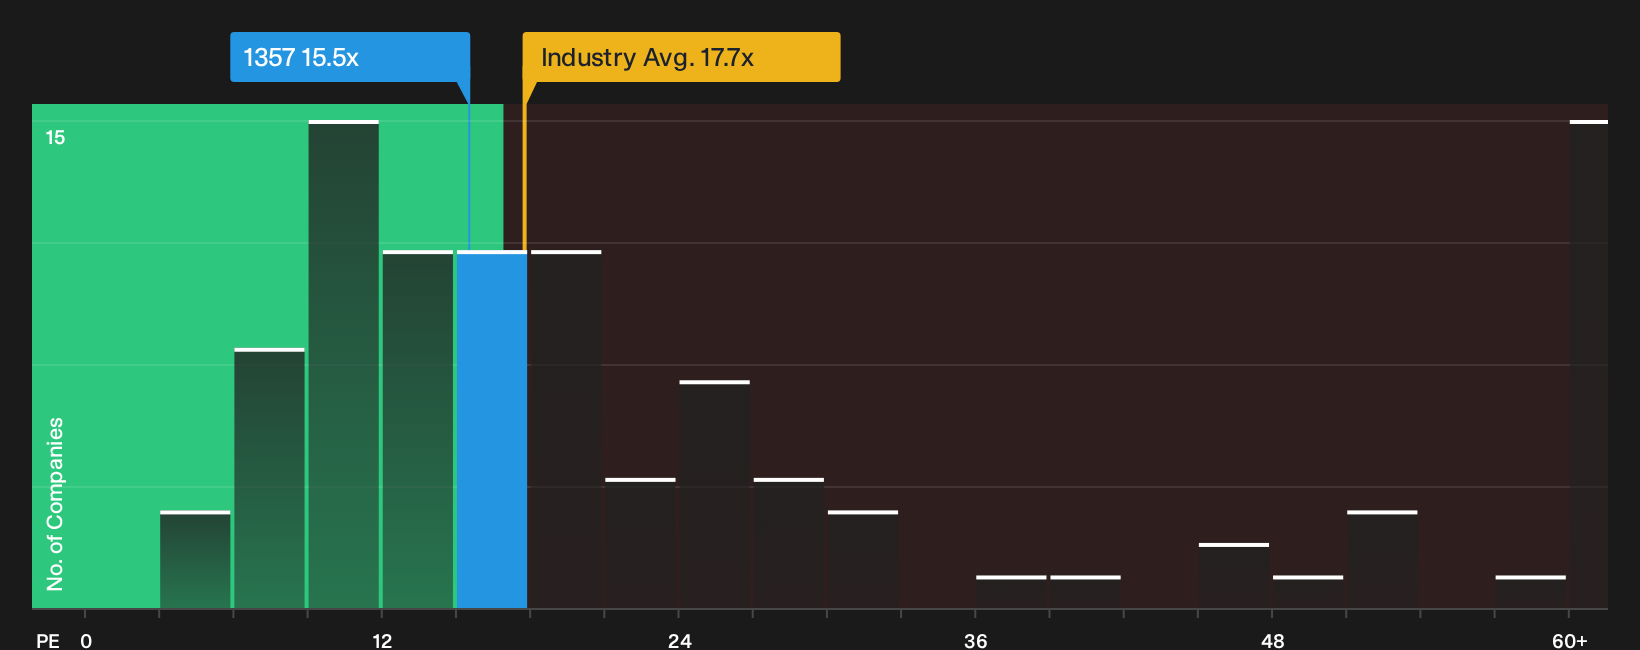
On a multiples check, Meitu trades on a P/E of 15.5x. That is above its own fair ratio of 14.7x and above peer companies on 11x, even though it is below the wider Asian Interactive Media and Services group on 17.7x.
A valuation built on earnings multiples therefore points to less of a clear bargain than the fair value narrative suggests and raises a simple question: is the current price already baking in much of the growth story investors are focused on, or does the higher P/E still leave room if forecasts play out?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Meitu's story today. Act quickly, stress test the bullish and cautious angles yourself, then weigh the 2 key rewards and 1 important warning sign.
Looking for more Meitu sized opportunities?
Do not stop with Meitu. Use fresh screeners to spot stocks that fit your style, because the best ideas rarely sit on the headline tickers.
- Target strong value by scanning companies that combine quality fundamentals with attractive pricing through the 191 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (203 results).
- Hunt for lesser known opportunities with robust metrics through the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com