


Sterling Infrastructure (STRL) Could Be 49% Undervalued After Its General Counsel Appointment
Sterling Infrastructure (STRL) has been back in focus after naming Katherine Hargis as Senior Vice President, General Counsel, Chief Compliance Officer, and Corporate Secretary. This governance shift is something investors may weigh alongside recent share volatility.
Recent trading has been rough for Sterling Infrastructure, with the share price down 4.92% in the last session and 17.29% over the past week, extending a 33.55% decline across three months. This follows a strong run that still leaves the year-to-date share price return at 32.95% and the three-year total shareholder return above 7x, which signals fading near-term momentum despite very strong long-term gains.
Spot 41 power grid technology and infrastructure stocks that, like Sterling Infrastructure, are tied to large scale projects where sentiment can swing quickly around earnings and governance news.For a stock that climbed hard over three years and then dropped more than 30% in ninety days, the obvious tension is simple. Is Sterling Infrastructure now pricing in fresh upside, or is the bulk of the story already in the rear-view mirror as the valuation case unfolds next?
Most Popular Narrative: 49% Undervalued
Sterling Infrastructure's most followed valuation storyline pegs fair value at $836.57, almost double the last close near $424. This puts the recent pullback in a very different light for anyone focused on long contracts and cash flows rather than the past quarter's price swings.
Sterling Infrastructure’s multi year pool of signed backlog and high probability future phase work now exceeds US$7b, heavily weighted to mission critical data center and semiconductor projects, which could continue to support revenue growth and earnings visibility if awards convert into execution as planned.
See why 101 investors see Sterling Infrastructure as 49% undervalued.
Result: Fair Value of $836.57 (UNDERVALUED)
Still, the bullish Sterling Infrastructure narrative leans heavily on adding scarce electrical labor and on large projects converting from awards into backlog without prolonged gaps.
Find out about the key risks to this Sterling Infrastructure narrative.
Another View: Multiples Paint A Hotter Picture For Sterling Infrastructure
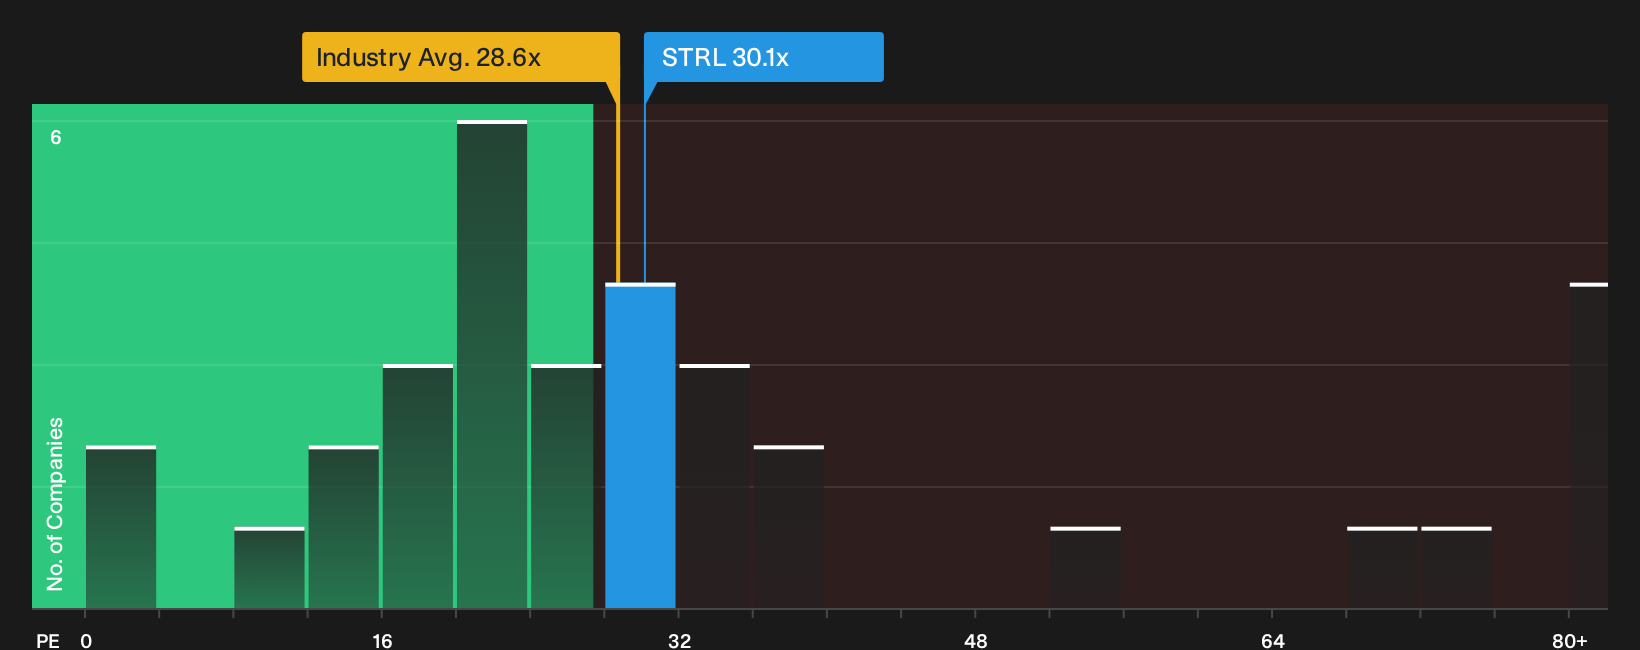
The fair value estimate of $836.57 suggests Sterling Infrastructure trades at a discount, yet the current P/E of 30.1x is higher than both its peer group on 24.5x and the wider US Construction industry on 28.6x, even though the fair ratio sits at a far richer 60.3x. Investors may need to consider whether this represents a margin-of-safety story, or a case of paying a premium with the expectation that the market moves closer to that fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Sterling Infrastructure leaves you unsure, that is the point. Move fast, review the numbers carefully, and evaluate the story in detail using the 4 key rewards and 1 important warning sign.
Ready for more investment ideas beyond Sterling Infrastructure?
If Sterling Infrastructure has your attention, do not stop here. Broaden your watchlist now and give yourself better odds of finding your next strong idea.
- Target dependable compounding by scanning for businesses with resilient earnings power and strong finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for underappreciated quality by reviewing the 20 high quality undiscovered gems before the wider market starts paying attention.
- Prioritise sleep-at-night investing by focusing on 32 resilient stocks with low risk scores that can help steady your portfolio when sentiment turns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com