


3 Indonesian Value Stocks Trading At Deep Discounts After The Market Selloff
Indonesia has been thrown into the spotlight after MSCI’s review put the market’s status in question, foreign funds have been pulling money, and the Jakarta benchmark is down roughly 39% this year. Forced selling risk, a weaker rupiah and low valuation filters now intersect. That mix can punish fragile businesses yet leave sturdier Indonesian value stocks trading at discounts. This article walks through three such ideas and discusses what the news shock might mean for each one.
The three Indonesian value stocks in this article are just a starting sample. The full screen surfaced 8 more companies with similarly priced metrics and detailed narratives that are not covered here.
If you want to identify potential bargains on your own terms, head straight to the Indonesian Value Stocks screener to filter candidates, analyze the data, and focus on the ideas that best fit your checklist.
Perusahaan Gas Negara (Persero) (IDX:PGAS)
Overview: Perusahaan Gas Negara (Persero) runs Indonesia’s main natural gas pipelines and LNG distribution network, serving industrial, commercial and household users.
Operations: Most revenue comes from Trading and Transmission at about US$3.7b, with US$281m from Exploration and Production and US$340m from Other Operations.
Market Cap: IDR28.8t
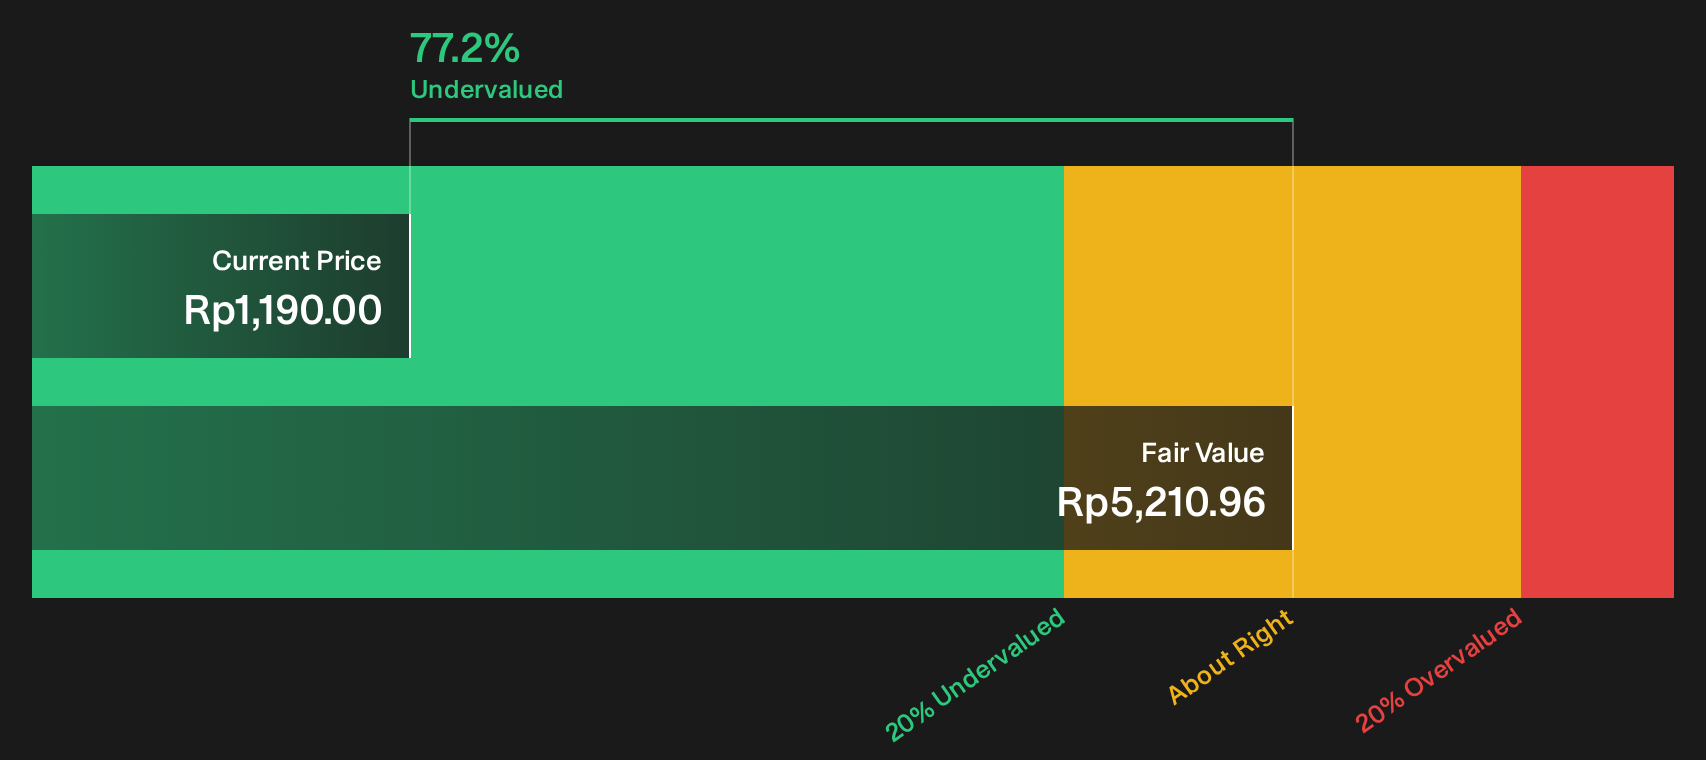
Perusahaan Gas Negara (Persero) fits the Indonesian Value Stocks screen as a large, cash-generative gas utility trading on a P/E of 6.6x versus peers near 18.4x. The share price has already fallen more than 10% over the past year, leaving a sizable estimated discount to intrinsic value. What happens when one unresolved pressure on this utility-like cash engine finally shifts will matter a lot for investors’ potential outcomes.
When that pressure finally moves, the DCF valuation analysis for Perusahaan Gas Negara (Persero) shows how current pricing could be masking where Perusahaan Gas Negara (Persero) might re rate if conditions change.
Indocement Tunggal Prakarsa (IDX:INTP)
Overview: Indocement Tunggal Prakarsa manufactures and sells cement, ready mix concrete, and aggregates in Indonesia and export markets.
Operations: Indocement Tunggal Prakarsa generates about IDR17.2t from Cement, IDR1.4t from Ready Mix Concrete, and IDR0.2t from Aggregates, mostly in Indonesia.
Market Cap: IDR16.9t
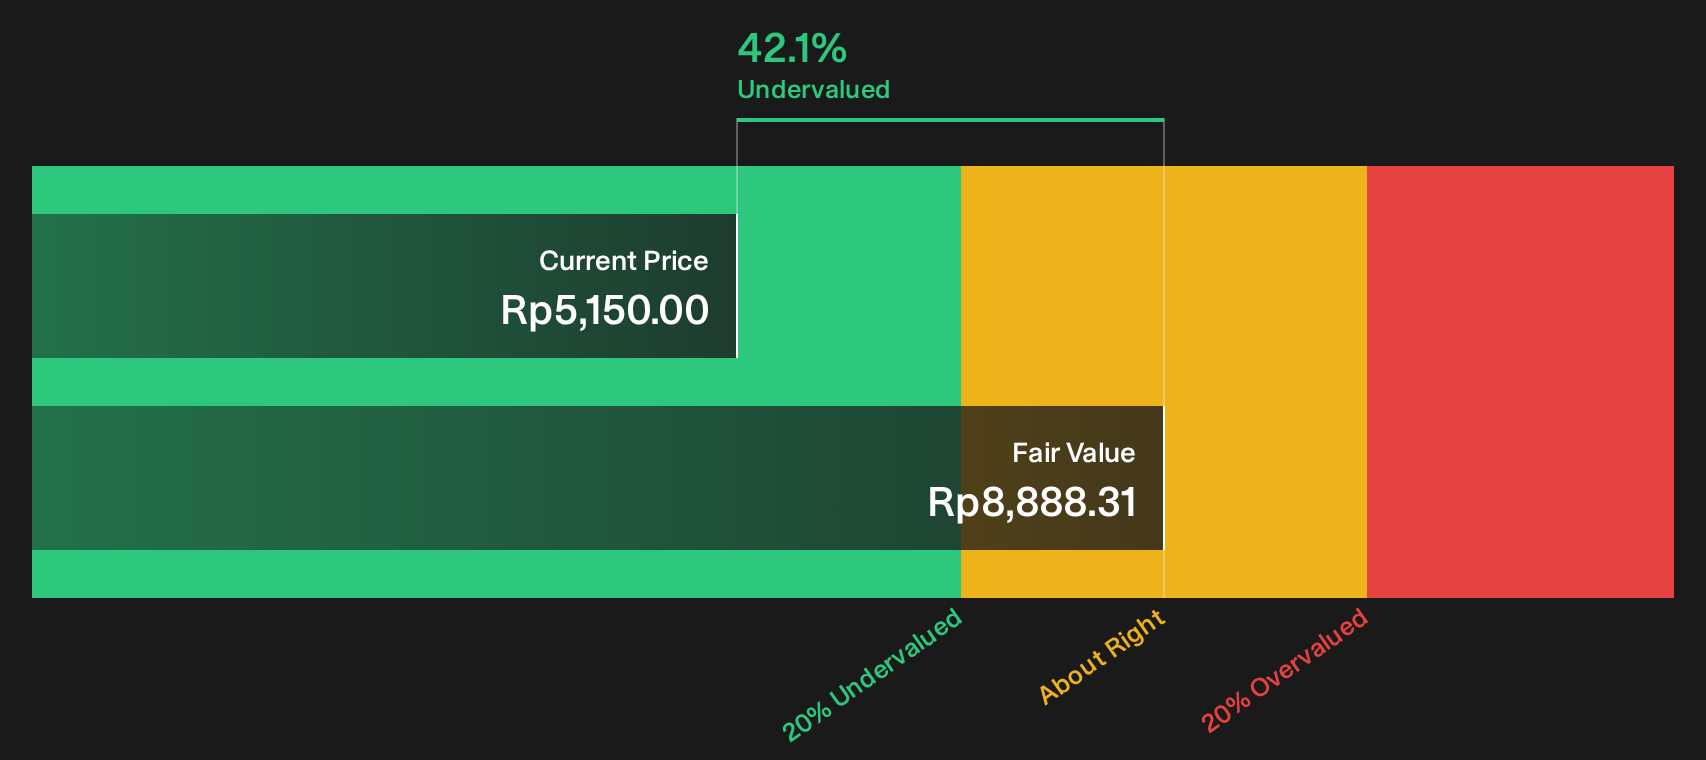
Indocement Tunggal Prakarsa fits the Indonesian Value Stocks screen as a large, cyclical cement producer trading on a P/E of 7.2x versus an industry closer to 14.1x, following a double digit share price decline and a screen estimated 42.1% discount to intrinsic value. Earnings resilience, improving 12.9% net margins and the potential impact of any easing in cement cycle pressure could be important factors for that gap.
That potential re rating gap is front and center in the analysis report for Indocement Tunggal Prakarsa so you can see what might be driving or stalling sentiment in Indocement Tunggal Prakarsa.
Sarana Menara Nusantara (IDX:TOWR)
Overview: Sarana Menara Nusantara owns and leases telecom towers and fiber networks across Indonesia, underpinning wireless connectivity and data services.
Operations: Sarana Menara Nusantara generates about IDR8.6b from Tower Rental and IDR5.6b from Other Services in Indonesia.
Market Cap: IDR22.5t
Within the Indonesian Value Stocks theme, Sarana Menara Nusantara links directly to core digital infrastructure, where long contracts and recurring lease income can cushion sentiment swings triggered by MSCI’s Indonesia review.
"The nationwide rollout of 5G technology over the coming decade, together with Indonesia's ongoing surge in mobile data consumption (driven by video streaming, social media, and IoT), is expected to drive a sustained need for expanded tower and fiber infrastructure, which could support long-term growth in SMN's tenancy ratios and lease revenue."
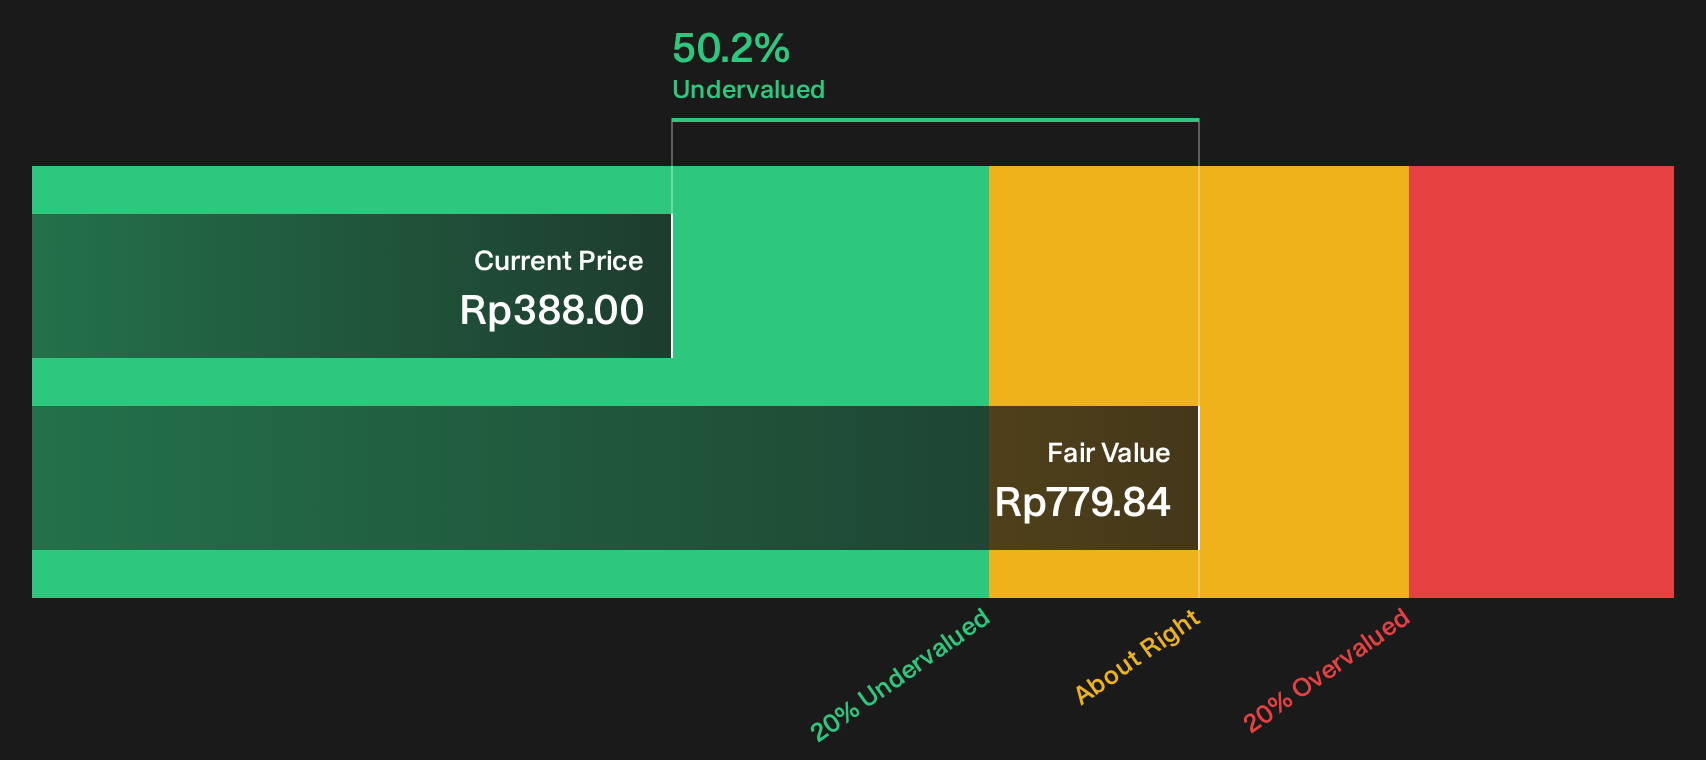
What happens when one financing and payout decision shifts against that backdrop could meaningfully change how investors value those recurring cash flows.
That hinge point is exactly what the full narrative for Sarana Menara Nusantara unpacks, showing how financing choices, tower rollout and pricing power could be masking where Sarana Menara Nusantara is really heading.
Curious To Explore Fresh Alternatives
Market shocks can send future breakout stories flying before they hit the headlines. Scan focused stock ideas while they are still under the radar for now and consider your options.
- Spot income workhorses early by reviewing a curated pool of companies in the 213 dividend fortresses before yields change with shifting demand.
- Track early AI momentum by scanning the 39 profitable AI stocks that aren't just burning cash while these operators still price like experiments instead of established cash generators.
- Hunt for resilient balance sheets by filtering the list of solid balance sheet and fundamentals (203 results) before renewed buying interest affects valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com