


CME Group (CME) Gains On Forecast Upgrades, Is The Stock Fairly Valued?
CME Group (CME) has landed on investor radars after analysts raised earnings forecasts while attention shifted to its plan to launch regulated Baseball futures tied to CMEFutureSports Performance Indexes later this month.
The recent Baseball futures announcement comes against a backdrop of firm price momentum for CME Group, with a 30-day share price return of 7.86% and a 90-day gain of 19.92% as investors react to both new products and upgraded earnings estimates. At the same time, total shareholder return of 13.94% over one year and 66.35% over five years, alongside a year-to-date share price return of 8.97%, indicates interest that has been building rather than fading.
Scan how CME Group fits alongside other exchanges and market infrastructure plays by reviewing the hand-picked 32 resilient stocks with low risk scores, which may appeal if you like resilient business models and measured volatility.
CME Group has already rewarded believers with a strong run, yet the Baseball futures launch and earnings momentum keep the story evolving. Has most of the upside already played out, or is valuation still leaving room?
Most Popular Narrative: 1% Overvalued
CME Group last closed at $293.87, slightly above the most followed fair value estimate of $292, which frames the Baseball futures story against a valuation that already bakes in a lot of good news.
The numbers and current valuation indicate that CME Group is fairly valued, with investors already accounting for strong margins, structural market data revenue, and potential benefits from new clearing and collateral efficiency initiatives.
See why 52 investors see CME Group as 1% overvalued.
Result: Fair Value of $292 (OVERVALUED)
Still, the CME Group story can change quickly if competition in key futures contracts reduces volumes, or if a shift in sentiment compresses the P/E multiple analysts rely on.
Find out about the key risks to this CME Group narrative.
Another View: CME Group Through The P/E Lens
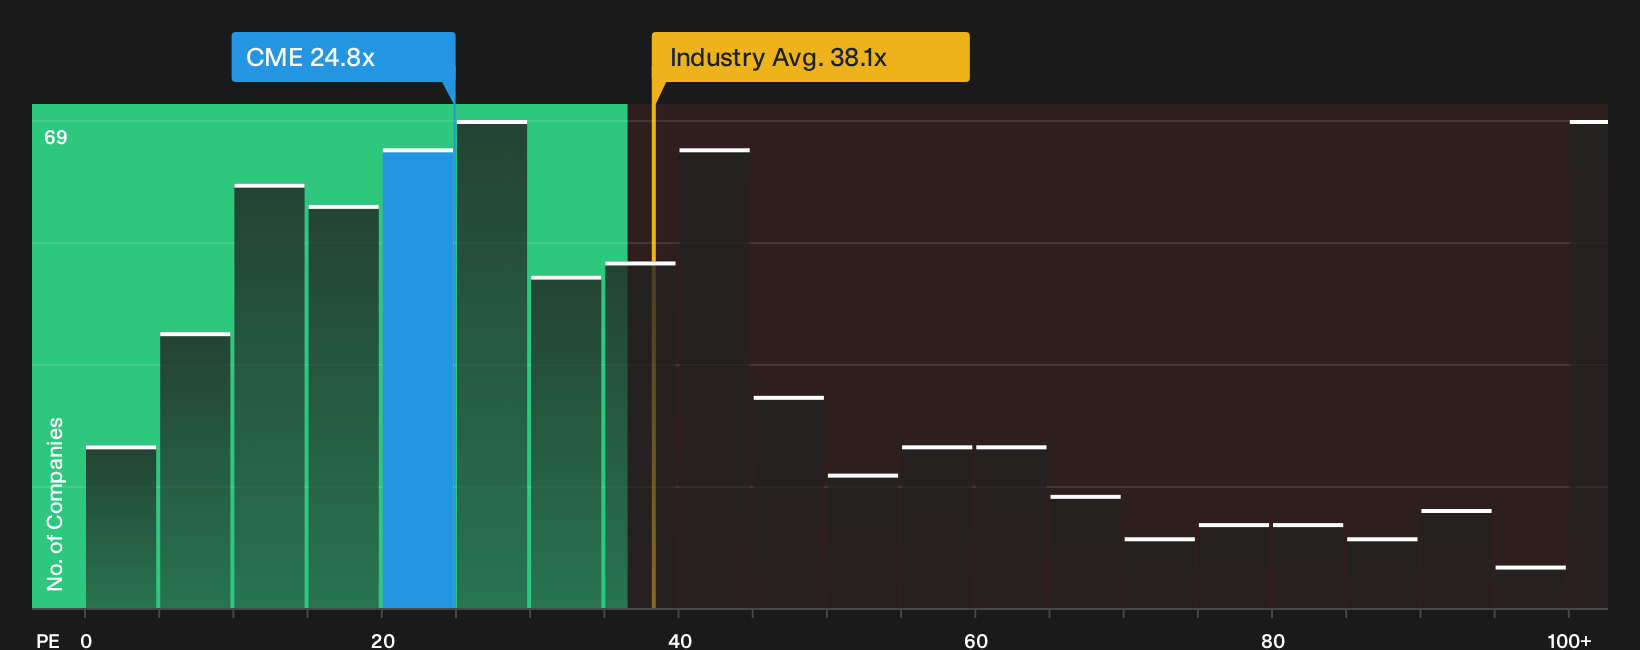
Look past the fair value of $292 for a moment and focus on the P/E. CME Group trades on 24.8x earnings, below the US Capital Markets average of 38.1x and under the peer average of 26.2x, yet well above its own fair ratio of 14.5x.
That mix indicates investors are paying a premium to what the fair ratio suggests the multiple could drift toward, even though the stock is cheaper than the broader industry and close to direct peers. Is that extra valuation gap a price you are comfortable paying for CME Group, or a risk you would rather avoid?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around CME Group feels familiar, treat it as a prompt to review the numbers yourself and move quickly while sentiment is still forming. To see how the positives stack up against the concerns, weigh up the 2 key rewards and 2 important warning signs.
Looking for more CME Group sized ideas?
If CME Group has you thinking more critically about value, take 25 focused seconds to hunt for other opportunities before this window of pricing missteps closes.
- Target quality at a discount by scanning the 33 high quality undervalued stocks that pairs strong fundamentals with prices the market has not fully reflected yet.
- Lock in potential income streams by reviewing the 8 dividend fortresses that focuses on high-yield payouts with solid underpinnings.
- Strengthen your watchlist by filtering through the 20 high quality undiscovered gems that screens for under-the-radar businesses with resilient metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com