


What Is Behind Tabcorp Holdings (ASX:TAH) Shares Climbing Today?
Recent commentary around Tabcorp Holdings (ASX:TAH) focuses on a tension between its stronger long-term track record and softer recent returns, raising fresh questions about earnings resilience and whether the current share price fairly reflects that risk.
At A$0.89, Tabcorp Holdings has seen a 1-day share price return of 3.49% and a 7-day gain of 2.89%. However, the 30-day share price return is down 3.26% and the year-to-date move is down 9.64%. The 5-year total shareholder return of 54.33% contrasts sharply with a 1-year total shareholder return decline of 13.02%. This indicates that long-term holders still sit on solid gains even as recent momentum has faded and markets reassess how much risk to price into the stock.
Balance your view on Tabcorp Holdings by scanning hand-picked alternatives with steadier recent performance using the 6 resilient stocks with low risk scores.
A business like Tabcorp Holdings can look solid on paper, yet still ask a hard question after the recent share price drop. Are you paying a fair price for that earnings power today?
Most Popular Narrative: 13% Undervalued
The most followed valuation view puts Tabcorp Holdings' fair value at A$1.03 per share, above the last close of A$0.89. This sets up a story that hinges on digital execution and regulatory reform.
Ongoing digital transformation initiatives including new customer offerings (e.g., in-play betting and omnichannel experiences) and tech upgrades to both digital and retail platforms position Tabcorp to capture higher online wagering volumes as mobile and digital betting become more mainstream, directly supporting future revenue growth and improved net margins. Progress toward implementing a national tote will expand liquidity, enable greater product innovation, and attract new customer segments, which is expected to unlock both revenue and cost synergies as scale benefits flow through.
See why 10 investors see Tabcorp Holdings as 13% undervalued.
Result: Fair Value of A$1.03 (UNDERVALUED)
Still, the whole story for Tabcorp Holdings can shift quickly if online giants keep squeezing digital share, or if key state based regulatory deals disappoint expectations.
Find out about the key risks to this Tabcorp Holdings narrative.
Another View: What The P/E Ratio Says About Tabcorp Holdings
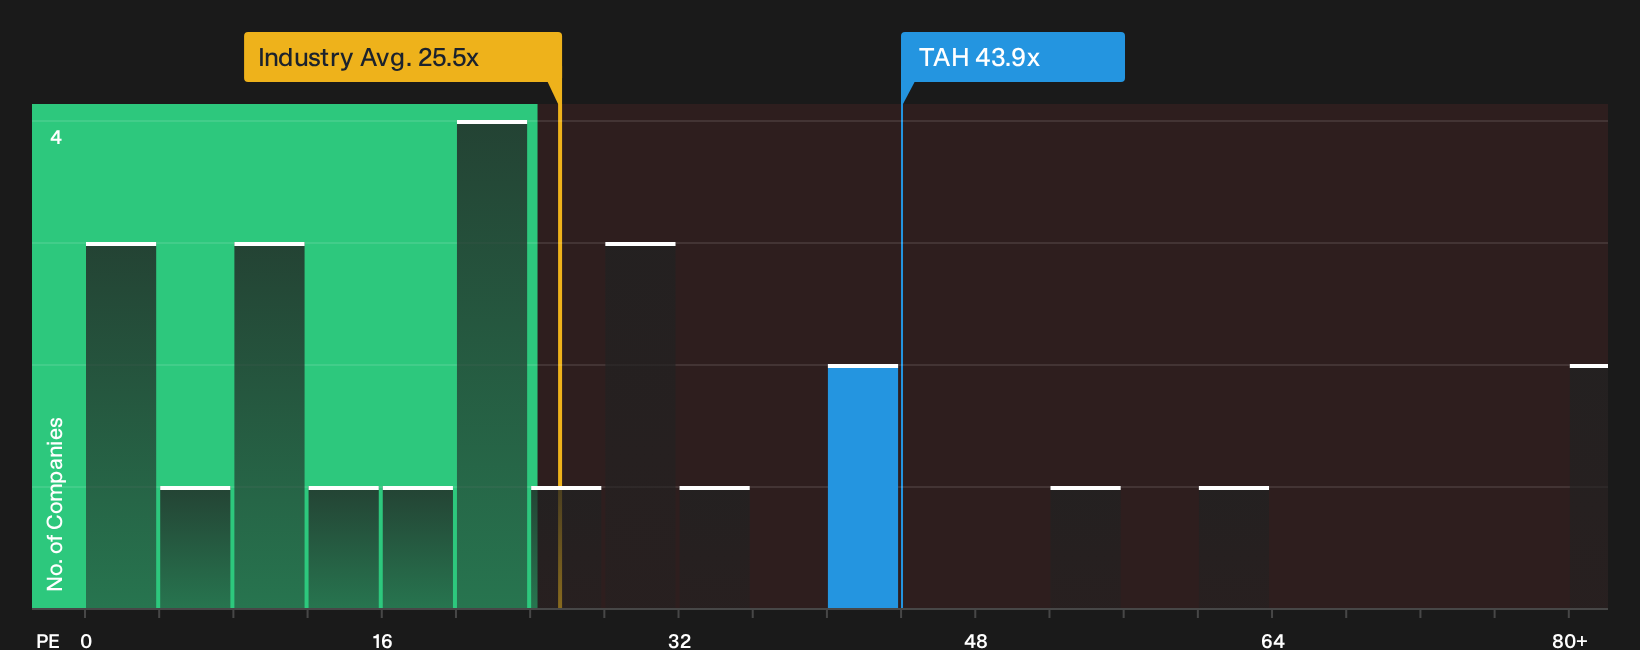
The story shifts once the focus moves from future cash flows to current market multiples. Tabcorp Holdings trades on a P/E of 43.9x, while the fair ratio is estimated at 24.9x and peers cluster closer to 25x. That gap points to real valuation risk if sentiment cools.
The question for you is simple. If the market edges back toward that fair ratio, are you comfortable with what that could mean for your potential upside and downside?
For a closer look at how this pricing gap could resolve, including where the ratios might settle, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Tabcorp Holdings can be confusing, so do not leave your view on autopilot when both risks and rewards are in play. To weigh those against each other and see what stands out, take a closer look at the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Tabcorp Holdings?
Do not stop your research with Tabcorp Holdings when there are other opportunities that might suit your goals and risk appetite more closely.
- Target stronger balance sheet resilience by scanning a list of solid balance sheet and fundamentals (12 results) that can help you stress test your portfolio against tougher conditions.
- Hunt for quality at a reasonable price by reviewing a 4 high quality undervalued stocks that could surface candidates the market may be overlooking.
- Build potential income streams by focusing on a 4 dividend fortresses that highlights higher yielding payers with more robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com