


Why European Rare Earth Stocks Deserve A Fresh Look After The China EU Trade Pause
China and the EU just stepped back from the brink on trade, and that pause in hostilities suddenly matters a lot for Europe’s rare-earth processing and magnet producers. Supply chains that once looked fragile now look more predictable, which can reshape how investors think about risk and pricing power across this niche corner of the market. This article walks through three European stocks closely exposed to that news and why their stories now deserve a fresh look.
The three stocks covered below are a sample pulled from a wider screen of European rare-earth processing and magnet producers, and that broader filter surfaced 10 more companies with equally interesting rare-earth narratives that are not included in this article. To see the full European Rare-Earth Processing and Magnet Producers list and start to identify and analyze your own highest-conviction ideas, head straight into the European Rare-Earth Processing and Magnet Producers screener.
Shenghe Resources Holding (SHSE:600392)
Shenghe Resources Holding is a rare-earth specialist that mines, processes, and refines concentrates, oxides, and metals used in permanent magnets and other advanced materials, linking Chinese supply to customers in green energy, aerospace, and defense. The business is sizeable, with a market value of about CN¥30.5b.
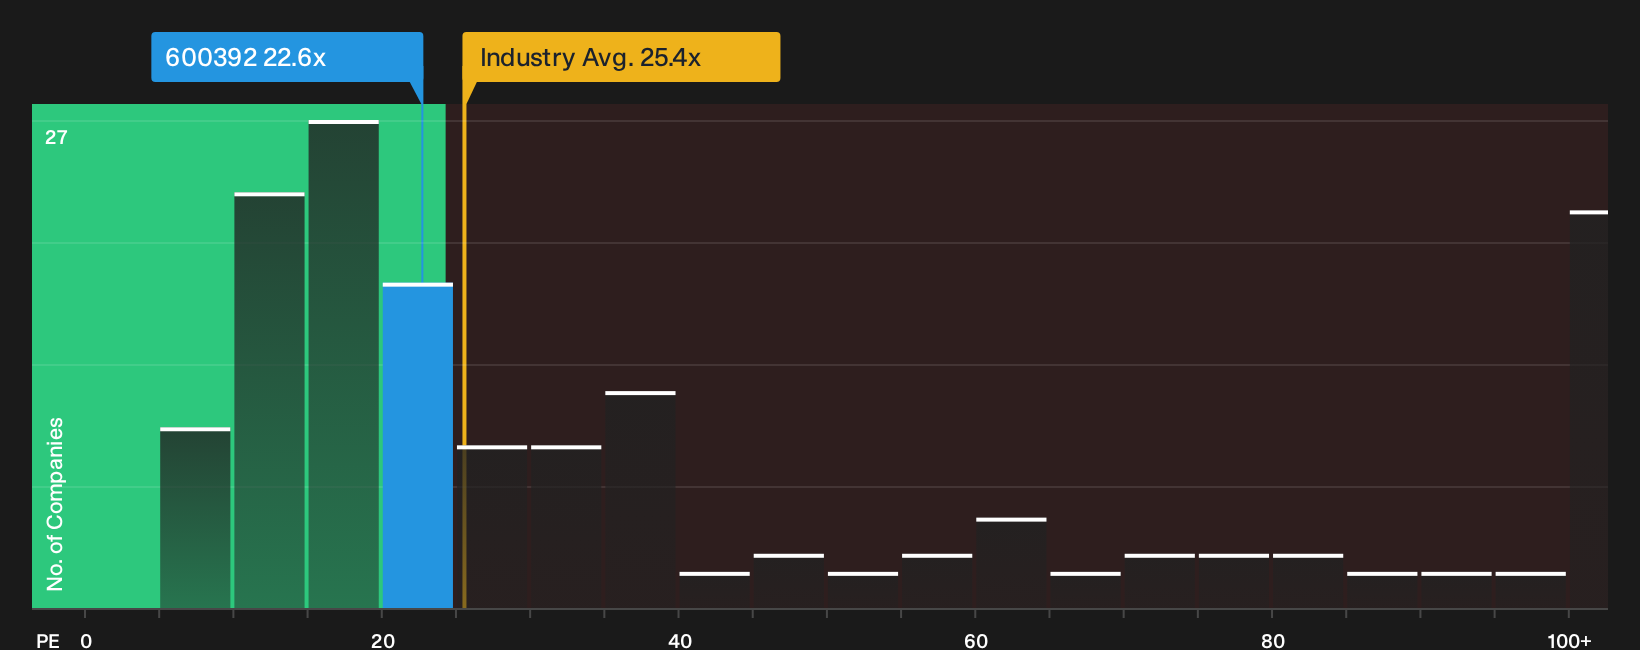
Shenghe Resources Holding sits close to the raw material tap for Europe’s rare-earth processing and magnet chains, selling the concentrates and oxides that European plants rely on for high-performance magnets in EVs, turbines, and defense hardware. Recent earnings growth of 106.7%, a P/E of 22.6x that is below both the wider Chinese market and metals peers, and improving net margins all anchor a rare mix of scale and profitability in a niche supply route that now benefits from a formal “green channel” for cross-border flows, although a single pressure point could still decide how much pricing power ultimately sticks.
That single pressure point is exactly why it pays to read the 4 key rewards and 1 important warning sign before the story around Shenghe Resources Holding shifts again.
Qingdao Yunlu Advanced Materials Technology (SHSE:688190)
Qingdao Yunlu Advanced Materials Technology is a CN¥7.5b advanced magnetic materials producer whose rare-earth friendly alloys and powders plug directly into the screener theme. All CN¥1.9b of its revenue comes from its Magnetic Material Industry segment across uses in EVs, power gear, data centers, and more.
Qingdao Yunlu Advanced Materials Technology provides focused exposure to high grade magnetic materials that can use rare-earth inputs for EVs, power equipment, and electronics. Future returns may depend on how competitive and industry pressures influence its ability to maintain pricing and margins.
That pricing power question is exactly why it helps to study the 2 key rewards and 1 important warning sign before sentiment on Qingdao Yunlu Advanced Materials Technology moves to the next phase.

Metso Oyj (HLSE:METSO)
Metso Oyj matters in this rare-earth processing theme because it sells the crushing, grinding, and refining kits that rare-earth refiners and magnet-material producers rely on to get ore into high value materials across global supply chains.
Metso Oyj is a €13.6b Finnish engineering group that earns about €4.1b from its Minerals segment and €1.3b from Aggregates, supplying processing equipment and services that rare-earth refiners and magnet-material producers can plug into their plants.
"Strategic acquisitions (for example, Swiss Tower Mills for energy efficient grinding, screening technologies in China, and recycling technology in Finland) strengthen Metso's portfolio in sustainable and eco-efficient processing technologies, aligning with stricter environmental regulations and the global decarbonization agenda, and positioning the company to compete for premium pricing and potential top-line revenue growth."
The key question is how one unresolved pressure on profitability shapes what Metso Oyj can actually keep from any rare-earth equipment upswing.
That profitability squeeze is exactly where the full narrative for Metso Oyj shows whether Metso Oyj’s equipment story is quietly decoupling from headline rare-earth sentiment.

Seeking Alternatives Before The Crowd
Fresh opportunities move fast, and the best breakout stories rarely stay under the radar for long. Before momentum gets fully caught by the crowd, scan these curated ideas and get in early.
- Spot early-stage momentum shifts in smaller companies that already show balance sheet strength and discipline by running the 129 elite penny stocks with strong financials while it still flies under the radar.
- Track where real earnings meet AI hype by filtering for the 38 profitable AI stocks that aren't just burning cash and see which businesses keep cash flow moving instead of dropping into constant refinancing.
- Anchor a more defensive income stream by reviewing the 212 dividend fortresses and focus on payout potential that may hold up before volatility really kicks in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com