


Should Strong Quarterly Earnings Require Action From Regions Financial (RF) Investors?
- Regions Financial reported third quarter 2026 net interest income of US$1,298 million and net income of US$631 million, with lower net loan charge offs of US$72 million and ongoing share repurchases and cash dividends on both common and preferred stock.
- The mix of higher earnings per share, reduced credit losses and active capital returns indicates a focus on earnings quality and disciplined balance sheet use at Regions Financial.
- We will now look at how this earnings strength and lower charge offs could influence Regions Financial's broader investment narrative.
Regions Financial Investment Narrative Recap
To own Regions Financial, you need to be comfortable with a regional bank that leans heavily on steady net interest income, disciplined credit and gradual fee buildout rather than rapid expansion. The latest quarter, with US$1,298 million of net interest income, US$631 million of net income and lower net charge offs of US$72 million, supports that slow and steady profile.
The key near term swing factor is whether Regions Financial can keep revenue and fees from stalling while holding the line on expenses. Lower credit costs help, but any repeat of flat total revenue or weaker efficiency could pressure earnings quality. By contrast, consistent execution on technology, deposit growth and core lending would support the existing narrative without a major reset.
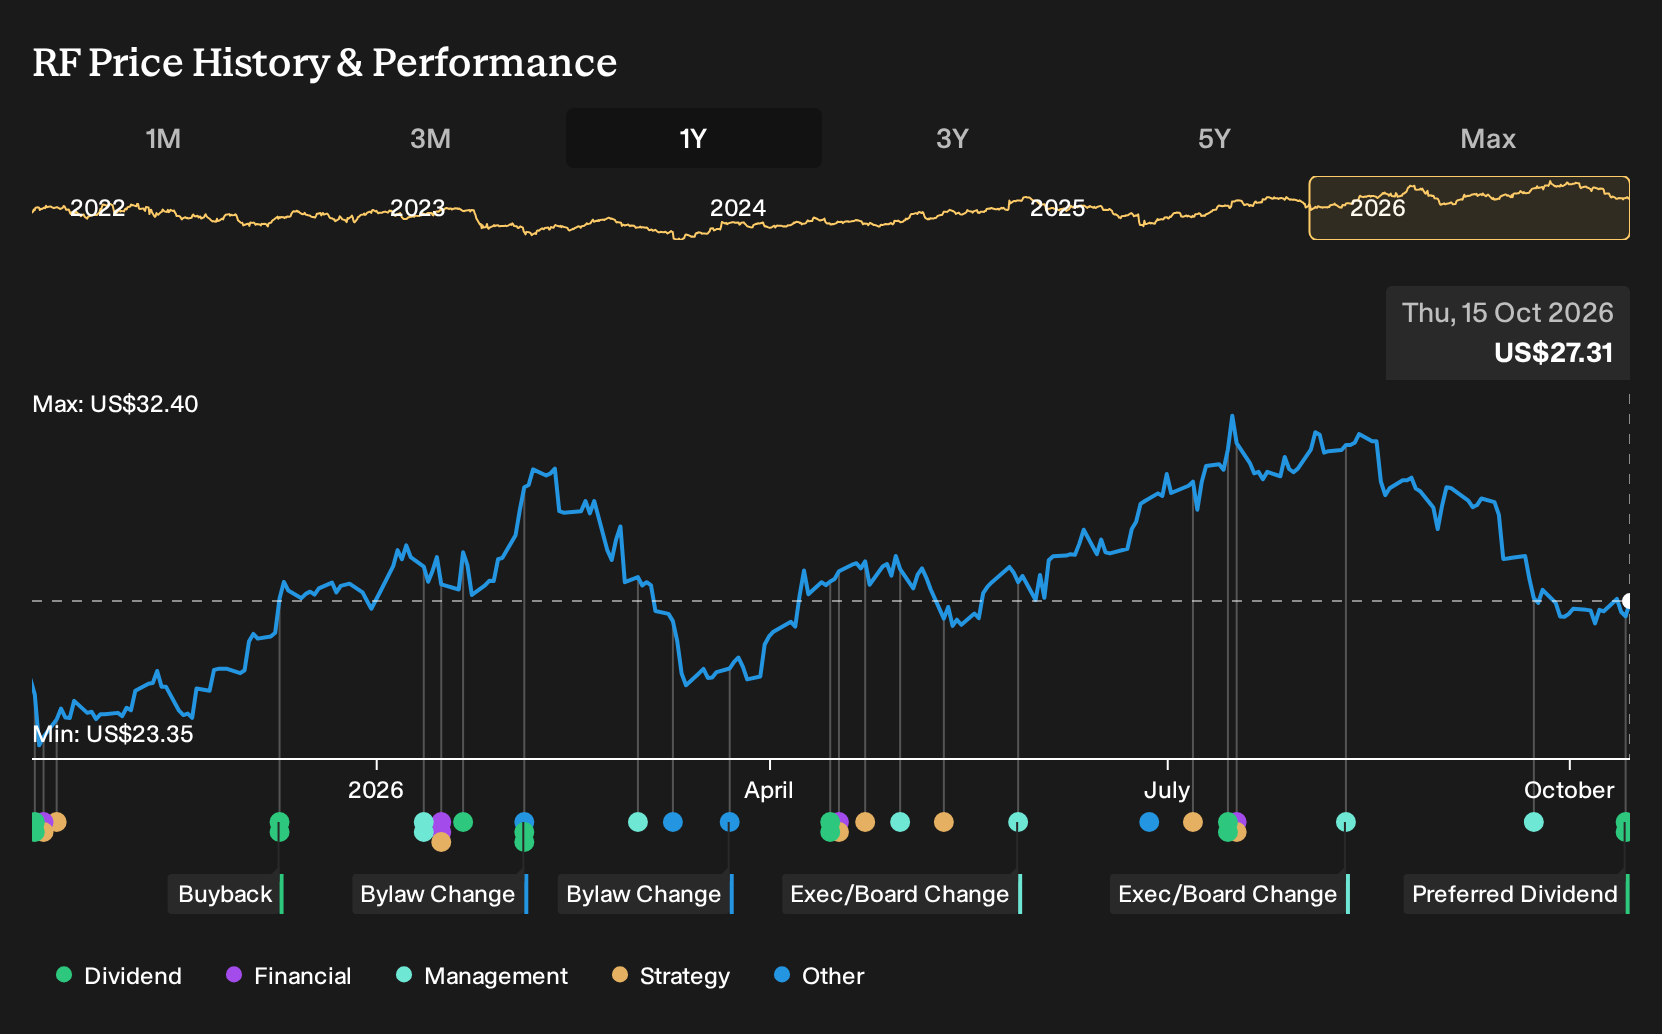
The most relevant recent update for this story is the common dividend affirmation, with a US$0.30 per share payout declared for January 4, 2027. That decision, alongside cash dividends on several preferred series, points to a board that sees current earnings and capital levels as sufficient to sustain regular cash returns.
For you as an investor, that dividend call links directly to the main catalysts and risks. Consistent payouts sit on top of net interest income, fee generation and credit discipline. Any pressure on revenue growth, operating efficiency or loan quality would feed quickly into the capacity to keep funding both dividends and buybacks at current levels, so those operating metrics remain the ones to watch most closely.
Regions Financial's current earnings are about US$2.1b, and analysts expect earnings to reach US$2.4b by 2029. This represents a US$0.3b increase, based on projected yearly revenue growth of 7.1% that would take revenue to US$8.9b in 2029.
Uncover why Regions Financial's fair value indicates a 17% potential upside to its current price before the discount to Regions Financial's earnings story narrows.
Exploring Other Perspectives
The Simply Wall St Community offers just 2 fair value views on Regions Financial, yet they span a wide band from about US$32 to nearly US$60 per share. That gap shows how far opinions can stretch. When you set those against risks around flat revenue and efficiency, plus Sun Belt and digital banking catalysts, you get a broad field of possible outcomes that you should explore through multiple viewpoints.
Explore another Regions Financial fair value estimate, including one that suggests as much as 119% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so you may want to trust your own analysis.
- A great starting point for your Regions Financial research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Regions Financial. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Regions Financial's overall financial health at a glance.
Looking For More Ideas Beyond Regions Financial?
If the Regions Financial story has you thinking about where earnings resilience, balance sheet strength and shareholder returns intersect, the next step is to widen your search. The Simply Wall St Screener lets you line up other companies with similar traits so you can compare quality, risk and income potential side by side instead of looking at this bank in isolation.
- For investors who want income plus staying power, start with a shortlist of steady payers by reviewing 8 dividend fortresses that may offer more durable cash returns.
- If capital preservation is your priority, narrow your universe to resilient operators by checking out 32 resilient stocks with low risk scores that may better match a cautious approach.
- When you want both solid finances and room for the story to grow, consider broadening your watchlist through 20 high quality undiscovered gems that pair strong fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com