


How First Human Trial Data Could Change The Case For Zai Lab Stock
- Zai Lab announced that first clinical trial data for ZL-1503, its internally developed IL-13/IL-31Ra bispecific antibody for moderate-to-severe atopic dermatitis, will be presented at the ACAAI 2026 meeting in Phoenix with initial pharmacokinetic, biomarker, safety, and immunogenicity readouts.
- The disclosure of first-in-human data for a potentially first-in-class, long-acting biologic could influence how investors view Zai Lab’s internal R&D engine compared with its historical reliance on in-licensed assets.
- We will look at how Zai Lab’s investment narrative shifts as first-in-human ZL-1503 data approach, particularly around internal pipeline productivity.
Zai Lab Investment Narrative Recap
To own Zai Lab, you need to believe the business can turn a heavily partnered model into a more balanced mix that includes meaningful internal R&D, while still scaling its marketed portfolio in China. The ZL-1503 update speaks directly to that first piece. It brings the internal pipeline into sharper focus but does not change the near term commercial drivers already in place.
The key near term swing factor remains whether high R&D and SG&A spending can be kept in check while revenue, currently US$449.6m, continues to expand. The biggest risk stays intact. Zai Lab is still loss making, with a net loss of US$188.2m and no profitability expected in the next three years.
The ACAAI 2026 presentation of first in human data for ZL-1503 is the clearest recent operational marker for Zai Lab right now. It gives you a concrete date, November 12 to 16, for fresh information on pharmacokinetics, biomarkers, safety and immunogenicity that can inform how credible management’s internal R&D ambitions look.
This matters because current consensus expectations already assume revenue growth of about 23% a year, supported by partnered products and potential future launches. ZL-1503 does not replace those commercial catalysts. It adds another potential source of value while also increasing the importance of disciplined trial execution, capital allocation and risk management around an unprofitable base business.
Zai Lab's outlook projects US$832.0 million in revenue and US$157.9 million in earnings by 2029. This scenario assumes 22.4% yearly revenue growth and an earnings increase of about US$336.0 million from a current loss of US$178.1 million.
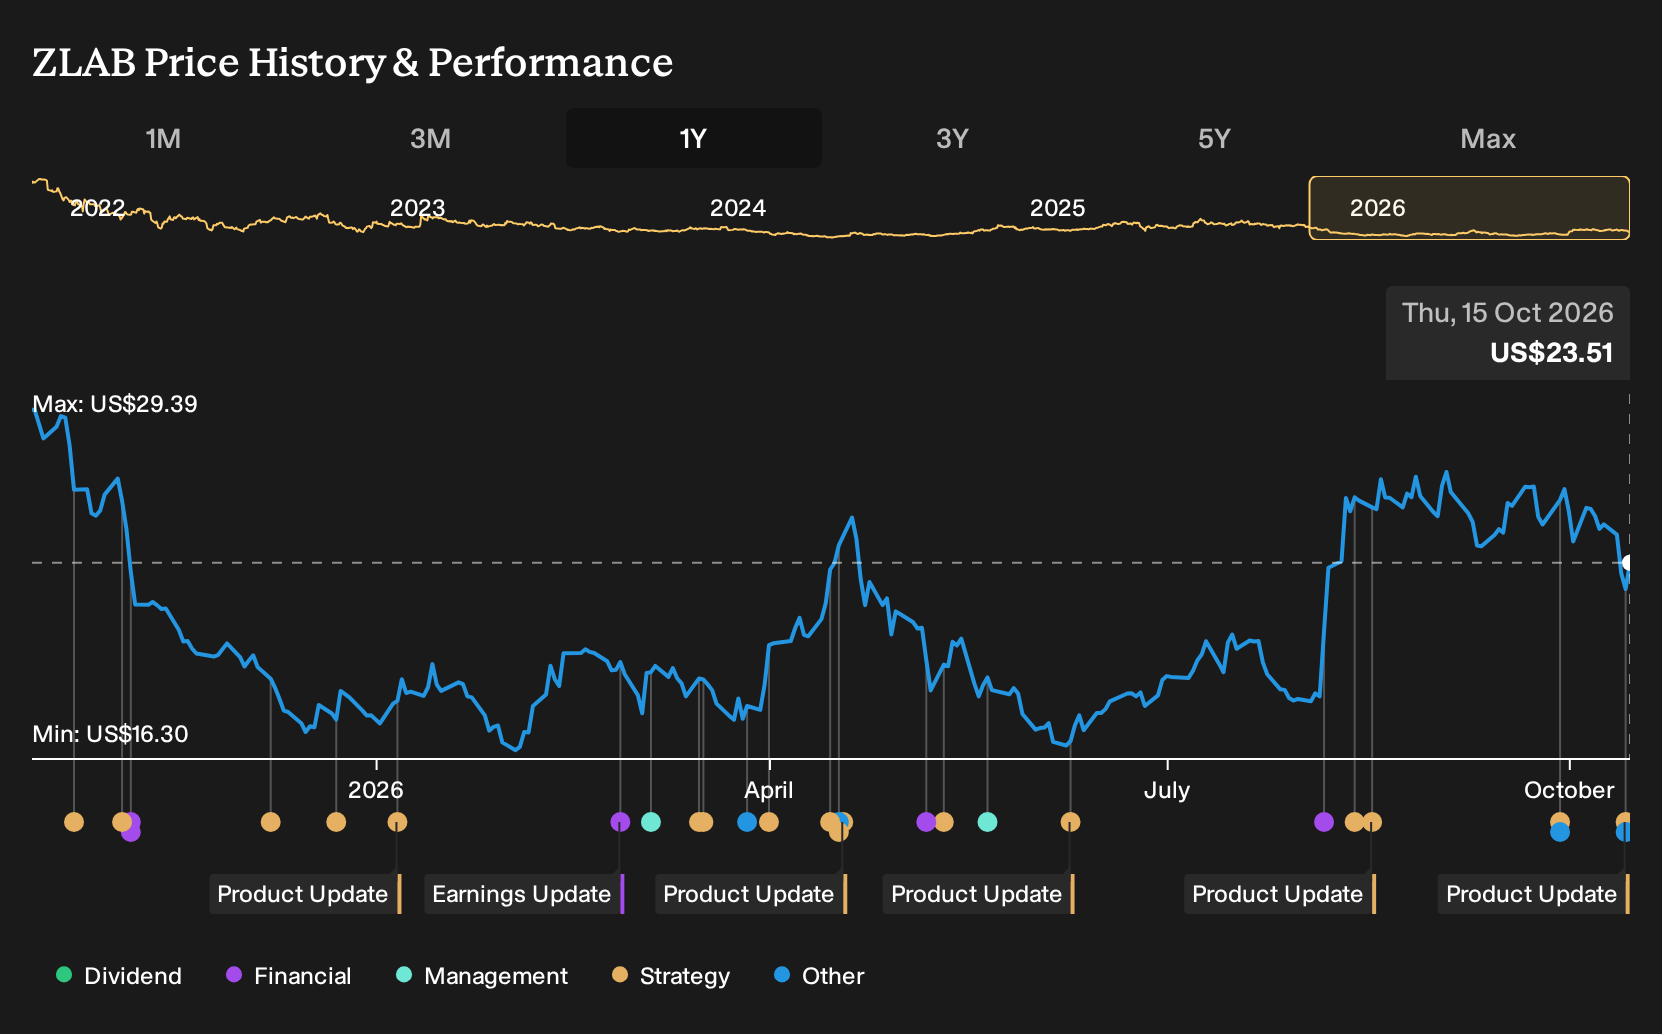
Discover how Zai Lab's fair value indicates a 42% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts regulatory risk in China front and center for Zai Lab. The most cautious analysts were modeling slower progress, with revenue reaching about US$702.1m and earnings of US$127.9m by 2029, and saw only a 3.8% upside to US$24.25. These forecasts were all set before the ZL-1503 news, so you may want to compare several viewpoints and decide which assumptions you find more realistic.
Explore 3 other Zai Lab fair value estimates, including one that suggests it could be worth just $24.25.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Zai Lab research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zai Lab. The report includes a comprehensive fundamental analysis summarized in a single visual (the Snowflake), making it easy to evaluate Zai Lab's overall financial health at a glance.
Looking for more Zai Lab style investment ideas?
If you want to apply the same kind of structured thinking used on Zai Lab to a wider watchlist, the Simply Wall St Screener can help you quickly sort through opportunities that fit your risk tolerance and return goals.
- If capital preservation comes first for you, start with companies that score well on resilience and risk, using the 32 resilient stocks with low risk scores as a filter for sturdier candidates.
- If you care most about financial strength, focus on balance sheets and underlying fundamentals through the list of solid balance sheet and fundamentals (25 results) to narrow down durable businesses.
- If you are hunting for less crowded opportunities, look toward under-followed quality using the 20 high quality undiscovered gems to surface potential prospects that might sit outside the usual headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com