


Ahead of GE Aerospace Earnings, Here's What Barchart Data Says Comes Next for GE Stock
GE Aerospace (GE) shares have been under significant pressure since early August, but the options market believes the company’s upcoming earnings event on Oct. 20 is unlikely to offer any relief. Consensus is for the aerospace and jet engine specialist to report $2.01 in earnings per share (EPS) for Q3, which would represent about 20% growth on a year-over-year basis.
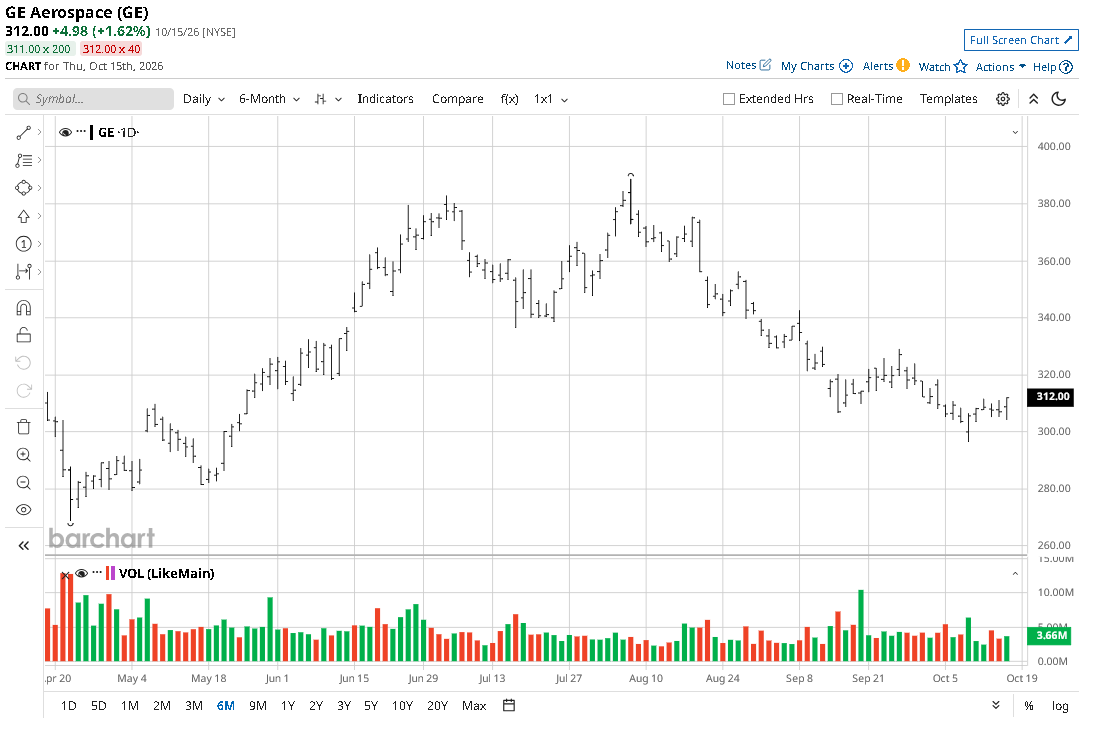
Heading into the quarterly print, GE Aerospace stock is down roughly 19% versus its year-to-date high.
Where Options Data Suggests GE Aerospace Stock Is Headed
The derivatives market believes there’s a bigger probability of a post-earnings decline in GE stock than a post-earnings surge.
According to Barchart’s data, the put-to-call ratio on contracts expiring at the end of October sits at 1.12x currently, signaling a bearish skew. A reading above 1.00x is typically interpreted as bearish. The lower price on those options contracts is set at $291 as of this writing, indicating potential for a nearly 6% decline within days after the earnings event.
Crucially, technicals mirror this options market sentiment, with GE Aerospace currently trading well below its major moving averages (MAs), suggesting bears remain firmly in control for now.
Institutional Investors Have Been Selling GE Shares
Caution is warranted in playing GE Aerospace at current levels also because institutional investors have been unloading shares in recent months. These include Courier Capital, Essex, Perpetual Ltd, and the State of Alaska, all of which trimmed their respective stakes in the company rather significantly in Q3.
Investors should also note that GE is currently trading at a forward price-to-earnings (P/S) multiple of nearly 39x, which makes it an expensive stock to own heading into 2027.
On the flip side, however, GE Aerospace shares currently pay a small dividend yield of 0.6%, which makes them somewhat more attractive as a long-term holding.
GE Aerospace Remains Buy-Rated Among Wall Street Firms
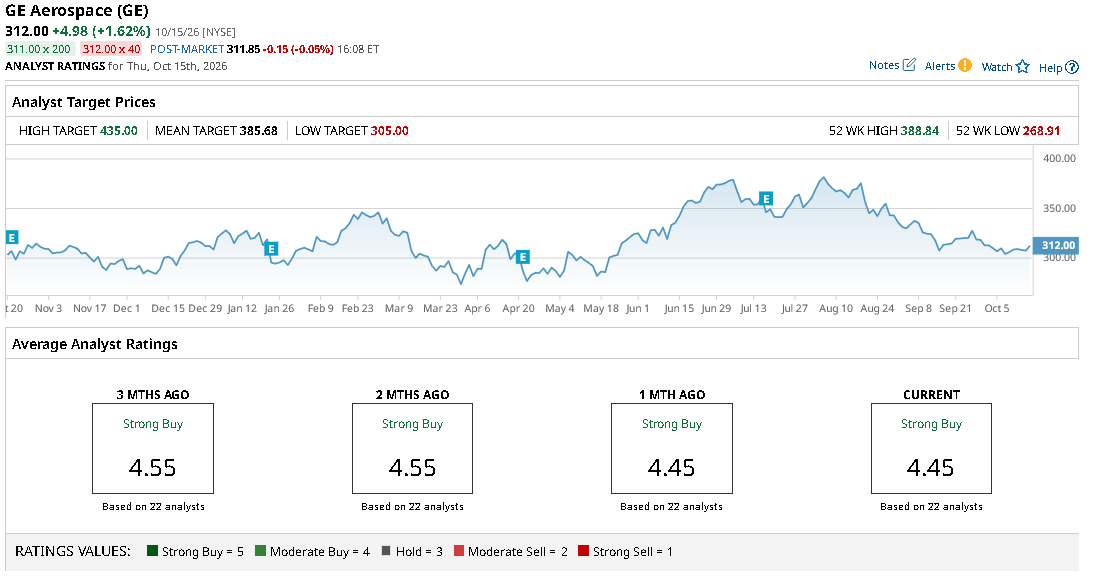
Wall Street analysts do not appear to agree with options traders on GE Aerospace. According to Barchart, the consensus rating on GE shares remains at “Strong Buy,” with the mean price target of about $386 indicating potential for a 23% rally from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.