


E-L Financial (TSX:ELF) Rides Undervalued Financials Rally But Is It Still Cheap
Renewed interest in undervalued financial stocks has pulled E-L Financial (TSX:ELF) into the spotlight, as its low P/E ratio and exposure to Canadian financial markets have put its earnings power under closer scrutiny.
Short term momentum around E-L Financial has been strong, with a 1 month share price return of 10.28% and a 7 day move of 8.98% lifting the stock to CA$19.53. At the same time, the 1 year total shareholder return of 29.39% and very large 3 and 5 year total shareholder returns point to a long running rerating rather than a brief spike driven only by the latest interest in its low P/E and exposure to Canadian financial markets.
Scan similar rerating stories around E-L Financial by running the hand picked 6 high quality undervalued stocks, which highlights companies that share low P/E profiles and renewed interest in undervalued financial stocks.
E-L Financial appears to be a solid financial holding company on paper. However, the recent share price jump has sharpened the most important question: is this strength already fully reflected in the valuation, or not?
Price-to-Earnings of 3.7x: Is it justified?
On simple earnings math, E-L Financial looks heavily out of sync with peers, trading on a P/E of 3.7x at a last close of CA$19.53 while broader insurance stocks in North America and its direct peer group sit at much higher levels.
The P/E ratio compares what investors are paying today for each dollar of earnings. For a financial holding group like E-L Financial, which reports both investment and insurance profits, this measure captures how the market is weighing its current profit stream against alternatives in the same sector.
Relative to its industry, the discount is stark. E-L Financial is described as good value on a P/E of 3.7x compared with about 11.4x for the North American insurance space and roughly 16.4x for its peer average. This points to the market assigning a far lower earnings multiple to the stock than to comparable insurers.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 3.7x (UNDERVALUED)
Still, the low P/E on E-L Financial could reflect concerns around the volatility of insurance and investment earnings or the complexity of its holding company structure.
Find out about the key risks to this E-L Financial narrative.
Another view on E-L Financial’s value
A second lens comes from the SWS DCF model, which estimates the future cash flow value of E-L Financial at CA$78.02 per share compared with the current CA$19.53 price. That gap suggests the stock screens as heavily undervalued on this framework. The key question is whether you trust the cash flow assumptions sitting underneath it.
Look into how the SWS DCF model arrives at its fair value.
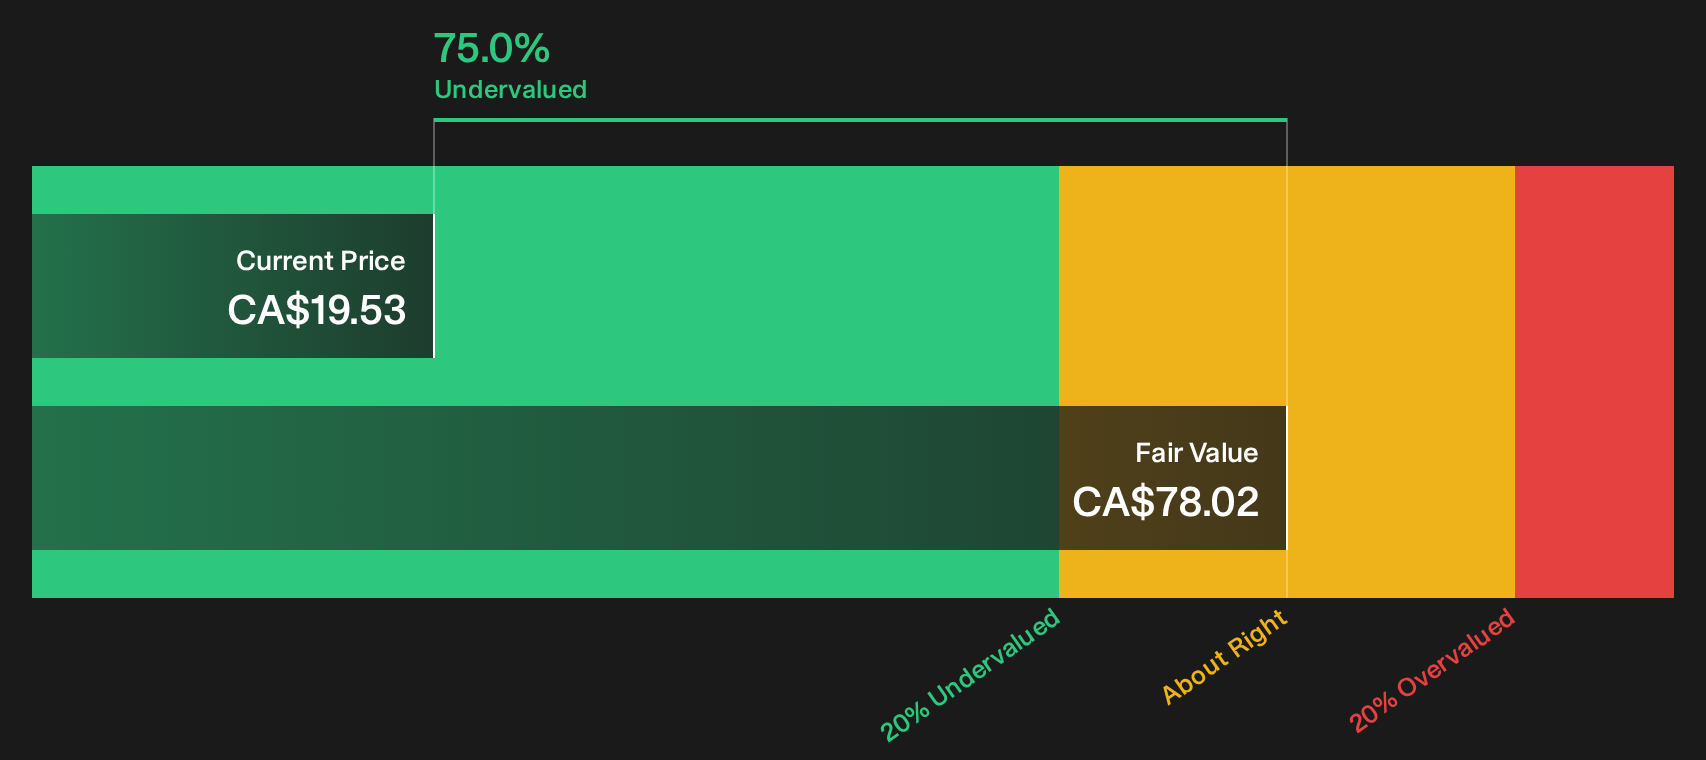
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out E-L Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the tone so far feels constructive on E-L Financial, now is the moment to check the data yourself and pressure test the optimism. Finish your review by weighing the 2 key rewards
Looking for more investment ideas beyond E-L Financial?
You have already done the hard part by digging into E-L Financial. Do not stop here when a few more focused screens could help sharpen your whole portfolio.
- Target resilient balance sheets by reviewing a list of solid balance sheet and fundamentals (8 results) that filters for companies pairing financial strength with solid fundamentals.
- Hunt for potential mispricings through a 10 high quality undiscovered gems that highlights quality businesses the broader market may be overlooking.
- Prioritise capital preservation and steadier profiles by running a 8 resilient stocks with low risk scores that zeroes in on companies with lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com