


How BofA Upgrade At BorgWarner (BWA) Has Changed Its Investment Story
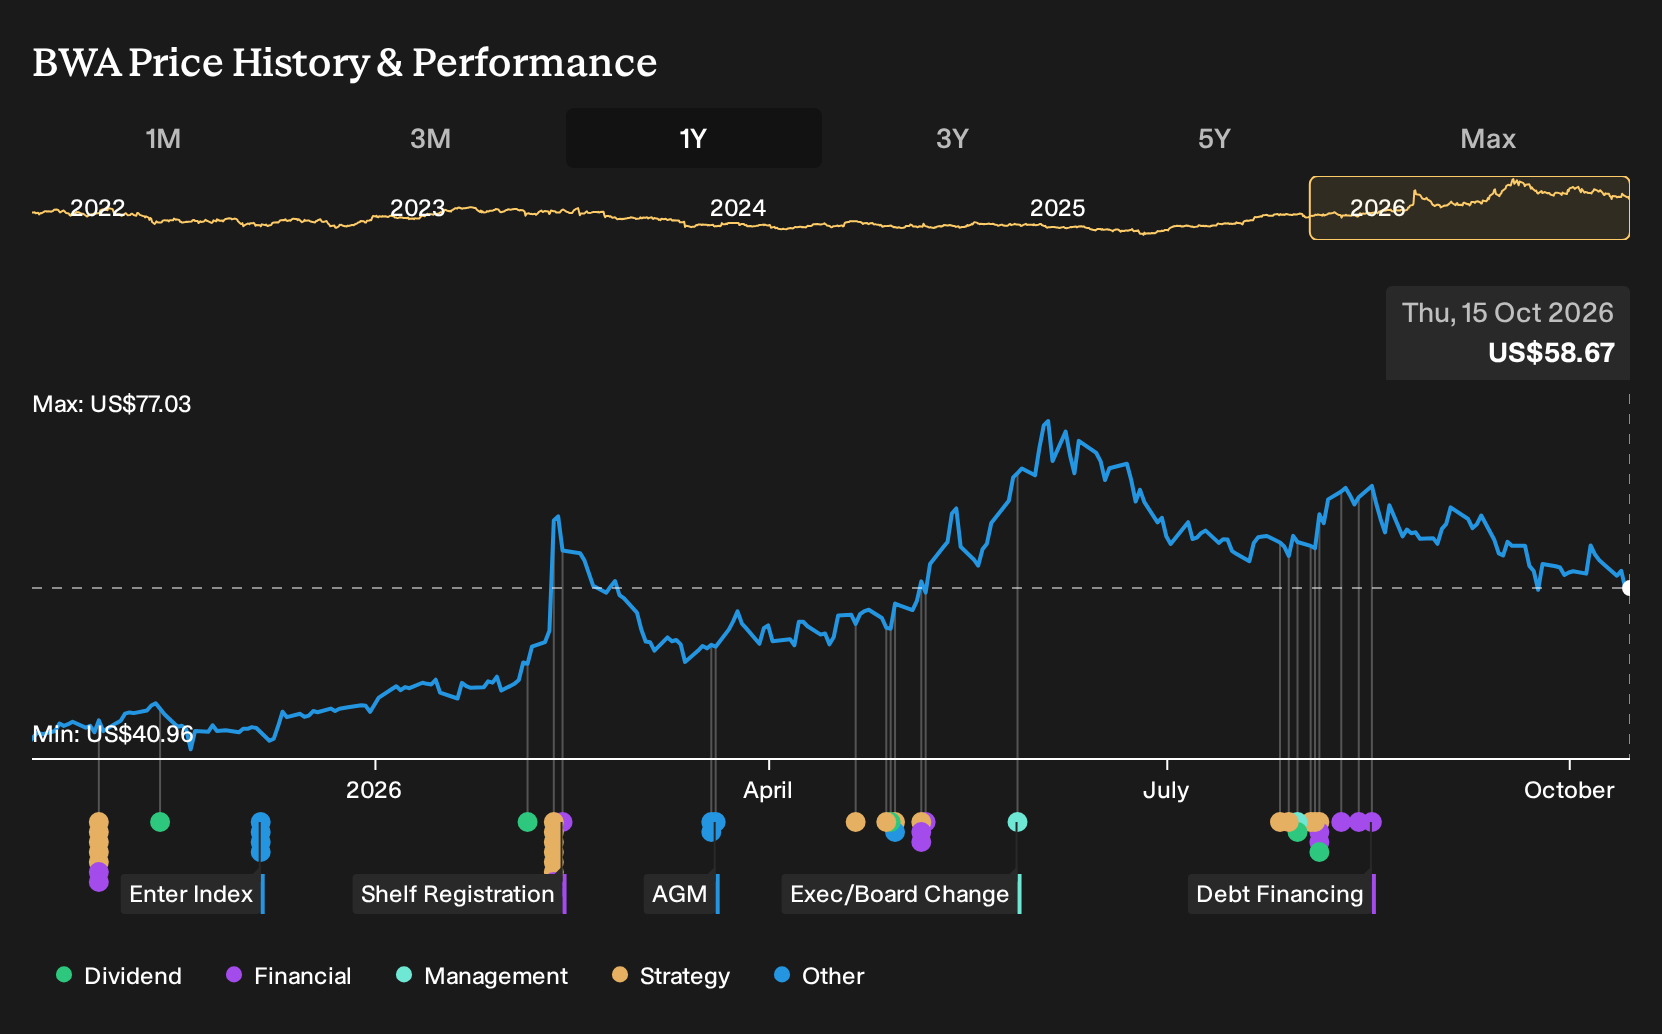
- BorgWarner received an upgrade from BofA Securities after the bank highlighted expected acceleration in the core auto business in 2027 and 2028, along with near term potential for its turbine generator system in data center power.
- The focus on data center power for AI positions BorgWarner to extend its technology base beyond light vehicles into a separate industrial revenue stream that is less tied to traditional auto cycles.
- This article examines how BorgWarner's investment narrative intersects with the AI driven data center turbine opportunity highlighted in the recent upgrade.
Compare BorgWarner's new AI driven power angle with other potential beneficiaries of the same trend by scanning our hand picked 94 AI infrastructure stocks.
BorgWarner Investment Narrative Recap
To own BorgWarner, you need to believe the vehicle tech group can keep shifting its earnings mix away from legacy combustion products and toward higher value electrified and industrial power solutions. The recent focus on AI driven data center power fits that idea, but the key near term swing factor still looks like execution on booked auto program launches.
The biggest near term risk remains the drag from the battery business and any faster than expected pressure on combustion heavy lines such as turbochargers and VCT. The upgrade itself does not change that. It simply spotlights the turbine generator program as an extra potential offset if industrial demand proves dependable.
The turbine generator program for data center power is the announcement that most closely ties into this upgrade. Management has outlined a 2 GW plant in North Carolina and indicated potential revenue of about US$300 million in 2027 at mid teens incremental margins. That puts real numbers behind the AI infrastructure narrative around BorgWarner.
For you as an investor, the operational question is whether BorgWarner can bring that facility online, win meaningful orders, and slot this industrial stream alongside auto contracts and the battery wind down. Success here could help absorb volatility from light vehicle cycles and the shrinking battery unit. Failure or delays would leave the business more exposed to its existing combustion and EV mix.
BorgWarner's current analyst storyline points to US$16.5b in revenue and US$1.2b in earnings by 2029, based on forecast top line expansion of 4.9% per year and an earnings rise of about US$785m from the current US$415.0m level.
Uncover why BorgWarner's fair value indicates a 39% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view says BorgWarner is leaning too hard on the turbine generator story. The most cautious analysts were only penciling in about US$15.2b of revenue and US$969.5m of earnings by 2029, with a 13.9x P/E. That is a far more restrained take than consensus, and this new AI power angle could reshape both narratives.
Explore 3 other BorgWarner fair value estimates, including one that suggests it could be worth just $81.33!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BorgWarner research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BorgWarner. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BorgWarner's overall financial health at a glance.
Looking For More Investment Ideas Beyond BorgWarner?
If the BorgWarner story has you thinking about where else AI, cash flow resilience, or balance sheet strength could matter, it helps to scan a wider field of stocks using focused screens.
- If you want potential mispricing combined with quality fundamentals, start with a 33 high quality undervalued stocks that may merit a closer look.
- For investors who value stability and capital preservation, consider companies in a 32 resilient stocks with low risk scores that score well on resilience.
- To broaden your watchlist with financially robust operators, filter for businesses in a list of solid balance sheet and fundamentals (25 results) that can support long term investment cases.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com