


PBF Energy (PBF) Stock Stays Reasonable On Tight Fuel Market News
PBF Energy has turned into one of the stronger performers in the refining space in recent years, which naturally puts a spotlight on what investors are paying for its earnings today. With the share price now reflecting a long run of gains, the question is how well that move lines up with the profits the business is currently generating.
- Over the past 5 years the stock has delivered a very large total return, which raises the issue of how much of that journey is now embedded in the earnings multiple.
- Recent coverage of tighter fuel markets and stronger refining margins suggests investors may be building in expectations for PBF Energy's future profitability and cash generation that go beyond current conditions.
- There is a second opinion on PBF Energy worth weighing. See what analysts think PBF Energy's shares could be worth.
The issue now is whether PBF Energy's current share price is adequately supported by its earnings once you compare it with the Fair Ratio benchmark.
If you want a broader view of how other refiners and energy producers are priced on similar themes, a focused stock screen built around 42 power grid technology and infrastructure stocks can be a useful next step.
Does PBF Energy Look Undervalued on Earnings?
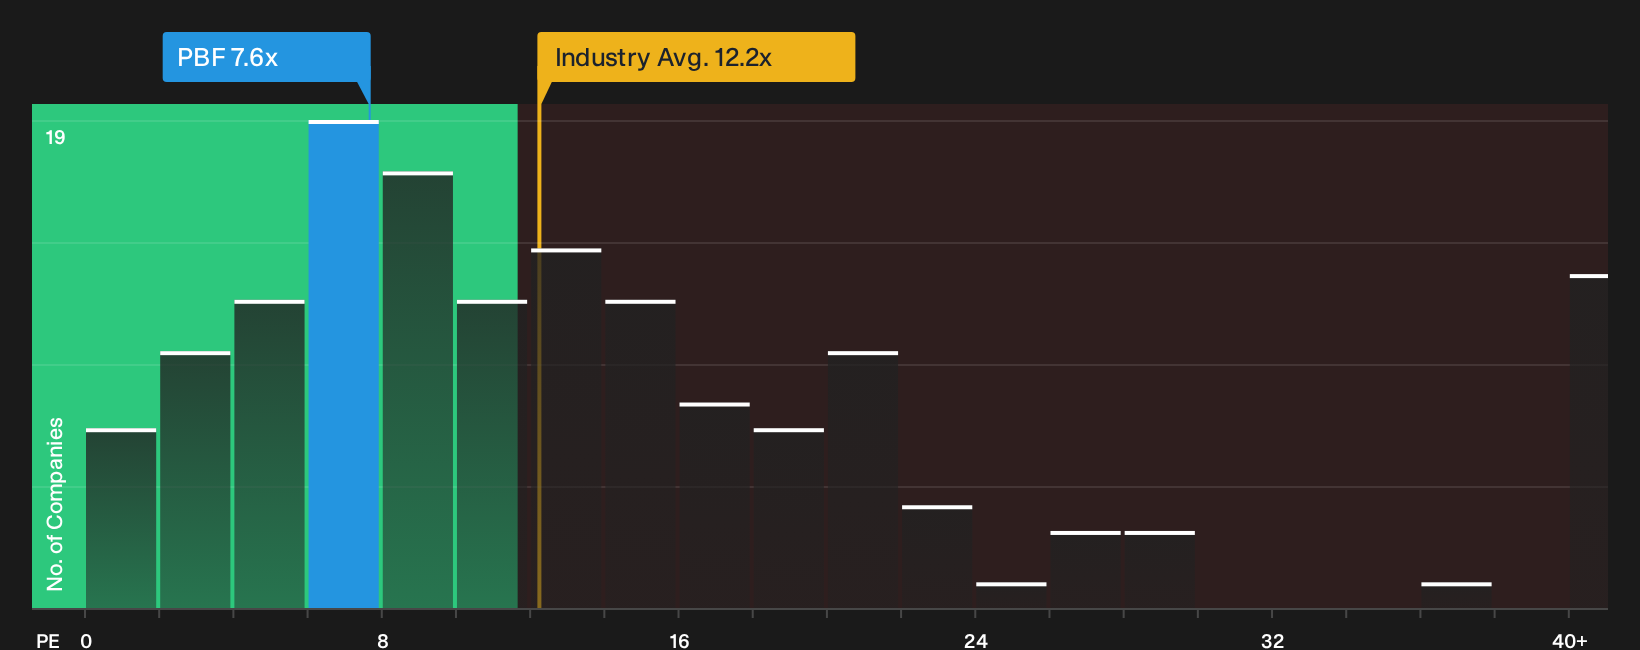
The P/E ratio suits a refiner like PBF Energy because earnings remain the anchor metric most investors watch for this kind of business. PBF Energy currently trades on about 7.6x earnings, which is meaningfully lower than the Oil and Gas sector average of roughly 12.2x and far below the broader peer group on about 34.7x. That places the stock on a comparatively low earnings tag despite its recent share price strength.
Because the Fair Ratio framework adjusts for factors such as the company’s risk profile, size and sector, it points to a level above where the P/E sits today. This suggests the shares screen as undervalued on this lens. Despite the nearly 70% rise highlighted in recent refining news coverage, the market is still pricing PBF Energy at a discount to what this earnings based model implies. Explore the numbers behind PBF Energy's P/E valuation.
The PBF Energy Narrative: What Would Justify Today's Price?
PBF Energy's valuation gap raises a simple next step: ask what kind of future would actually make today's share price look high or low. Simply Wall St Narratives on the Community page set out those possible paths in plain English for PBF Energy's earnings, margins and growth. Rather than relying on one multiple or a single model, each narrative lays out the assumptions behind its fair value so you can compare them with the company’s results as they arrive.
One of the top community narratives on PBF Energy: 15% overvalued
"PBF faces persistent operational, regulatory, and market challenges that threaten profitability and long-term growth, with limited diversification and heavy exposure to evolving fuel demand trends..."
Discover why this Narrative puts PBF Energy at 15% overvalued.
PBF Energy: why the current share price is only half the story
Market multiples show what investors pay today, and the projections from analysts sketch out where they expect PBF Energy to be a few years from now. Explore where analysts expect PBF Energy to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com