


Corning (GLW) Could Be 27% Undervalued As AI Fiber Deals Lift The Narrative
Why Corning’s AI Fiber Push Matters Now
Corning (GLW) is back in focus after strong momentum in its Optical Communications division, anchored by long term fiber deals with Amazon and Nvidia and a higher long range sales ambition despite recent sector volatility.
Recent trading has been choppy. The share price is down 9.4% over the last week and about 10.5% over 90 days. However, Corning still carries a strong 52.7% year to date share price return and a very large 3 year total shareholder return, indicating that momentum has built over time despite bouts of volatility.
Spot 93 AI infrastructure stocks that could benefit from the same AI data center fiber build out powering Corning’s long term deals with Amazon and Nvidia.Corning’s AI fiber story is stronger, yet the share price has just stepped back after a big year to date run. The key question is whether that reset leaves more upside than downside from here, as the valuation section spells out next.
Most Popular Narrative: 27% Undervalued
Corning closed at $138.43, while the most followed narrative pegs fair value near $189.94. The gap between price and perceived worth is significant and is described as being connected to specific growth projects across optical, solar and photonics.
The build out of an integrated U.S. solar manufacturing chain, with a stated goal of reaching about $3b in solar revenue by around the end of 2027 at profitability above the corporate average, creates a potential new earnings stream for Corning that sits alongside Optical Communications.
Investment in passive Photonics content for co packaged and near package optics, aimed at a potential $10b revenue platform by 2030, gives Corning a new avenue for inside the box data center sales that could add incremental revenue and support earnings growth if adoption scales.
See why 99 investors see Corning as 27% undervalued.
Result: Fair Value of $189.94 (UNDERVALUED)
Still, Corning’s reliance on non-GAAP metrics and potential dilution from its $2 billion at-the-market equity program could weaken confidence in the current undervaluation story.
Find out about the key risks to this Corning narrative.
Another View: Corning Through the P/E Lens
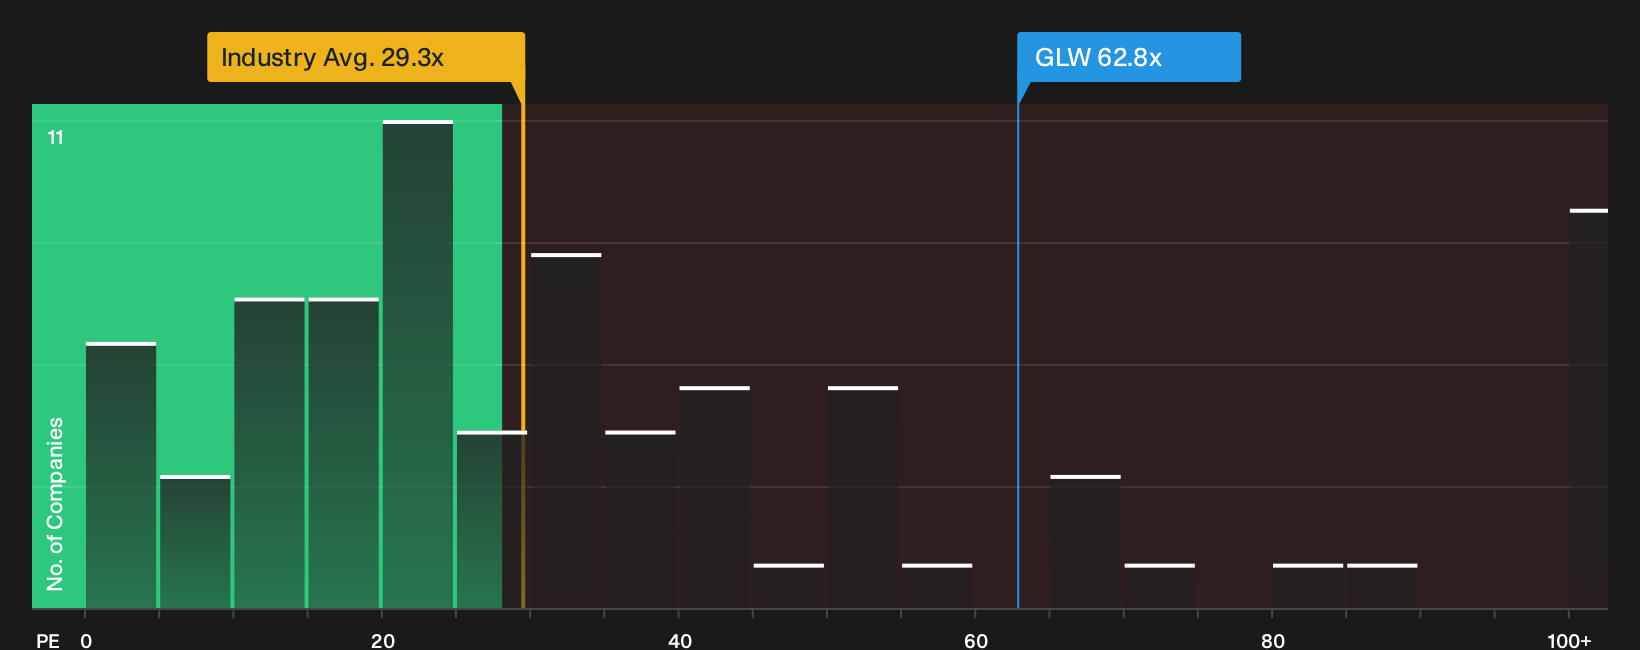
Looking at Corning through simple P/E maths makes the story feel less one sided. The current P/E of 62.8x is well above the US Electronic industry at 29.3x and also ahead of Corning’s own fair ratio of 53x, which points to valuation risk if sentiment cools.
For a different angle on how this price stacks up, including how the gap to the fair ratio could close in either direction, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Corning is clearly mixed, with big projects on one side and clear pressure points on the other. Take a moment to weigh the evidence, stress test the numbers for yourself, and then check the 3 key rewards and 3 important warning signs
Looking for more Corning sized investment ideas?
Do not stop with Corning. Broaden your watchlist with fresh angles on other companies that match the kind of risk reward profile you care about most.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that filters for stronger fundamentals and financial staying power.
- Zero in on potential mispricings and use the 32 high quality undervalued stocks to focus on businesses where quality and valuation may be out of sync.
- Prioritise stability and income and let the 8 dividend fortresses surface companies aiming to combine higher yields with more durable payout records.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com