


Power Corporation Of Canada (TSX:POW) Faces An Earnings Test, Is The Stock Overvalued?
Investor focus on Power Corporation of Canada (TSX:POW) has sharpened as the group’s insurance and asset management subsidiaries release operating results, putting sustainable earnings, profitability, and capital returns under closer scrutiny.
At a share price of CA$93.54, Power Corporation of Canada has seen short term momentum pick up, with a 1 day share price return of 3.23% and a 7 day share price return of 6.16%. A 1 year total shareholder return of 56.96% and a 3 year total shareholder return of over 3x suggest longer term holders have already seen substantial gains as investors reassess earnings resilience and capital return potential.
Scan for other insurers and financials showing similar momentum and earnings resilience with our curated list of list of solid balance sheet and fundamentals (8 results) as a comparison set to Power Corporation of Canada.
After such a sharp rerating in Power Corporation of Canada, the share price now sits close to analyst targets, while the intrinsic estimate points lower. Where does fair value really land in that spread?
Price-to-Earnings of 22.4x: Is it justified?
Power Corporation of Canada is trading on a P/E of 22.4x, which places a richer tag on its earnings than peers and the broader insurance industry, even with the recent share price strength.
The P/E ratio compares what investors pay for each dollar of current earnings. For a diversified financial group like Power Corporation of Canada, which spans insurance, wealth management, and alternative assets, this gauge is often used as a simple shorthand for how the market weighs near term profit against perceived stability and future cash generation.
Here, the message is clear. The stock is described as expensive against the peer average P/E of 17.8x, and even more stretched when set beside the North American insurance industry average of 11.4x. The gap is wide relative to an estimated fair P/E of 14.9x, which suggests the market valuation is materially higher than the level that model indicates it could gravitate toward over time.
Explore the SWS fair ratio for Power Corporation of Canada.
Result: Price-to-Earnings of 22.4x (OVERVALUED)
Still, any stumble in earnings resiliency at key subsidiaries, or a shift in capital return plans, could quickly challenge the premium that Power Corporation of Canada commands.
Find out about the key risks to this Power Corporation of Canada narrative.
Another View: What the SWS DCF Model Says
The multiples point to Power Corporation of Canada looking expensive, yet the SWS DCF model tells a slightly softer story. At CA$93.54 versus an estimated future cash flow value of CA$90.21, the shares screen as modestly overvalued rather than wildly stretched. How much of that gap are you comfortable paying for today?
Look into how the SWS DCF model arrives at its fair value.
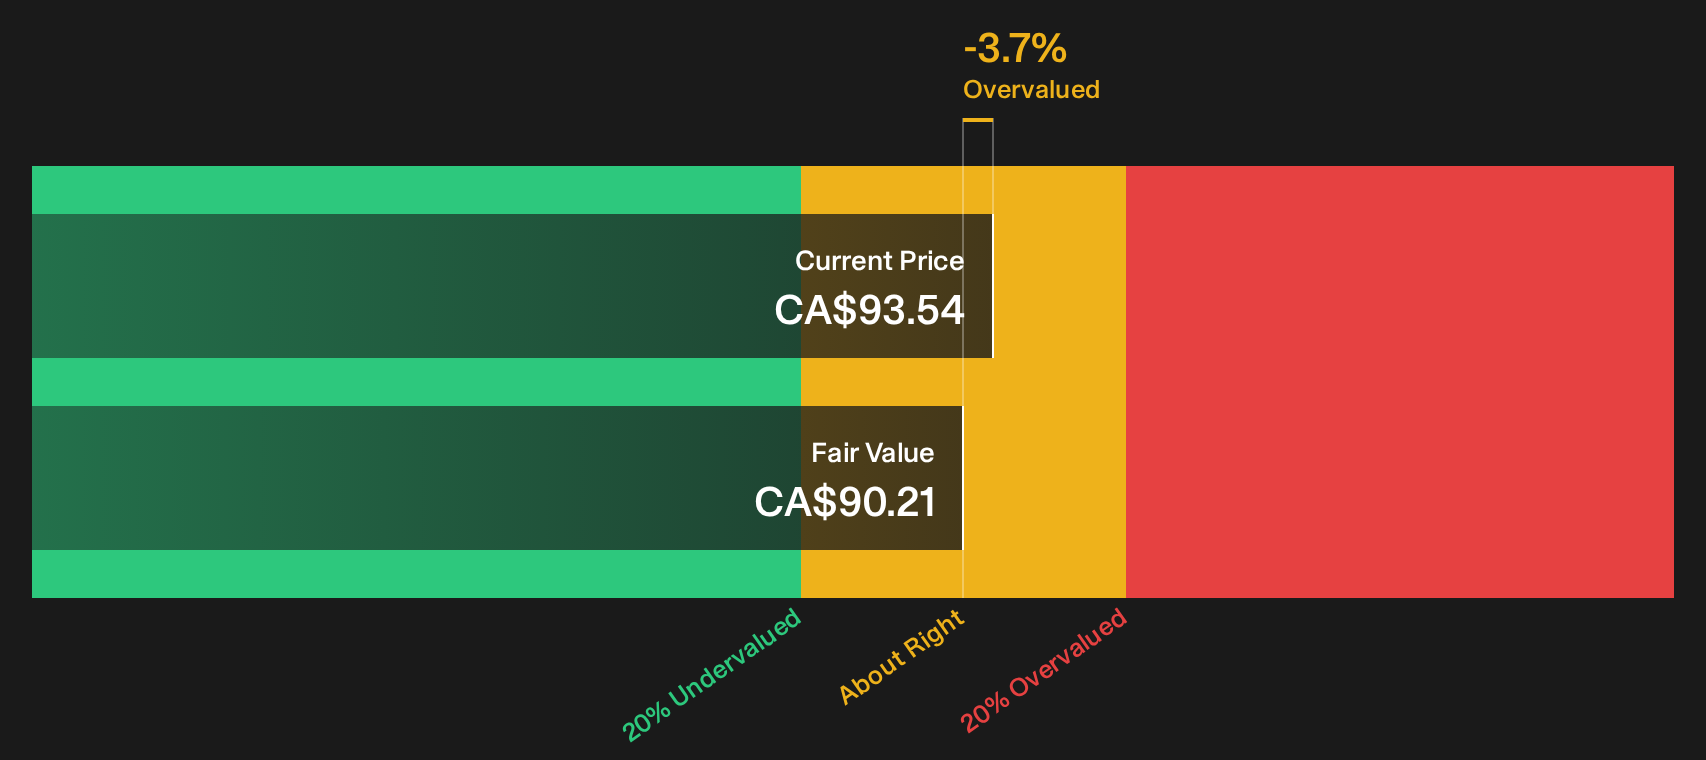
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Power Corporation of Canada for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Power Corporation of Canada is clearly divided, which is exactly when your own judgment matters most. Act while the data is fresh and weigh both sides of the story by digging into the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Power Corporation of Canada?
If Power Corporation of Canada has sharpened your focus on quality and valuation, you can widen your opportunity set now using a few targeted screeners built around fundamentals.
- Target resilient balance sheets that can handle shocks by running your filters through the 8 resilient stocks with low risk scores.
- Hunt for mispriced quality where fundamentals and valuation work together by starting with the 6 high quality undervalued stocks.
- Build a watchlist of potential income pillars and compare yields, coverage, and consistency with the 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com