


Did Record SBA Lending Just Shift M&T Bank's (MTB) Investment Narrative?
- M&T Bank recently ranked No. 1 across its communities for SBA 7(a) lending by number of loans in fiscal 2026 and reached the highest SBA 7(a) loan volume and dollar amount in its history, while also moving to No. 5 nationally among SBA 7(a) lenders.
- This record SBA 7(a) production, achieved while national SBA lending volume and dollars were under pressure, highlights how M&T Bank’s small business franchise is generating business growth in a tougher credit environment, alongside expectations for year over year revenue and earnings increases in Q3 2026.
- We will now look at how M&T Bank’s record SBA 7(a) activity could reshape the broader investment narrative investors are using.
M&T Bank Investment Narrative Recap
To own M&T Bank, you need to believe its relationship driven model, fee income mix and tech investment can keep returns resilient even when loan demand or funding costs shift. The record SBA 7(a) volumes reinforce that the small business engine is still humming. The key near term swing factor remains how Q3 2026 revenue and earnings land against expectations in a tougher credit backdrop.
The biggest risk is still pressure on funding costs and expenses. Higher priced deposits and elevated noninterest expense guidance near US$5.5b to US$5.6b for 2026 could weigh on net interest margin if top line progress slows. The latest SBA momentum helps sentiment but does not remove that cost and funding tension.
The fresh data point that ties closest to this is the expectation for year over year increases in M&T Bank’s Q3 2026 revenue and earnings. SBA 7(a) outperformance gives some operational support for that, since it hints at underlying loan demand, customer stickiness and cross sell potential in small business banking.
For catalysts, investors are watching whether that upcoming print confirms that fee lines and core lending are carrying enough weight to offset higher expenses and deposit competition. If results show stable net interest income alongside healthy fee revenue around the guided US$2.8b to US$2.85b for 2026, it would help the thesis that current spending and capital deployment are translating into durable earnings power.
M&T Bank's narrative projects US$10.9b revenue and US$3.1b earnings by 2029, based on analyst estimates. This assumes 5.0% yearly revenue growth and an earnings increase of about US$200m from US$2.9b today to the US$3.1b consensus forecast.
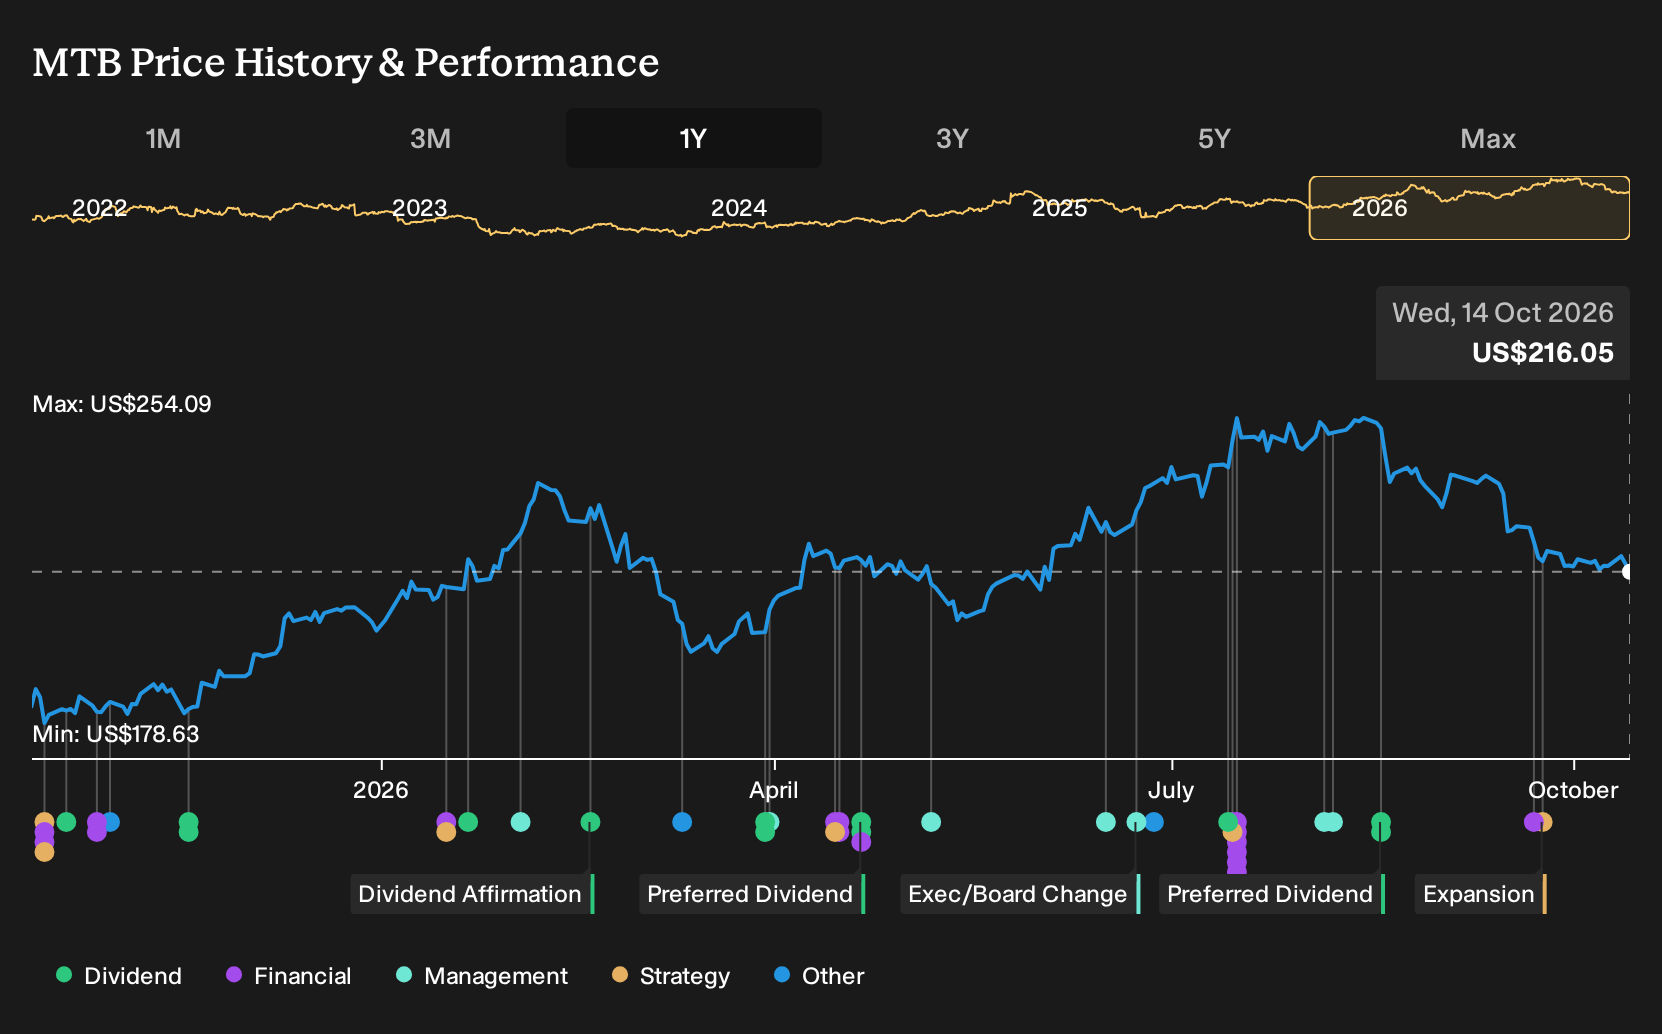
Uncover why M&T Bank's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only shows two fair value views for M&T Bank, yet they already stretch from about US$253 to roughly US$417, which is a wide span for a single stock. Treat that gap as a signal that opinions vary sharply. Then weigh it against risks around funding costs, expense guidance near US$5.6b and the potential payoff from fee growth and tech investment. Use those contrasts to test your own thesis and review other community perspectives before deciding how M&T fits in your portfolio.
Explore another M&T Bank fair value estimate, including one that suggests it could be worth just $253.08.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your M&T Bank research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for M&T Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate M&T Bank's overall financial health at a glance.
Looking for more investment ideas beyond M&T Bank?
Once the M&T Bank story is clear in your mind, it can help to compare it with a few very different opportunities so you see where risk, balance sheet strength and payout profiles line up with your own goals.
- If you want potential upside with tighter risk controls, you can focus on companies that pair solid fundamentals with historically resilient trading patterns through the 32 resilient stocks with low risk scores.
- For investors who care most about quality and price discipline, consider scanning a wider set of stocks that combine strong cash generation with supportive valuations using the 32 high quality undervalued stocks.
- If reliable income matters more than short term price moves, you might concentrate on businesses that offer higher yields and robust coverage metrics with the help of the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com