


Is Health Sense Launch Altering The Investment Case For Cigna (CI)?
- Cigna Healthcare recently announced Health Sense, a personalized support model that connects individuals' health data, benefits, costs and prior interactions, with an initial rollout focused on oncology and cardiometabolic customers from early 2027.
- The Health Sense launch consolidates digital tools, clinical resources and benefit information into a single experience, which could be relevant for employers seeking clearer cost control and for employees facing complex treatment decisions.
- We will now assess how Cigna Group's investment narrative could be affected by Health Sense as it expands personalized, clinically grounded support across its platform.
Cigna Group Investment Narrative Recap
To own Cigna Group, you need to believe the business can keep using Evernorth, specialty services and data driven tools like Health Sense to manage medical costs while holding on to large employer and PBM clients. The most important near term catalyst still sits in execution on the 2027 PBM selling season and the Signature model, and this news does not materially shift that focus.
The biggest near term risk remains pressure on Evernorth margins and elevated commercial medical cost trends, especially as Cigna exits the individual ACA exchanges and absorbs stranded overhead. Donna Zarcone’s planned board retirement looks like normal refreshment, not a change that alters the operating outlook or near term risk balance.
The Health Sense announcement is the clearest link to the current catalyst stack, because it extends Cigna Group’s use of AI and clinical data to tackle inefficient medical spend. Management is targeting a 10% reduction in certain avoidable costs by 2030, which directly ties into the wider effort to keep medical trends in check for employers.
Execution on Health Sense will likely be judged on adoption, measurable cost savings and how well it plugs into Evernorth’s PBM contracts and Cigna Healthcare plans. If it helps members find in network care, avoid duplicative services and use benefits more effectively, that could support the case for more stable margins and reinforce Cigna’s broader data driven health programs as a key operational catalyst.
Cigna Group's current analyst narrative points to revenue of US$324.7b and earnings of US$7.8b by 2029, based on an assumed 4.8% yearly increase in revenue and a move from US$6.4b in earnings today to that US$7.8b figure. This represents about a US$1.4b rise in profit over the period.
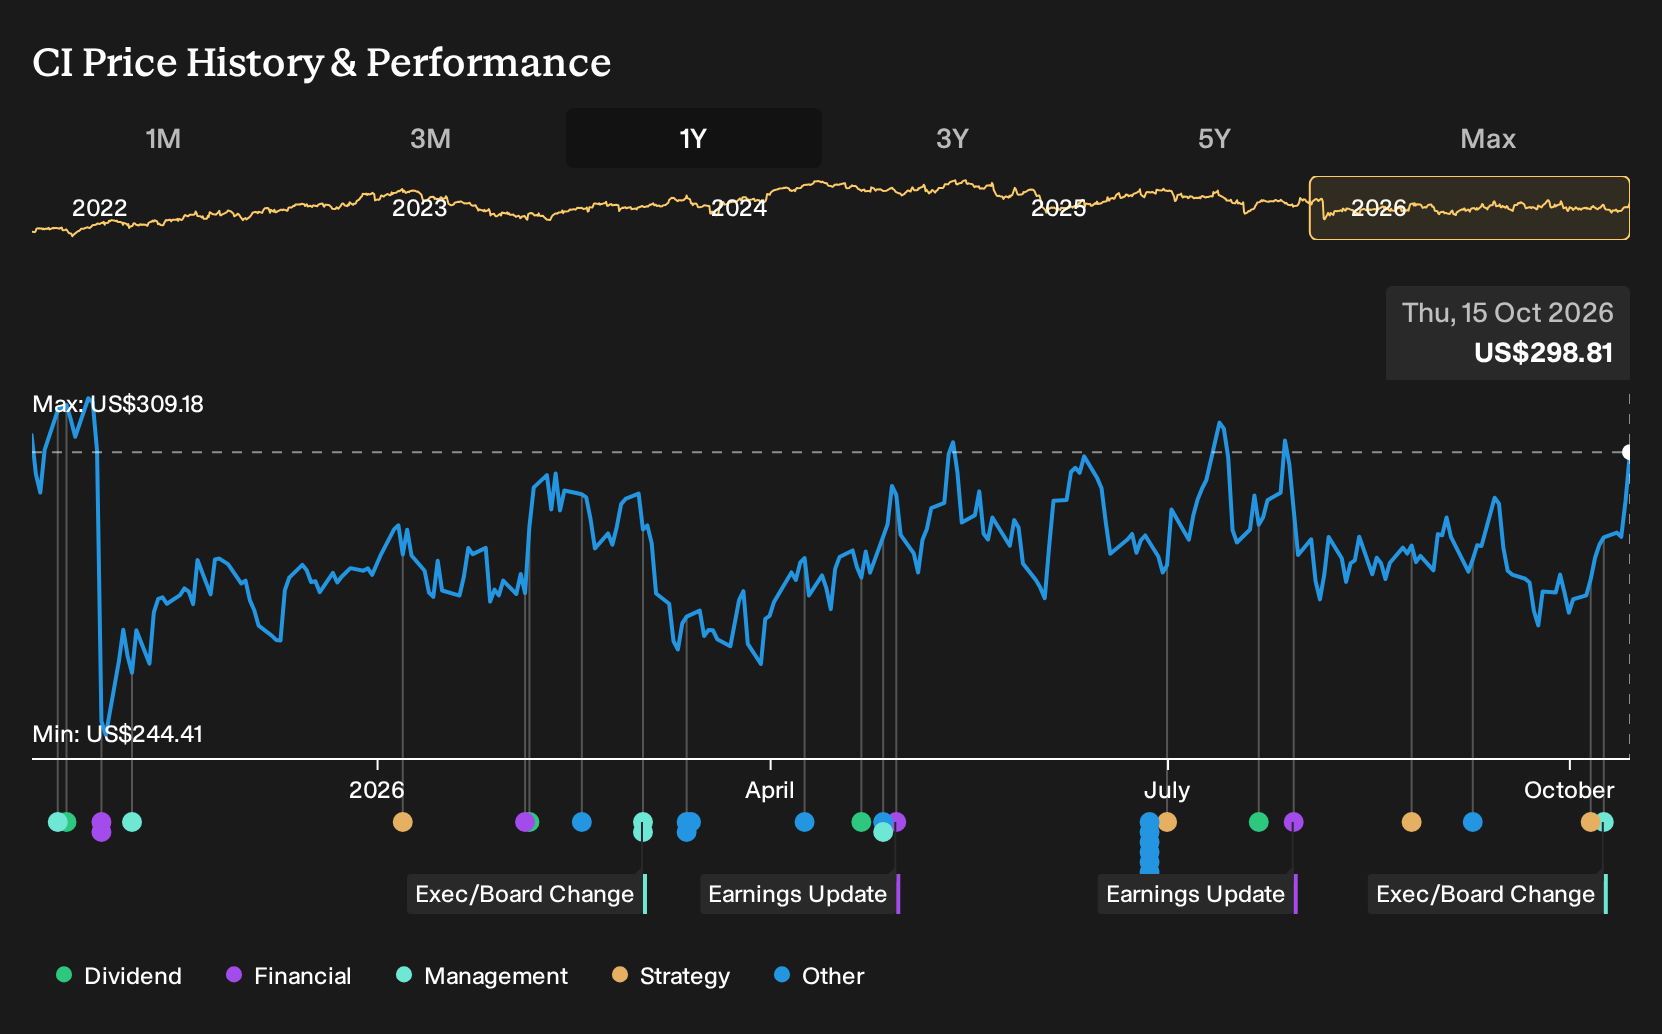
Uncover why Cigna Group's fair value indicates a 14% potential upside to its current price before the window for that discount starts to close.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community range from roughly US$319 to about US$935 per share, so there is almost a 3x gap between the lowest and highest conviction views. That spread is set against current risks around Evernorth margins and ACA exit overheads, which could influence Cigna Group’s results relative to some of the more optimistic forecasts. Opinions clearly diverge, so treat these community models as a menu of contrasting viewpoints to stress test your own thesis.
Explore 4 other Cigna Group fair value estimates, including one that suggests it could be worth just $318.90.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research.
- A great starting point for your Cigna Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cigna Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cigna Group's overall financial health at a glance.
Looking for more investment ideas beyond Cigna Group?
If Cigna Group has sharpened your focus on healthcare, cash flow and balance sheet strength, broaden that search by using screeners that surface companies with clear, data driven fundamentals instead of starting from a long, unfocused watchlist.
- If you prefer businesses that already generate solid cash and carry less financial strain, you can quickly filter for that profile using our 32 resilient stocks with low risk scores.
- If you are interested in finding companies that combine strong fundamentals with a sense that the market may be overlooking them, you can scan the 20 high quality undiscovered gems to see which ones fit that brief.
- If you care most about durable balance sheets and clean financial footing, you can work through a curated list of solid balance sheet and fundamentals (25 results) and compare those candidates to what you see in Cigna Group.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com