


PAL GROUP Holdings (TSE:2726) Could Be 51% Undervalued On Half Year Earnings
PAL GROUP Holdings (TSE:2726) just posted half-year results to August 31, 2026, with sales of ¥121,931 million and net income of ¥9,428 million, alongside slightly higher basic earnings per share.
Recent trading tells a mixed story for PAL GROUP Holdings. The share price is now ¥1,426, after a 1-day share price return of 1.06% and a 90-day share price return of 0.71%. However, the year-to-date share price return is down 28.20%, while the 5-year total shareholder return of 310.60% points to a much stronger long-run outcome.
Look beyond PAL GROUP Holdings and explore similar opportunities in retail with our hand picked 15 high quality undervalued stocks that combine solid cash generation with balance sheet strength.
PAL GROUP Holdings has delivered steady half year figures while the share price is still down sharply this year. Has most of the recovery already played out, or is meaningful upside still on the table once valuation enters the frame?
Preferred P/E of 13.7x for PAL GROUP Holdings: Is it justified?
PAL GROUP Holdings trades on a P/E of 13.7x at a share price of ¥1,426, which points to a lower valuation compared to peers despite a solid earnings track record. That gap raises the question of whether the market is being cautious, or whether the discount reflects real concerns around sustainability of recent profit trends.
The P/E ratio compares the current share price with earnings per share, so it effectively shows how much investors are paying for each unit of profit. For a retailer like PAL GROUP Holdings, this metric is a common shortcut investors use when they want to weigh current profitability against what they are willing to pay today.
On one hand, management has lifted net profit margins to 7.5% from 6%, earnings have grown 34.3% over the past year, and profit expansion over five years has averaged 24.5% per year. Those outcomes sit alongside a high Return on Equity of 21.4%, which suggests the business has been turning shareholder capital into profits efficiently. Against that earnings profile, the current P/E of 13.7x sits below an estimated fair P/E of 15.9x, which is a level the market could move towards if confidence in these profit levels holds.
On the other hand, the same 13.7x P/E is slightly expensive compared to the wider JP Specialty Retail industry average of 13.3x. The market is therefore pricing PAL GROUP Holdings at a small premium to the sector, while still leaving it on a lower multiple than the peer average of 25.3x highlighted in the checks. That combination suggests investors are applying a modest uplift for its earnings quality and growth profile, but not pushing the valuation anywhere near the higher end of sector pricing.
Explore the SWS fair ratio for PAL GROUP Holdings.
Result: Price-to-earnings of 13.7x (UNDERVALUED)
Still, the sharp year to date share price fall and a 1 year total return decline of 24% could signal waning investor confidence if profit momentum cools.
Find out about the key risks to this PAL GROUP Holdings narrative.
Another View on PAL GROUP Holdings: What the DCF Model Says
The P/E hints at PAL GROUP Holdings trading on a discount, yet our DCF model goes much further. At a share price of ¥1,426 and a future cash flow value estimate of ¥2,909.03, the stock is flagged as significantly undervalued. If that cash flow outlook holds, is the market leaving too much on the table?
Look into how the SWS DCF model arrives at its fair value.
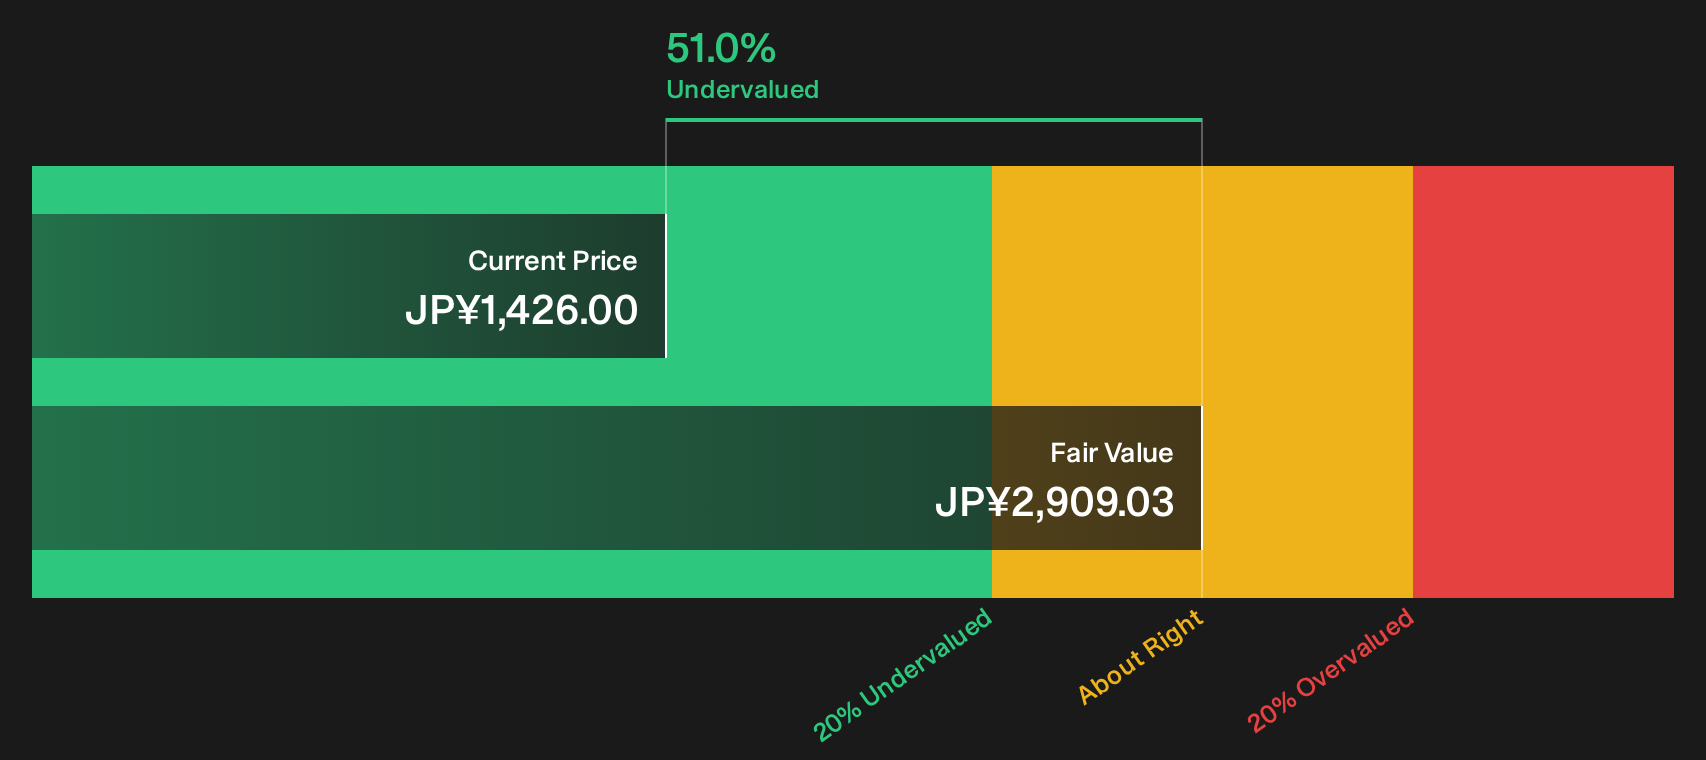
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PAL GROUP Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around PAL GROUP Holdings in this update may feel mixed. Consider moving quickly, reviewing the underlying numbers yourself, and pressure testing every assumption against the 5 key rewards
Looking for more investment ideas beyond PAL GROUP Holdings?
If PAL GROUP Holdings has sharpened your focus on valuation, do not stop here. Broaden your watchlist now and give yourself more options to compare.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (21 results) that highlights businesses with sturdy finances and room to handle shocks.
- Spot potential mispricings early by checking a 72 high quality undiscovered gems that surfaces quality companies the crowd may not be watching yet.
- Dial down volatility risks by reviewing a 21 resilient stocks with low risk scores that filters for resilient stocks with more stable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com