


Strong Profitability Outlook Might Change The Case For Investing In Butterfield Bank Stock (NTB)
- Bank of N.T. Butterfield & Son released its third quarter 2026 results in late October and held an earnings call that focused investors on the bank's profitability profile, capital position and progress on its full service banking and wealth management strategy across Bermuda and other offshore markets.
- Analyst commentary highlighted projected tangible book value per share and a high return on equity for Butterfield Bank, while also noting relatively weak net interest income trends versus the broader banking sector. This drew attention to the bank's growing reliance on fee income and wealth focused services.
- We will now look at how Bank of N.T. Butterfield & Son's projected tangible book value strength could shape its investment narrative.
Bank of N.T. Butterfield & Son Investment Narrative Recap
To hold Bank of N.T. Butterfield & Son in a portfolio, you need to be comfortable with a bank that leans heavily on high projected tangible book value, strong historical ROE and growing fee based services, while accepting softer net interest income trends. The near term story revolves around whether wealth and trust income can keep offsetting more muted lending driven revenue.
The upcoming third quarter 2026 results and earnings call look important for one key catalyst: clarity on how fee income, costs and credit quality are tracking into year end. The biggest immediate risk remains execution around higher expenses, debt funding for CIBC Caribbean and any impact from ratings pressure on funding costs.
The most relevant fresh development is Butterfield’s plan to release its third quarter 2026 results after the New York close on 27 October, with a call the following morning. That update gives you a clear checkpoint on how the bank is aligning its balance sheet, capital and cost base with the push toward fee driven banking and wealth management.
On that call, management commentary on CIBC Caribbean, loan quality and core noninterest expenses around US$93m to US$95m per quarter will matter for the medium term thesis. You get a read on whether the planned acquisition, subordinated debt issuance and current expense run rate are tracking in a way that supports projected tangible book value strength rather than diluting it.
Analysts outline a scenario in which Bank of N.T. Butterfield & Son reaches US$1.8b in revenue and US$325.0m in earnings by 2029. This implies forecast revenue growth of 42.3% per year and an earnings increase of about US$90.6m from current earnings of US$234.4m to the consensus forecast.
Uncover why Bank of N.T. Butterfield & Son's fair value indicates a 13% potential upside to its current price, which could narrow quickly.
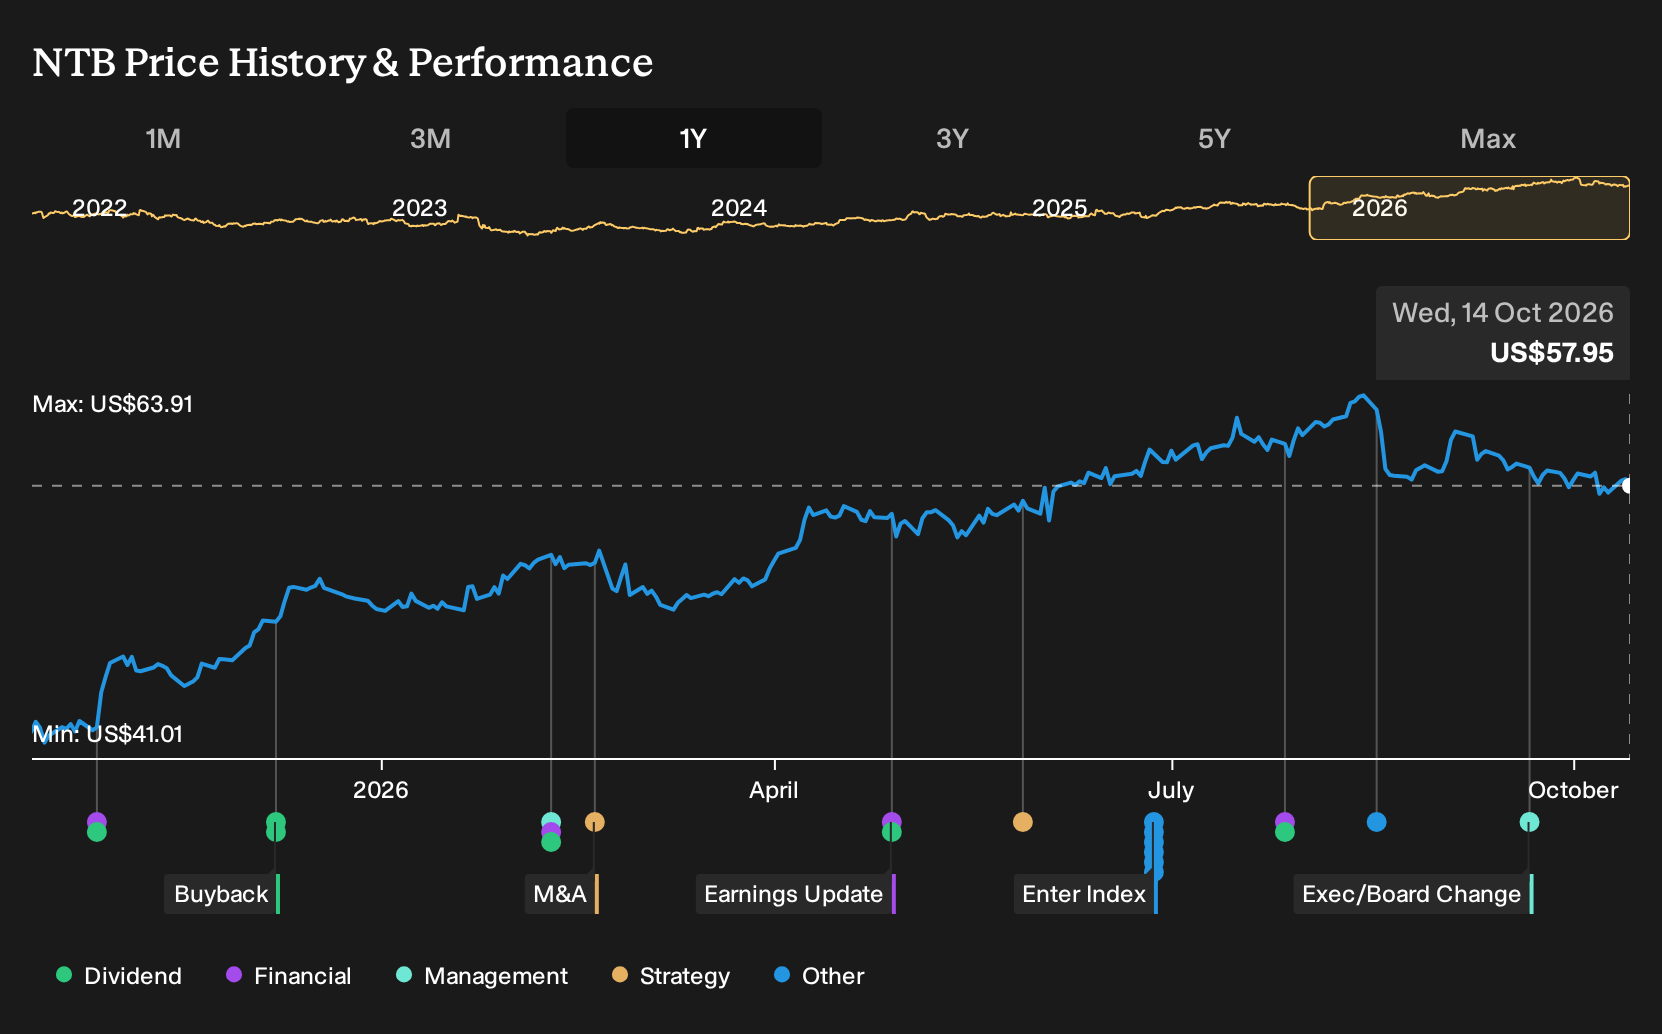
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from 65.33 to 196.44, showing how far views on Bank of N.T. Butterfield & Son can stretch. As you weigh that spread against risks around higher funding costs and expense pressure, it makes sense to compare multiple viewpoints before deciding how this story fits into your portfolio.
Explore another Bank of N.T. Butterfield & Son fair value estimate, including one that suggests it could be worth just $65.33.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bank of N.T. Butterfield & Son research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bank of N.T. Butterfield & Son. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of N.T. Butterfield & Son's overall financial health at a glance.
Looking for more investment ideas beyond Bank of N.T. Butterfield & Son?
If the story around Bank of N.T. Butterfield & Son has sharpened your sense of what you want in a financial stock, the next step is to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- For investors who want potential value combined with solid fundamentals, scan a curated set of 32 high quality undervalued stocks that share a similar blend of quality and price appeal.
- If capital preservation and balance sheet strength matter most to you, focus on companies drawn from a list of solid balance sheet and fundamentals (25 results) so you can weigh Butterfield Bank against peers with robust financial footing.
- Income focused readers who care about consistency and yield can benchmark Butterfield Bank against a group of 7 dividend fortresses that pair higher payout levels with underlying resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com