


LIXIL (TSE:5938) Hyderabad Expansion Keeps Its Undervalued Narrative In Focus
LIXIL’s India Expansion Puts Hyderabad in Focus
LIXIL (TSE:5938) is drawing fresh attention after announcing a new window manufacturing plant in Hyderabad, planned to support rising demand for TOSTEM aluminum window systems and sliding door profiles in India.
The facility, expected to start operating in 2028, is intended to lift local production in India from roughly 30% to more than 60%. That shift supports the country’s Make in India policy and gives the Housing Technology unit a more locally anchored supply chain.
LIXIL’s latest India move comes after a mixed run in the market, with the share price down 10.99% year to date and about 9.95% over 3 months, even as the 3 year total shareholder return of 22.05% points to longer term momentum building.
Scan other manufacturers that are benefiting from similar regional expansion themes with our curated list of list of solid balance sheet and fundamentals (21 results)
Bulls see the Hyderabad build as proof LIXIL is compounding its global footprint. Skeptics point to the share price drift and muted value score. Which side do today’s valuation signals lean toward?
Most Popular Narrative: 10% Undervalued
On the most followed view of LIXIL, the fair value sits at ¥1,881, which is above the last close of ¥1,688 and frames the India buildout inside a broader earnings recovery story.
The main factor that needs to go right is LIXIL successfully protecting margins by passing through over JPY 30b of higher material and fuel costs, while executing its cost efficiency measures and continuing to lift profitability in regions such as the Americas and IMEA.
Across recent periods, LIXIL has been pursuing structural reforms and cost control initiatives that have already supported higher core earnings. Continued roll out of logistics rationalization, AI-enabled process automation and plant optimization is intended to support operating margins and core earnings.
See why 0 investors see LIXIL as 10% undervalued.
Result: Fair Value of ¥1,881 (UNDERVALUED)
Still, the LIXIL story depends on two pressure points not breaking: U.S. housing softness weighing on the Americas turnaround, and raw material inflation squeezing already thin margins again.
Find out about the key risks to this LIXIL narrative.
Another View: LIXIL Looks Expensive On Earnings
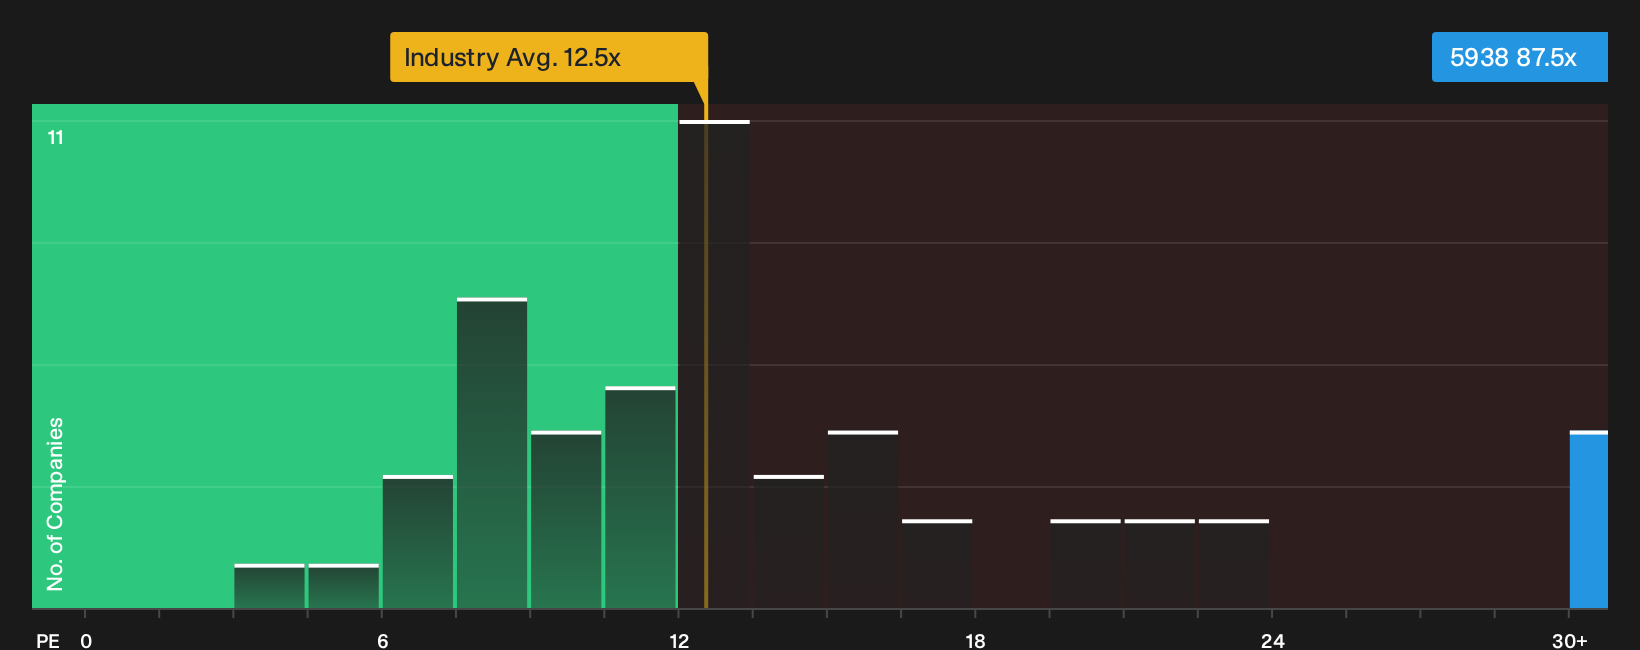
The story changes when you look at LIXIL through its P/E ratio. The stock trades on 87.5x earnings, compared with about 15x for peers and 12.5x for the wider JP Building industry. Against a fair ratio estimate of 27.3x, that gap points to meaningful valuation risk if sentiment cools.
For investors comparing price tags across similar manufacturers, these relative multiples raise a simple question: Is the market already paying tomorrow’s earnings expectations upfront, or is this premium justified by how you see the next few years unfolding for LIXIL.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on LIXIL so far. If this blend of risks and potential rewards has you on the fence, consider moving quickly and carefully weighing both sides using the full breakdown in 1 key reward and 2 important warning signs.
Looking for more LIXIL investment ideas?
If LIXIL has you thinking harder about valuation and risk, do not stop here. Fresh opportunities often sit just beyond the handful of stocks you already follow.
- Target dependable cash generators by scanning our 15 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect their balance sheets.
- Strengthen your income stream by using the 32 dividend fortresses to focus on companies offering higher yields with an eye on resilience.
- Prioritise resilience over drama and filter for steadier performers through the 21 resilient stocks with low risk scores before capital chases the next headline story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com