


Independence Realty Trust (IRT) Sets Q3 Results Date, Is It Still 23% Below Fair Value?
Independence Realty Trust (IRT) has set the date for its next catalyst. Third quarter 2026 results are scheduled to be released after the close on Monday, November 2, followed by a conference call on Tuesday morning.
Independence Realty Trust heads into this third quarter update with mixed momentum, with the share price down 13.67% over 90 days and 16.76% year to date, while the 3 year total shareholder return of 21.07% contrasts with a 1 year total shareholder return decline of 4.91%.
Scan beyond Independence Realty Trust and line up other real estate players with recent price pressure but solid fundamentals by using our curated list of list of solid balance sheet and fundamentals (25 results).
Independence Realty Trust now trades well below both intrinsic value estimates and analyst targets after this pullback. Is that discount compensation for real risk, or is the market leaning too hard on caution about this REIT’s story?
Most Popular Narrative: 23% Undervalued
On Simply Wall St’s most followed narrative, Independence Realty Trust screens as undervalued, with a fair value estimate of $19.14 against a last close of $14.65. That gap rests on a specific view of how its Sun Belt footprint and renter demand play out over time.
The tapering of new multifamily supply and a 43% year-over-year reduction in deliveries projected for IRT's Sun Belt-focused markets in 2026 positions the company for a reacceleration of rent growth and stronger occupancy as demand continues to outpace incoming inventory, which should drive future revenue and NOI growth.
Ongoing capital recycling, selling older, higher CapEx assets to acquire newer, lower CapEx communities with higher growth profiles in high-demand regions, allows IRT to enhance portfolio quality, capture operating synergies, and improve overall net margins and earnings growth potential.
See why 0 investors see Independence Realty Trust as 23% undervalued.
Result: Fair Value of $19.14 (UNDERVALUED)
Still, the narrative can break if Sun Belt oversupply continues to pressure rents or if Independence Realty Trust struggles to recycle older assets into stronger performers.
Find out about the key risks to this Independence Realty Trust narrative.
Another View: Independence Realty Trust Through The Earnings Lens
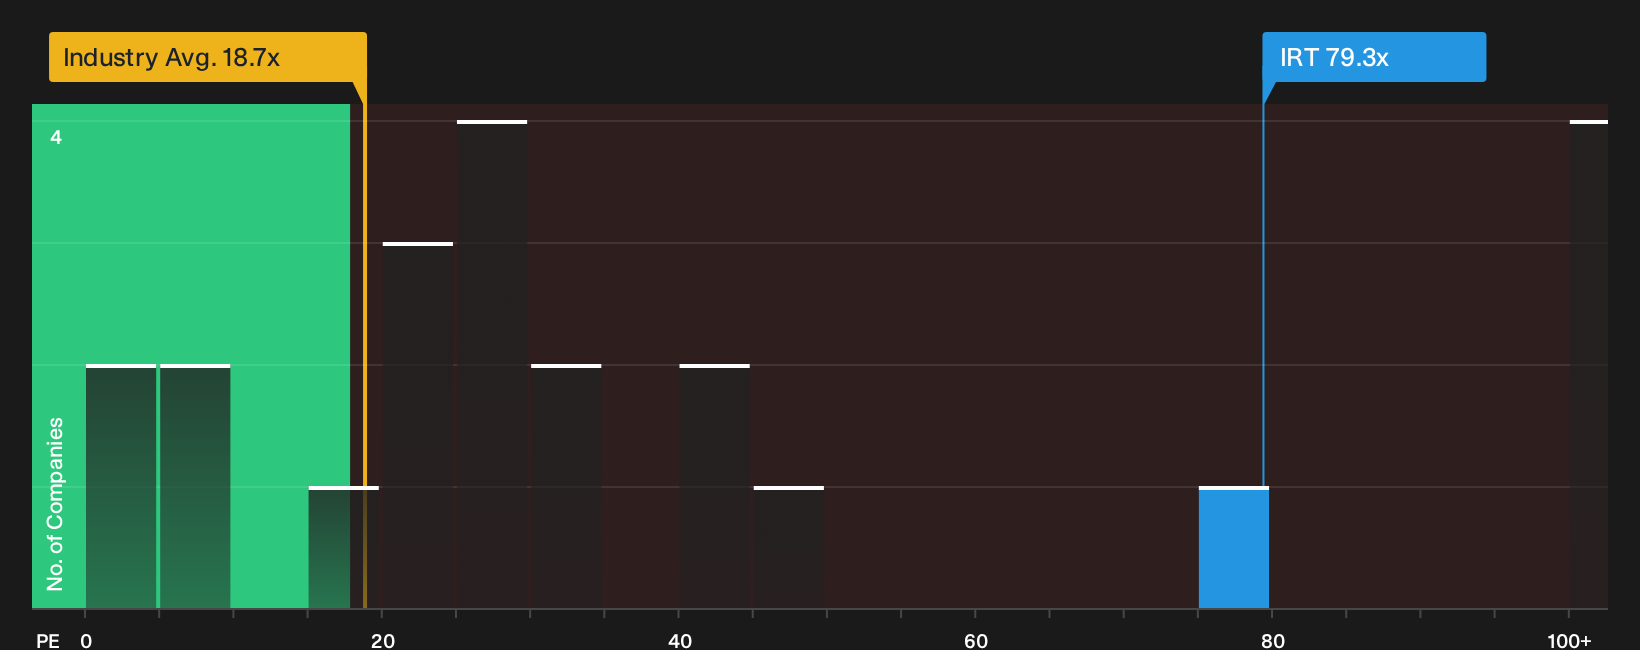
The DCF workup presents Independence Realty Trust as undervalued, while the earnings multiple points in a very different direction. The stock trades on a P/E of 79.3x, compared with 18.3x for the global residential REIT group, 32.2x for peers, and a fair ratio of 32x that the market could potentially gravitate toward over time.
That gap leaves investors weighing a discounted cash flow story against an earnings multiple that appears rich on almost every comparison. Which signal is more relevant when framing risk around IRT from this point?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Independence Realty Trust is clearly split, with risk and reward signals pulling in opposite directions, so move quickly and test the numbers against your own expectations. To see those trade offs laid out side by side, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Independence Realty Trust?
Do not stop your research at Independence Realty Trust. Broaden your watchlist with fresh ideas across quality, value, and resilience so you are not relying on a single story.
- Target resilient balance sheets and steadier fundamentals by screening for companies on our 32 resilient stocks with low risk scores.
- Hunt for quality at a discount by focusing on opportunities flagged in the 32 high quality undervalued stocks.
- Prioritise income potential by zeroing in on higher yielding candidates highlighted through the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com