


Garmin (GRMN) Has The Market Watching, What Is Behind The Attention?
Garmin (GRMN) has packed several product and aviation milestones into October 2026, from a third generation of MARQ luxury tool watches to fresh Autoland and G1000 retrofit achievements that keep the stock on investor watchlists.
Those October product launches and aviation milestones have come as Garmin’s share price has climbed 11.45% over the past 90 days and 38.17% year to date, while the 3 year total shareholder return of 180.24% points to strong longer term momentum that investors are now reassessing against the current price of $279.72.
Spot similar momentum across other premium hardware and aviation-focused players by scanning our curated list of 20 high quality undiscovered gems that are aligned with Garmin’s blend of wearables, avionics and community-driven products.After that kind of run, Garmin now forces a simple question. Is the recent rally just catching up to what the business already delivered, or are investors paying today for gains that used to be cheaper?
Most Popular Narrative: 7% Undervalued
Garmin’s most followed valuation story pegs fair value at $302, slightly above the last close at $279.72. This frames the recent rally as still leaving some upside according to that narrative.
The launch of the Garmin Connect+ premium service, which offers AI based health and fitness insights, is likely to boost subscription based revenue growth and improve overall margins through higher margin services.
The acquisitions of TrainingPeaks and TrainHeroic, which add endurance and strength training platforms around Garmin wearables, are expected to deepen the service ecosystem and create more recurring revenue streams that can support gross margin and operating margin over time.
See why 47 investors see Garmin as 7% undervalued.
Result: Fair Value of $302 (UNDERVALUED)
Still, the Garmin story carries pressure points, including softer Outdoor revenue trends and management flagging a likely return to operating losses in Auto OEM.
Find out about the key risks to this Garmin narrative.
Another View: Garmin Through The P/E Lens
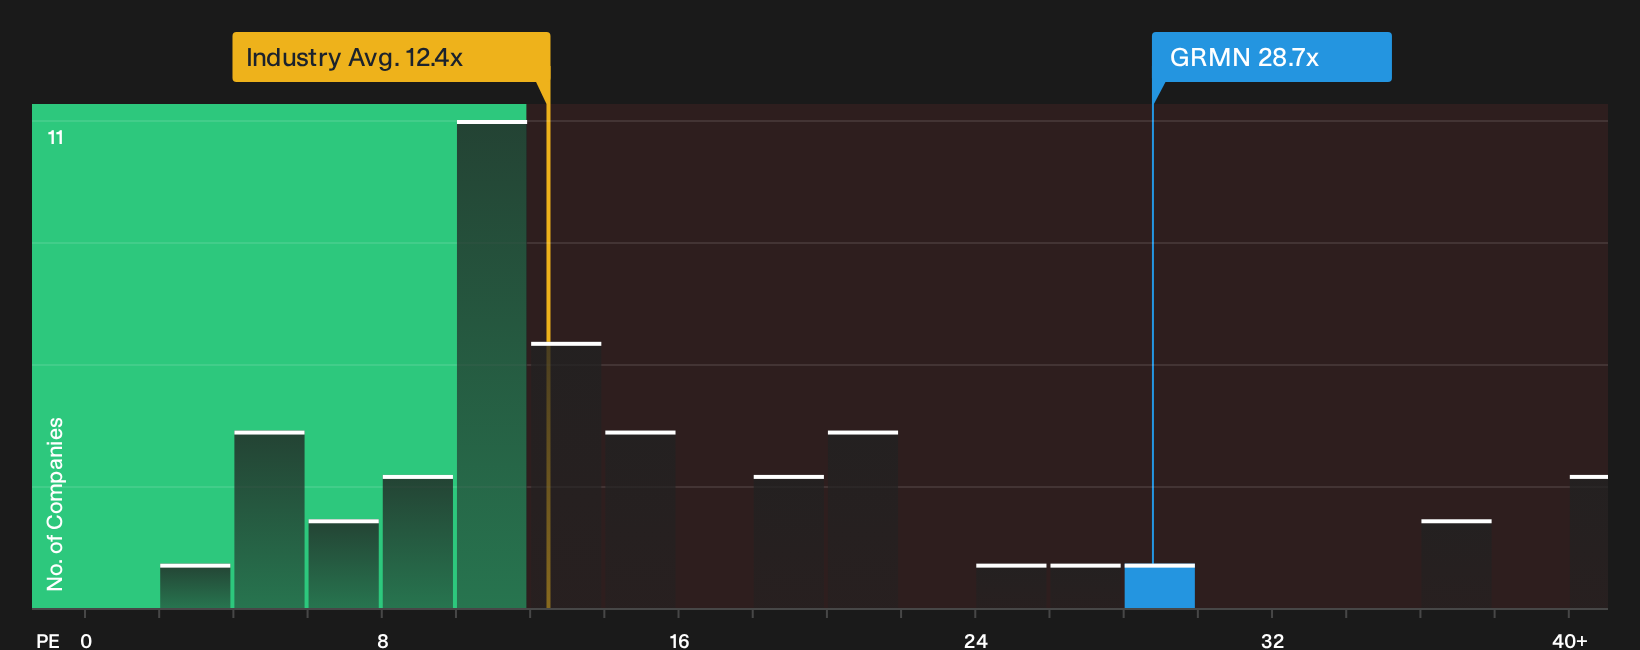
Analyst models and the SWS DCF work up to a fair value near $302 for Garmin, which frames today’s $279.72 price as 16.3% below an internal estimate of fair value and below an implied future cash flow value of $334.26. Yet the current 28.7x P/E is well above the fair ratio of 22.3x, the US Consumer Durables average of 12.4x, and a 24.3x peer average. How comfortable are you paying a richer multiple even if cash flow maths points to upside?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Garmin is mixed, which is exactly when independent thinking matters most. Move quickly, get familiar with both sides of the argument, then weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Garmin?
If Garmin has you rethinking what belongs in your portfolio, do not stop at a single ticker. Cast a wider net now so genuine opportunities do not slip past.
- Target resilient cash generators that still look overlooked by screening for 32 high quality undervalued stocks with robust earnings and balance sheets.
- Strengthen your income stream by zeroing in on companies in the 7 dividend fortresses that pair higher yields with consistent payout histories.
- Dial back portfolio risk by focusing on sturdier businesses surfaced through the 32 resilient stocks with low risk scores before the crowd catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com