


CoreWeave Stock Is Sinking Again Today. Here's Why.
CoreWeave (CRWV) shares came under pressure on Oct. 14 as a selloff in its corporate bonds heightened concerns about financing its ambitious artificial intelligence (AI) infrastructure expansion. Yields on the AI infrastructure company’s bonds maturing in 2032 climbed to about 15%, drawing attention to the risks surrounding its debt-funded growth.
Billionaire Elon Musk amplified those concerns with a one-word social media response: “Yikes.” CoreWeave stock has continued moving downward on Oct. 15 and is now trading at less than half its year-to-date high.
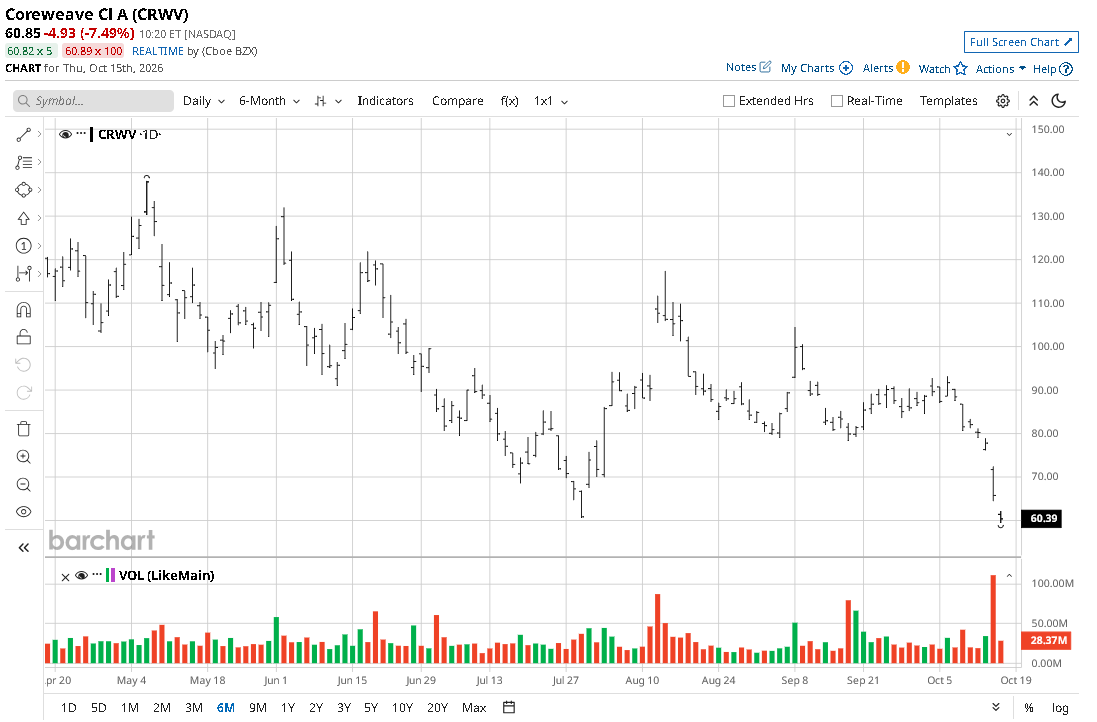
What Triggered the Selloff in CoreWeave Stock
The immediate catalyst behind this was a post from famed investor Chamath Palihapitiya highlighting the sharp increase in the firm’s bond yields, which Musk subsequently amplified.
CRWV shares slipped on the underlying concern that investors are demanding substantially greater compensation for lending to the AI cloud provider.
A higher secondary-market yield doesn’t automatically increase interest payments on existing fixed-rate bonds. But it signals potentially more expensive financing when CoreWeave raises additional debt or refinances borrowings. That matters significantly for a business funding costly data centers and computing equipment.
A hotter-than-expected U.S. inflation report compounded the pressure on Wednesday, intensifying concerns about borrowing costs across the capital-intensive artificial intelligence sector and adding to CRWV’s vulnerability.
Are CRWV Shares Still Worth Owning?
For long-term investors, CoreWeave shares nonetheless retain a credible growth case.
The company’s latest quarterly results showed revenue more than doubling to $2.575 billion, with about $104 billion in backlog as of June 30, excluding more than $25 billion in commitments in Q3.
Those figures demonstrate “substantial demand.” However, quarterly net interest expense reached $640 million, while CRWV’s net loss totaled $626 million.
Investors should also note that the backlog depends on meeting delivery and service requirements; it’s not cash already collected.
That combination makes CoreWeave somewhat of a speculative holding. For investors assessing the selloff, the strongest argument for caution is that exceptional sales growth has yet to overcome the financial burden of delivering it.
What’s the Consensus Rating on CoreWeave?
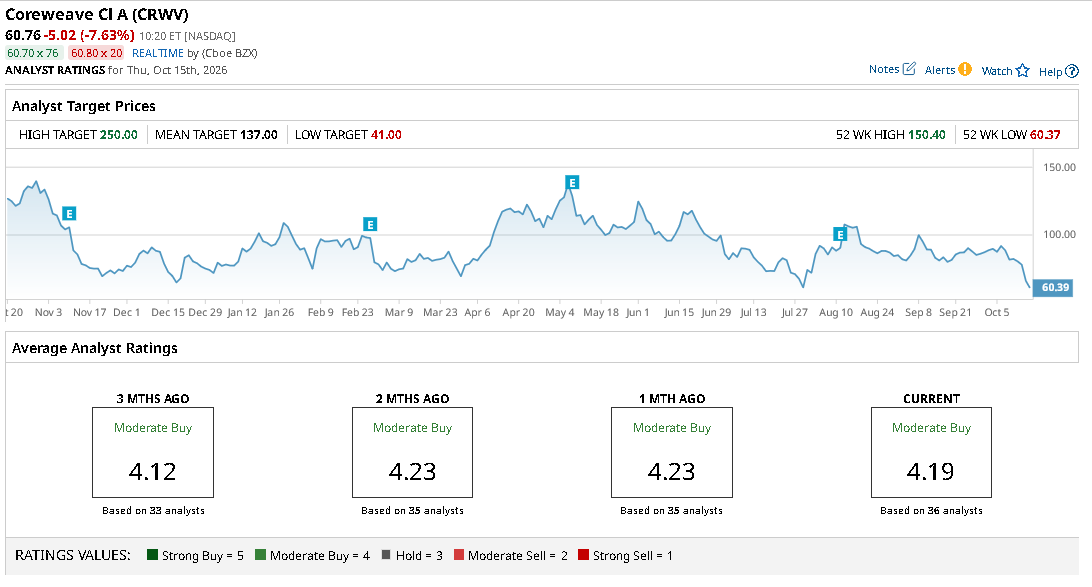
Wall Street analysts nonetheless remain bullish as ever on CRWV stock heading into 2027.
The consensus rating on CoreWeave sits at “Moderate Buy” currently, with the mean price target of about $137 indicating potential for over 100% upside from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.