


Did Visible Alpha Data Just Shift S&P Global's (SPGI) Investment Narrative?
- S&P Global recently added Visible Alpha's consensus data to the S&P Global AI Data Portal, giving clients API driven access to detailed estimates, financial line items and segment level forecasts for thousands of companies.
- This move plugs granular sell side models directly into MCP enabled AI workflows. It could reshape how research teams prepare earnings materials, run comps and benchmark investor relations activity.
- Next, the focus turns to how S&P Global's investment narrative around AI driven workflows could shift as Visible Alpha joins its AI Data Portal.
S&P Global Investment Narrative Recap
Owning S&P Global means believing this business can keep turning its data, benchmarks and workflows into steady, high margin growth across Ratings, Indices, Market Intelligence and Energy. The big swing factor in the near term still sits in Ratings, where activity depends on refinancing appetite around the 8 trillion dollar maturity wall and broader deal volumes.
The Visible Alpha integration helps the S&P Global AI Data Portal story, but it does not change that the main near term catalyst remains issuance trends and billed activity in Ratings. The biggest risk is a reset in what investors are willing to pay if organic growth or margins fall short of the profile implied in current expectations.
The Capital IQ Pro upgrade earlier in October looks closely tied to the Visible Alpha launch. ChatIQ, Deterministic Retrieval and, later, Adaptive Retrieval all point in the same direction, which is deeper AI centric workflows and heavier use of S&P Global content through MCP compatible channels.
For you as a shareholder, the test is execution. Strong AI tools and richer datasets only matter if they translate into higher enterprise data usage, better cross selling into private markets and energy products, and stickier customers who are less sensitive to market cycles that affect Ratings transaction volumes.
S&P Global Consensus Assumptions Around AI Workflows
Analysts currently frame the S&P Global story around modest top line expansion, fatter profit margins and more earnings per share over the next several years, with AI enabled tools like the Visible Alpha integration acting as one of several levers rather than the only driver. The investment case that gets airtime today leans on revenue compounding at 2.3% a year, profit margins rising from 30.5% to 34.8% and earnings climbing from US$4.9b to US$6.0b by 2029.
Those earnings expectations imply roughly a US$1.1b increase in profit over the forecast window, which is a sizeable absolute move when you remember the business already generates multi billion dollar income. For an AI focused reader, that sets a rough hurdle for what new datasets, retrieval tools and MCP ready workflows need to support in terms of extra customer spend and operating efficiency across Ratings, Market Intelligence, Indices and Energy.
On top of that, consensus assumes the share count shrinks by around 2.64% a year over the next 3 years, which helps earnings per share grow faster than total profit. That buyback effect matters for anyone trying to judge whether AI data products like the S&P Global AI Data Portal simply protect the current earnings base or contribute meaningfully to EPS growth as the overall pie gets carved up across fewer shares.
The current narrative also leans on a required P/E of 29.8x in 2029 if earnings land at US$6.0b, up from about 24.2x today, with analysts pointing out that this multiple still sits below the 39.6x level quoted for the wider US Capital Markets industry. For you, the question is whether AI heavy workflows and deeper integration into client systems justify that richer multiple or whether these tools are now table stakes across data providers, which could cap how much of a premium investors are willing to pay.
S&P Global's narrative projects US$17.3b revenue and US$6.0b earnings by 2029. This rests on 2.3% yearly revenue growth and about US$1.1b earnings increase from US$4.9b today.
How Valuation Ties Back To The S&P Global AI Story
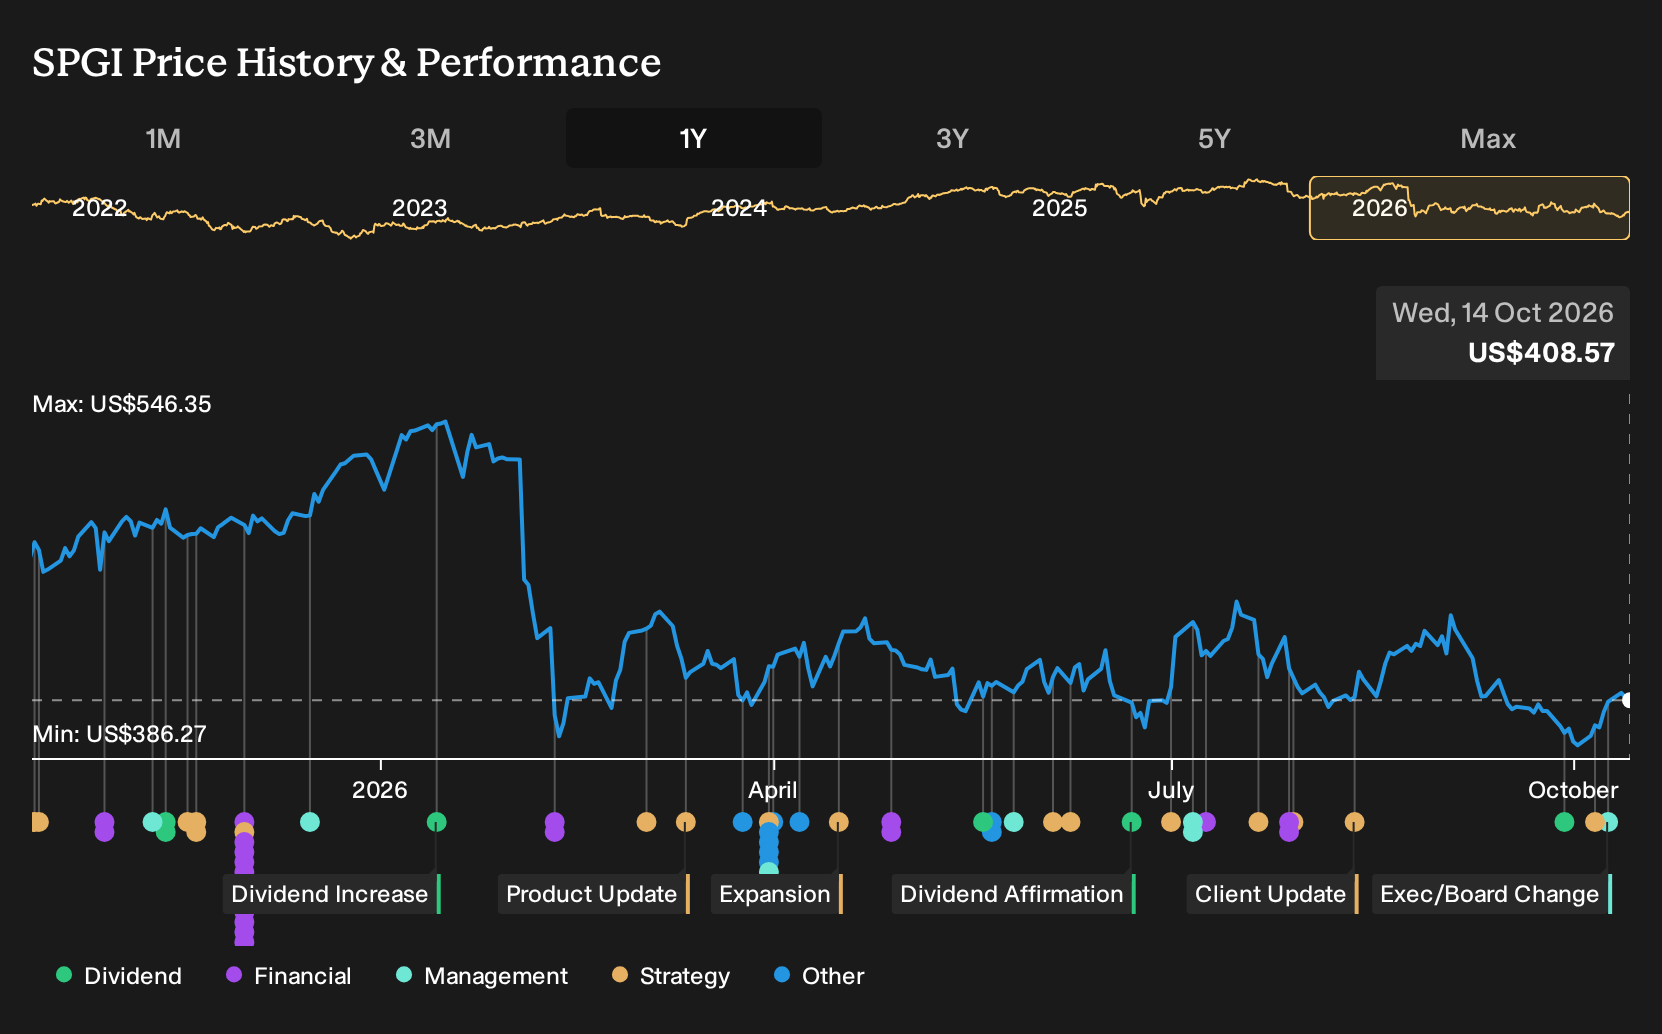
Price targets around US$520.30 per share imply that some analysts see room above the current US$404.47 price if revenue, profit margins and capital allocation all line up with their playbook. In that playbook, S&P Global reaches about US$17.3b of sales and US$6.0b of earnings in 2029 and trades on a 29.8x P/E, using a discount rate close to 8.1% to bring those cash flows back to today.
Under that lens, tools like the AI Data Portal and the Visible Alpha integration are not just product upgrades. They are part of the mechanism meant to support mid single digit organic revenue growth, higher profitability and a valuation that assumes clients keep deepening their dependency on S&P Global datasets and workflow tools across issuance work, portfolio analysis and investor relations.
For your own framework, it helps to separate the moving parts. One bucket is operational, where you judge how realistic it is for AI ready data, MCP channels and private markets content to support 2.3% annual revenue growth and higher margins while issuance cycles in Ratings move up and down. The other bucket is market based, where you consider whether a 29.8x P/E on 2029 earnings feels reasonable if more AI data infrastructure competitors capture a slice of the same spend.
The spread between the present share price and the consensus target, currently about 22.3% higher at that US$520.30 level, simply reflects those embedded assumptions rather than any guarantee. Your task is to pressure test the idea that richer AI workflows increase enterprise data usage, help cross selling into private markets and energy tools and make S&P Global clients stickier through a full credit cycle so that the earnings and valuation pieces of the story hold together.
Uncover how S&P Global's fair value indicates a 27% potential upside to its current price that could narrow quickly if AI execution aligns with those earnings assumptions.
Exploring Other Perspectives
The Simply Wall St Community adds 12 retail perspectives, with fair value views stretching from about US$377 to the US$520.30 high that echoes some analyst targets. That spread meets fresh catalysts like S&P Global's AI Data Portal and Visible Alpha rollout, while issuance reliant Ratings revenue keeps the risk of setbacks in front of you.
Explore 11 other S&P Global fair value estimates, including one that suggests up to 8% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your S&P Global research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for S&P Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate S&P Global's overall financial health at a glance.
Looking For More Investment Ideas Beyond S&P Global?
If you want to broaden your watchlist beyond S&P Global, the Simply Wall St Screener can help you filter the market into focused shortlists that match your risk tolerance, income needs and return goals.
- For investors who want growth potential without stretching on quality, consider a shortlist built around 20 high quality undiscovered gems that already show strong fundamentals.
- If resilience and capital preservation sit higher on your list, you might prefer companies screened from a 32 resilient stocks with low risk scores that keeps an eye on stability first.
- Income focused readers can zero in on cash generating businesses by reviewing a 7 dividend fortresses that targets higher yielding payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com