


Is Golar LNG (GLNG) Fairly Valued Following Its Grace Dahlia FLNG Deal?
Golar LNG (GLNG) just moved to expand its floating LNG fleet, agreeing to buy the 2013-built Grace Dahlia carrier from NYK Line for conversion into its fourth FLNG unit.
Despite the Grace Dahlia deal pointing to future FLNG capacity, recent trading has been weak, with a 1-month share price return down 10.6% and a 7-day slide of 6.3%, even as the year-to-date share price return is up 21.3%. Over longer horizons the picture looks different, with total shareholder return of 20.3% over one year and over 3x over five years, which indicates long-term momentum, while near-term moves suggest some investors are reassessing execution risk and funding needs around Golar LNG’s growth plans.
Capitalize on the momentum around Golar LNG's FLNG expansion and scan a curated set of infrastructure focused plays with the 43 power grid technology and infrastructure stocks.Golar LNG now trades at a steep discount to both analyst targets and an implied fair value, even as the Grace Dahlia move raises questions about execution risk and funding. Is the market being prudent or overly cautious?
Most Popular Narrative: 7% Undervalued
On the most followed narrative, Golar LNG screens as modestly undervalued, with a fair value of about $49.71 against the recent $46.03 close and a 7.24% discount rate framing that view. That gap is not huge, yet it rests on a very specific read of FLNG growth, Argentina exposure and long term contract coverage.
The plan to order a fourth FLNG unit in 2026 and potentially move toward a larger multi-unit platform depends on continued access to attractive long-lead items, shipyard capacity and financing. Any cost inflation or delays in conversions and yard schedules could erode the targeted 5x to 6x CapEx to EBITDA economics and compress future margins and cash flows.
See why 0 investors see Golar LNG as 7% undervalued.
Result: Fair Value of $49.71 (UNDERVALUED)
Still, the narrative can break if Argentina related infrastructure underdelivers, or if new FLNG charters land on tighter terms than analysts currently factor in.
Find out about the key risks to this Golar LNG narrative.
Another View: What Golar LNG’s P/E Is Telling You
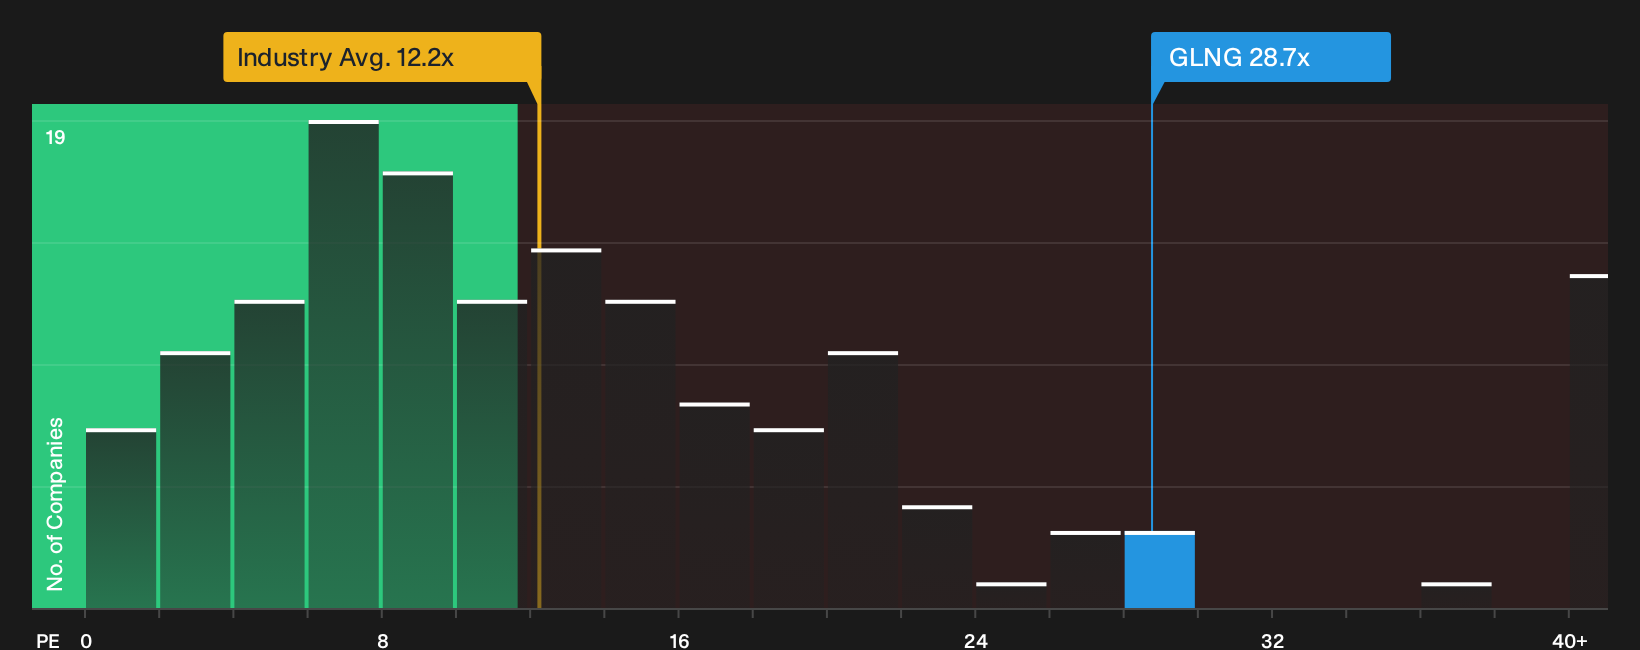
The fair value narrative paints Golar LNG as modestly undervalued, yet the market multiple sends a different message. The shares trade on a P/E of 28.7x, which is far above the US Oil and Gas industry at 12.3x and the peer average of 16.1x, and only slightly below the fair ratio of 29.5x. That mix points to a stock already priced for strong execution. It also raises the question of how much room is left if anything slips on FLNG delivery or Argentina economics.
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Golar LNG’s story so far. Move quickly from reading to testing the numbers yourself by weighing 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Golar LNG?
Do not stop with one stock. Use structured screens to surface other opportunities that fit your style, then pressure test each idea before committing capital.
- Target value upside by reviewing companies that currently rank as 32 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by focusing on a list of solid balance sheet and fundamentals (25 results).
- Hunt for future market leaders before the crowd notices by scanning our 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com