


Caught Out By NIO's 50% Fall? Here's What The Bears Saw
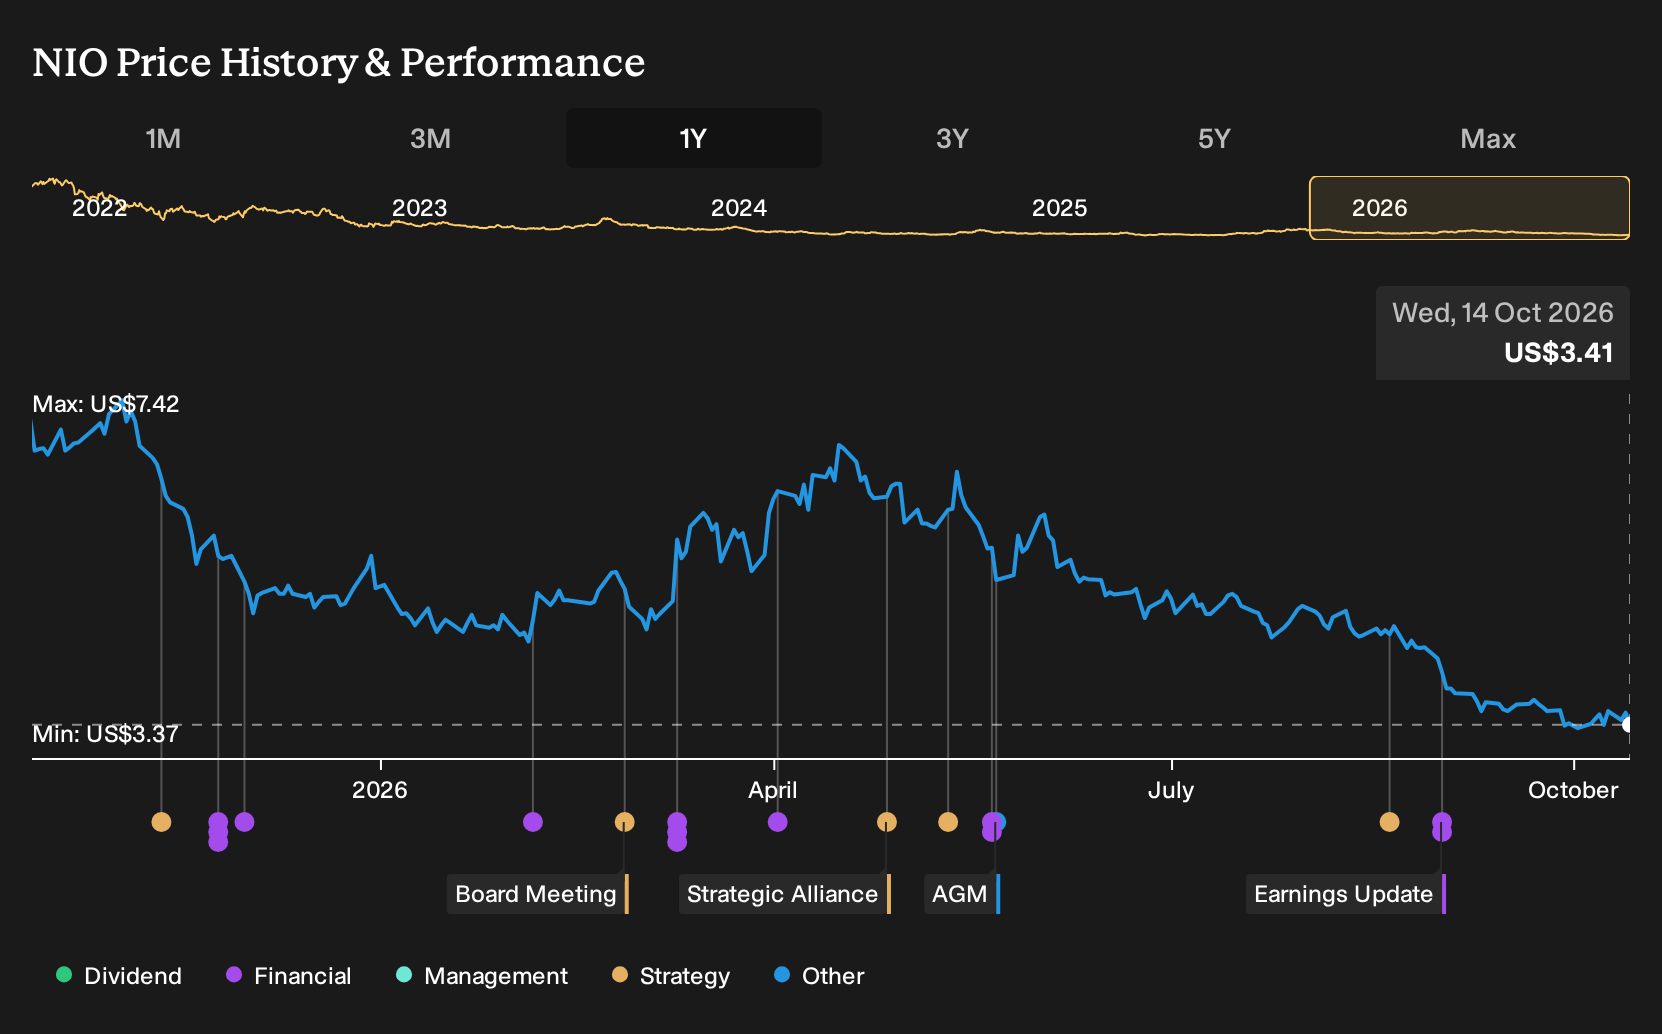
If you had looked at NIO in October 2025, with analysts split between a bullish US$9.0 case and a far more cautious US$3.0 view, it might have felt like just another high-risk EV story. Holding NIO over the past year would have meant a 50.0% loss, including dividends. If that decline felt surprising, which early clues in the assumptions on growth, margins, funding needs, or China concentration were already on record for you to question?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
NIO has already moved. Pinpoint other ways to investigate the theme among 43 power grid technology and infrastructure stocks.
The Two NIO Stories Investors Had To Weigh
The shares cost US$6.8 at the start of the period, and NIO sat between two sharply different stories that both sounded plausible.
On the bullish side, a Fair Value of US$8.1 rested on faith in battery swaps, digital services, and a delivery ramp that assumed revenue could grow 44.4% a year with profit margins eventually moving from a loss toward 5.0%.
The bearish Narrative pointed to a Fair Value of US$3. It leaned on concerns that higher tariffs, excess EV capacity, and funding costs might cap revenue growth around 13.6% and keep profitability uncertain.
What The Results Changed For The NIO Thesis
NIO’s Q2 2026 report showed revenue of CN¥32,136.9m and a net loss of CN¥721.6m, with net margin moving from a loss of 27.0% in Q2 2025 to a loss of 2.2%. That shift toward breakeven supported the bullish margin and efficiency story, while the continued losses and ongoing funding needs kept the bearish concerns alive. The evidence cut both ways.
The lesson for any stock is simple. When a thesis leans on margin recovery, track net margin and absolute profit side by side, and test whether each quarter actually closes the gap to the profit level the story assumes.
What NIO’s Lower Price Asks You To Believe
NIO trades at US$3.41 today, and the selected Narrative’s Fair Value now sits above that quote. The argument focuses on premium positioning, in-house technology, and infrastructure as the reasons the business can still justify that higher figure.
After a 50.0% loss over the past year, a buyer now has to judge whether sustained delivery growth, premium margins, and recurring services can outweigh softer demand and intense competition.
"Operational improvements in R&D and SG&A efficiency, underpinned by the Cell Business Unit mechanism, are leading to substantial reductions in fixed costs and improved operating leverage, providing a clear path to breakeven and eventually to positive net earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond NIO’s EV Story
If NIO keeps you focused on premium EV branding, look one step sideways. Your thesis does not need to stop at cars.
Software heavy vehicles also need capable driving intelligence. That points to chips, models, and code built for constantly changing roads.
Another Chinese automaker is building its own stack here. It develops in house AI hardware, autonomous driving systems, and smart cockpits.
This rival is also exploring overseas markets and non vehicle robots. If that approach gains traction, the whole idea of a car company could look very different.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 95% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com