


Symrise (XTRA:SY1) As Asia Push And Sector Optimism Put Valuation Back In Focus
Symrise (XTRA:SY1) drew fresh attention after Givaudan’s stronger-than-expected third quarter lifted sector sentiment, while Symrise’s new scent creative center in Singapore highlighted its focus on Asia’s fragrance and taste demand.
The upbeat sector mood has been reflected in Symrise’s own chart. A 7 day share price return of 6.52% and a 30 day gain of 9.90% have helped push the stock to €96.98. The year to date share price return of 41.87% and 1 year total shareholder return of 30.22% point to momentum building over a longer stretch, despite a 5 year total shareholder return that declined 10.67%.
Spot similar momentum and Asia-focused expansion stories by scanning our curated list of 613 high quality undiscovered gems while Symrise rides this sector tailwind.After a sharp rerating and a fresh push into Asia, Symrise now poses a simple question to new investors: Does the current price still offer enough upside for the risk you take?
Most Popular Narrative: 4% Undervalued
On the most followed view, Symrise is worth €101.30 on a fair value basis compared with the latest close at €96.98. This frames today’s rally as only partially closing that gap.
Symrise is executing a multi-year transformation focused on operational efficiency, portfolio optimization, and disciplined cost management, which is already yielding substantial margin improvements (notably, a gross margin increase of 250 bps and an EBITDA margin uplift), laying the groundwork for structurally higher net margins and improved earnings compounding.
See why 17 investors see Symrise as 4% undervalued.
Result: Fair Value of €101.30 (UNDERVALUED)
Still, that 5 year shareholder return that declined 10.67% and management’s lower 2025 organic growth guidance remind you how quickly this Symrise narrative could be challenged.
Find out about the key risks to this Symrise narrative.
Another View: Symrise Through The P/E Lens
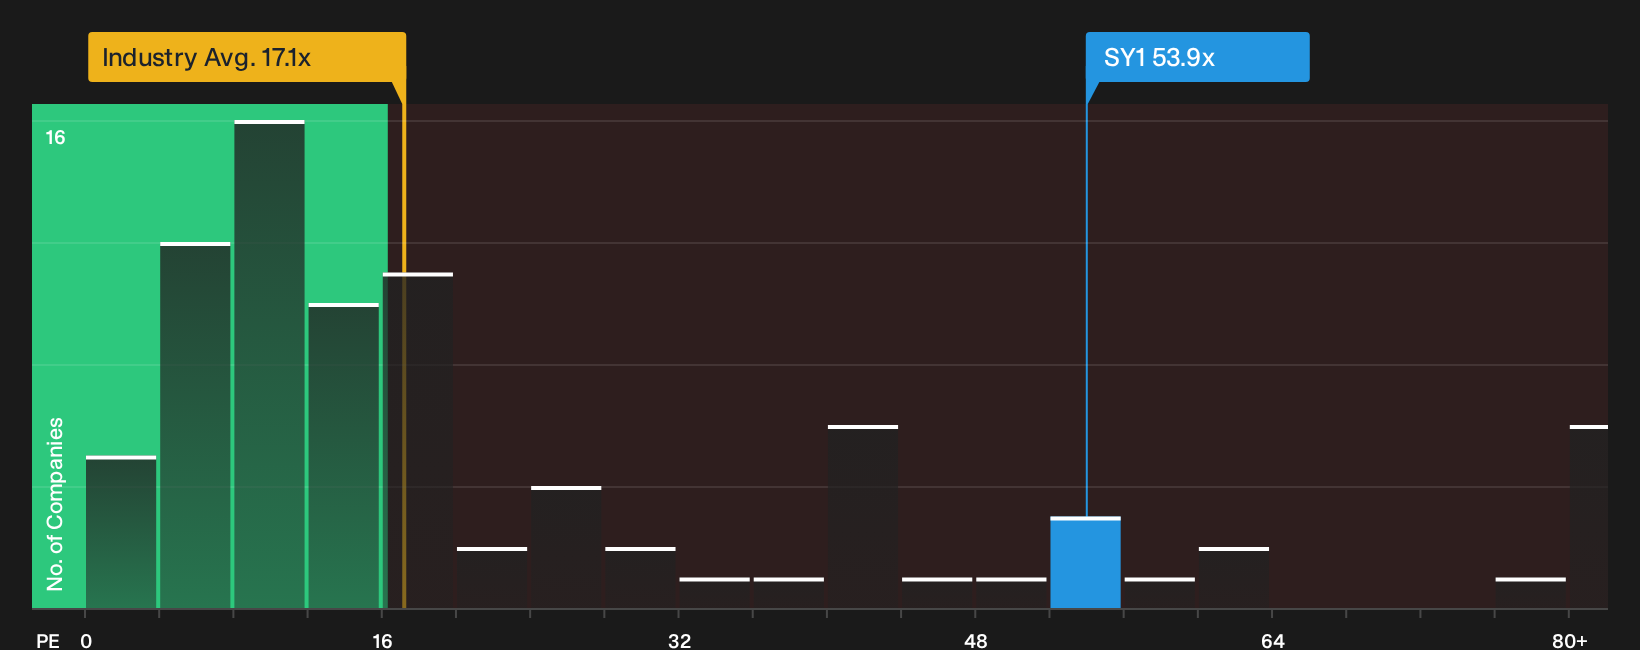
The fair value narrative for Symrise paints a modest 4% upside to €101.30, yet the current P/E tells a very different story. At 53.9x earnings, the stock trades at more than triple the European Chemicals average of 17.1x and well above its own fair ratio of 23.6x.
That gap suggests investors are already paying a hefty premium for Symrise compared with both peers and where the fair ratio implies the multiple could settle. This increases the risk that future disappointment in earnings or sentiment would hurt returns more quickly. The key question is whether you believe the underlying earnings story is strong enough to keep that premium in place or even stretch it further.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Symrise debate feels finely balanced, take that as a signal to act quickly. Review both the upside and the red flags, then weigh the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Symrise?
Do not stop your research with Symrise alone. The broader market holds a range of opportunities that fit different risk levels, income needs, and growth preferences.
- Target resilient income by reviewing companies we flag as potential yield strongholds through the 217 dividend fortresses screened list.
- Hunt for quality at a discount by reviewing the hand picked 199 high quality undervalued stocks that score well on both fundamentals and pricing.
- Dial back risk without stepping away from equities by focusing on the 222 resilient stocks with low risk scores curated for more stable balance sheets and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com