


Is Valero Energy (VLO) Undervalued After Analysts Upgraded Its Refining Outlook?
Refining tailwinds are back in focus for Valero Energy (VLO) after fresh research highlighted tight global capacity, firm fuel demand, and analyst upgrades to the company’s earnings outlook, which together have sharpened investor attention.
Valero Energy’s recent run has been intense, with the share price up 20.06% over the past month and 53.13% over 90 days. This has contributed to a 178.13% year to date share price return and a 1-year total shareholder return of 191.67%, together signaling powerful momentum building behind the refining story.
Surface other refiner opportunities riding similar fuel demand and capacity trends by scanning our curated list of 43 power grid technology and infrastructure stocks.For Valero Energy, that surge could reflect genuine confidence in its refining and renewable fuels platform, or it could simply mark a sharp swing in sentiment. The valuation now needs a closer look.
Most Popular Narrative: 2% Undervalued
Valero Energy’s strongest supporters see the current $459.78 share price sitting slightly below their $467 fair value anchor, which puts the recent surge within a framework built on heavier crude optionality, margin work, and capital returns.
Shorter cycle optimization projects planned for 2026, focused on crude and product optionality in refining plus efficiency and rate expansion in ethanol plants, are explicitly targeted at raising the earnings capacity of the existing asset base. This directly links to future revenue resilience, operating margins and return on invested capital.
See why 5 investors see Valero Energy as 2% undervalued.
On this narrative, modeled revenue growth, firmer profit margins, and a 7.24% discount rate combine to support a fair value of $467 for Valero Energy, only slightly above where the stock last closed. The gap is narrow, yet it highlights how much weight this framework puts on refining throughput, heavy crude discounts, and the renewal of the buyback program in sustaining earnings power over time.
Result: Fair Value of $467 (ABOUT RIGHT)
Still, the bullish Valero Energy story can be knocked off course if refining utilization stays elevated and heavy crude discounts narrow faster than analysts currently build into their models.
Find out about the key risks to this Valero Energy narrative.
Another View: Valero Energy Through The Earnings Multiple Lens
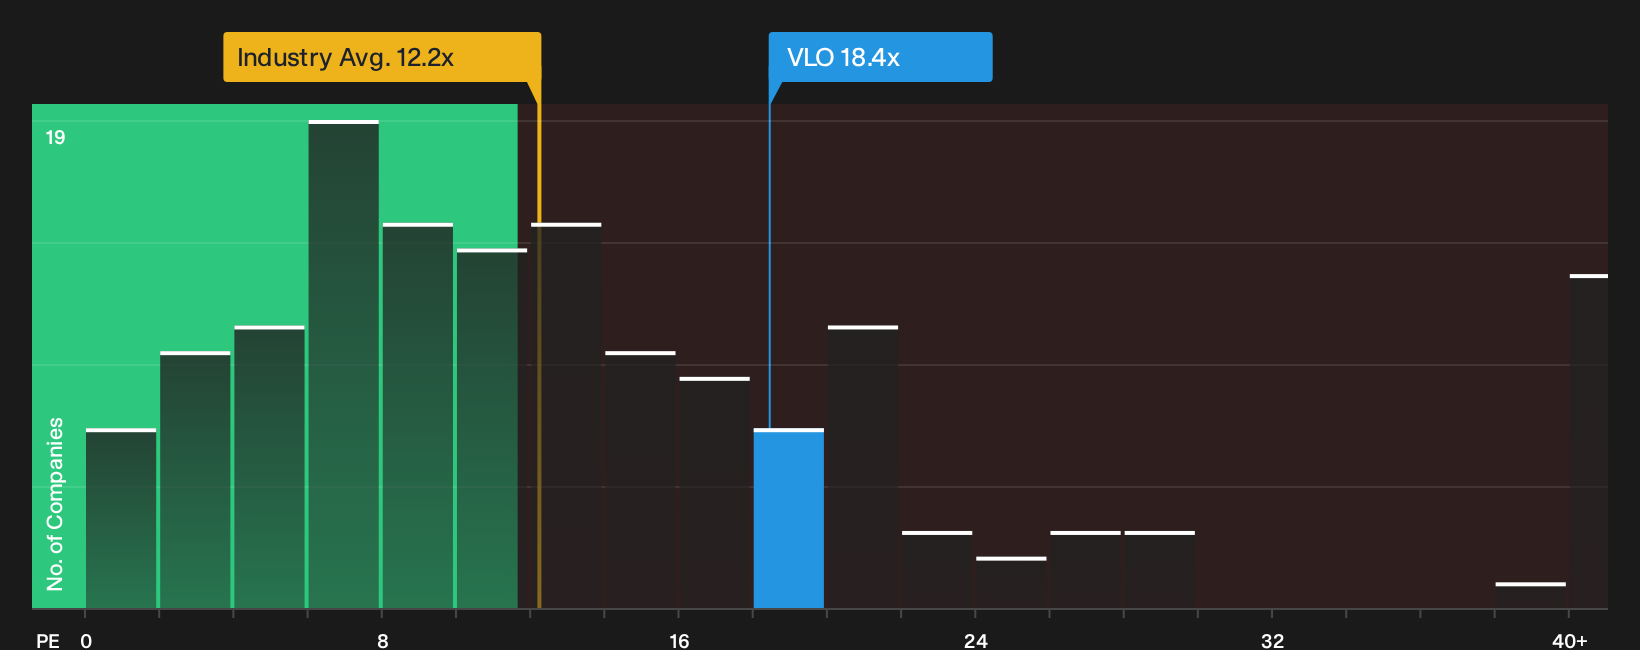
The story around Valero Energy looks very different when price is compared to earnings rather than to that $467 fair value anchor. The stock trades on a P/E of 18.4x, which is higher than the US Oil and Gas industry at 12.2x and above the peer average of 13.1x.
Simply Wall St's fair ratio for Valero Energy is 13x. That is well below the current 18.4x, which suggests the market is paying a premium for this refiner and leaves less room for disappointment if refining margins or buybacks soften.
For anyone weighing these trade offs, the real question is which story feels more fragile: the optimistic fair value model, or the richer than average earnings multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
It may be difficult to determine whether optimism or caution carries more weight in the Valero Energy story at this point. Consider reviewing the underlying data promptly, including the 1 key reward and 1 important warning sign.
Looking for more Valero Energy style investment ideas?
If you want to stress test your view on Valero Energy and avoid leaving good ideas on the table, put a few contrasting screeners to work right now.
- Target stronger pricing power by scanning a focused set of companies that trade below what their fundamentals imply through our 32 high quality undervalued stocks.
- Prioritize resilience by checking a curated list of solid balance sheet and fundamentals (25 results) that can help you avoid fragile business models when conditions tighten.
- Stretch your opportunity set by hunting for future leaders buried in plain sight using a 20 high quality undiscovered gems before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com