


When Will FreeCast, Inc. (NASDAQ:CAST) Breakeven?
FreeCast, Inc. (NASDAQ:CAST) is possibly approaching a major achievement in its business, so we would like to shine some light on the company. FreeCast, Inc. develops and markets an interactive digital media guide that facilitates access to a virtual library of entertainment media in the United States. The US$57m market-cap company announced a latest loss of US$24m on 30 June 2026 for its most recent financial year result. The most pressing concern for investors is FreeCast's path to profitability – when will it breakeven? In this article, we will touch on the expectations for the company's growth and when analysts expect it to become profitable.
Expectations from some of the American Entertainment analysts is that FreeCast is on the verge of breakeven. They anticipate the company to incur a final loss in 2027, before generating positive profits of US$6.0m in 2028. So, the company is predicted to breakeven approximately 2 years from now. In order to meet this breakeven date, we calculated the rate at which the company must grow year-on-year. It turns out an average annual growth rate of 99% is expected, which is extremely buoyant. Should the business grow at a slower rate, it will become profitable at a later date than expected.
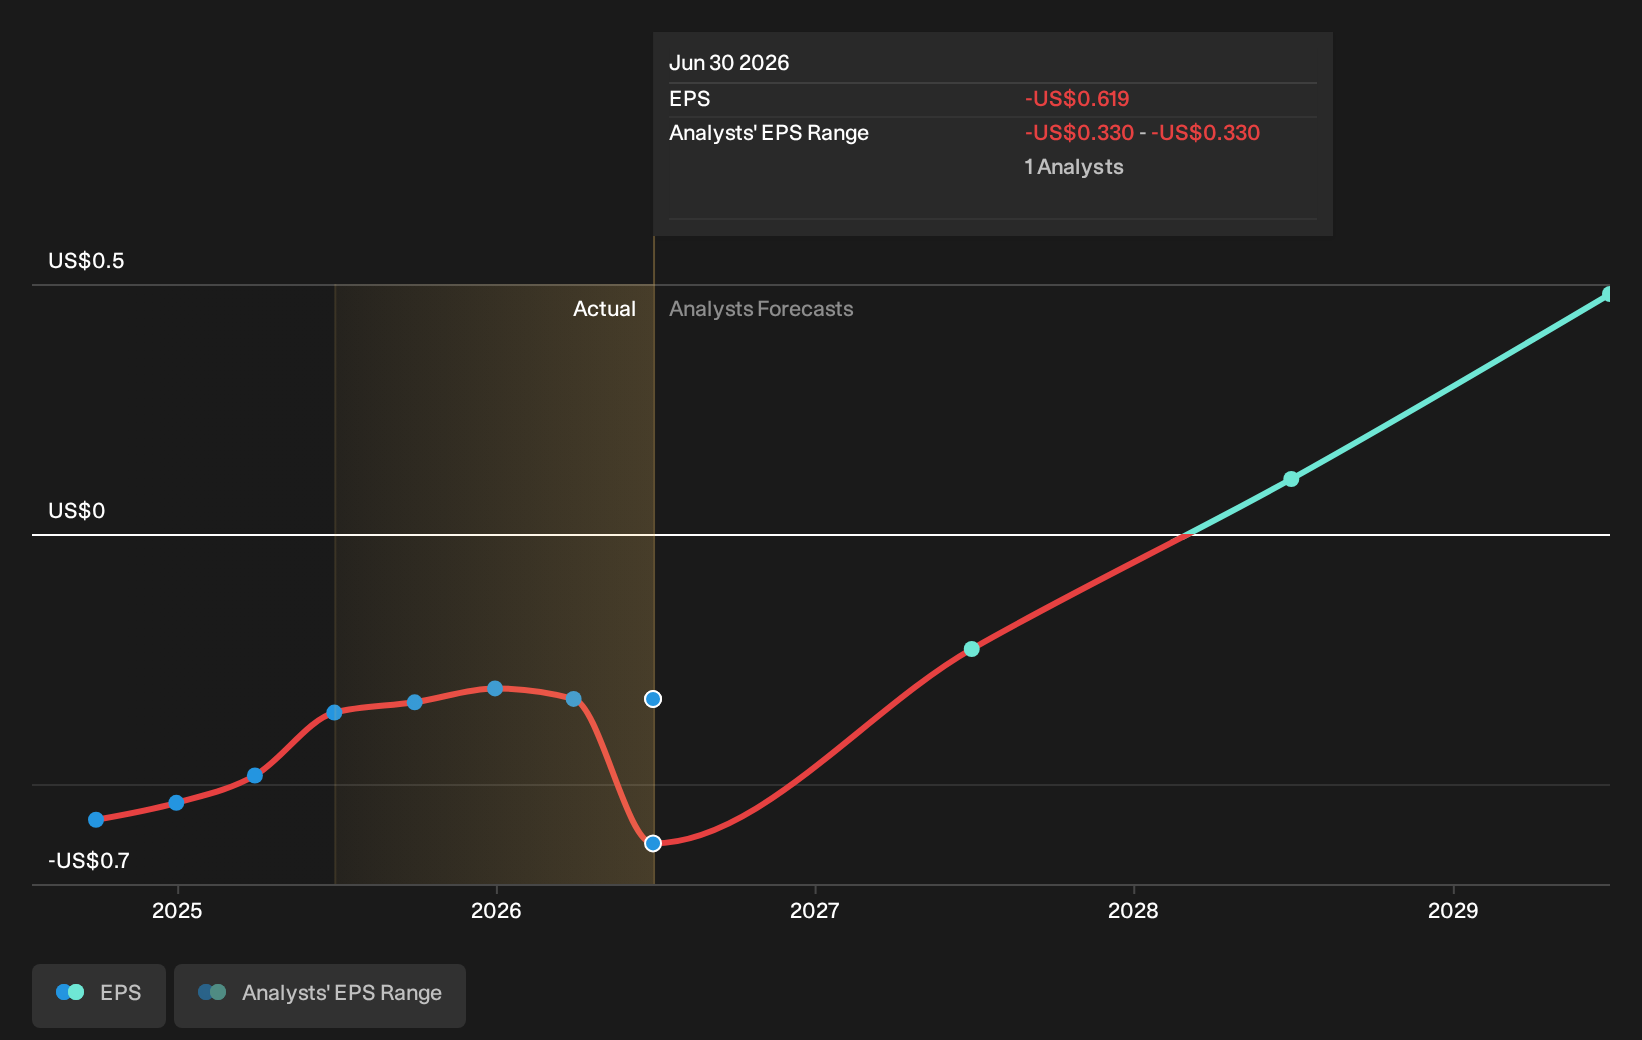
Given this is a high-level overview, we won’t go into details of FreeCast's upcoming projects, but, take into account that typically a high forecast growth rate is not unusual for a company that is currently undergoing an investment period.
Check out our latest analysis for FreeCast
Before we wrap up, there’s one issue worth mentioning. FreeCast currently has a debt-to-equity ratio of 168%. Typically, debt shouldn’t exceed 40% of your equity, and the company has considerably exceeded this. Note that a higher debt obligation increases the risk around investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on FreeCast, so if you are interested in understanding the company at a deeper level, take a look at FreeCast's company page on Simply Wall St. We've also put together a list of important aspects you should look at:
- Valuation: What is FreeCast worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether FreeCast is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on FreeCast’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.