


How New FSRU Contracts At Seatrium (SGX:5E2) Have Changed Its Investment Story
- Seatrium reported two fresh Floating Storage Regasification Unit contracts in early October 2026, including a first EPCIC FSRU conversion for Excelerate Energy and a ninth conversion project with long-time partner Karpowership.
- These LNG carrier conversion deals deepen Seatrium’s role in floating gas infrastructure, adding complex EPC scope that could influence future workload visibility, execution risk and cost management.
- Now the focus shifts to how Seatrium's expanding FSRU conversion pipeline might alter its investment narrative around earnings quality and diversification.
Scan beyond Seatrium and explore other contractors involved in floating energy and gas infrastructure trends with the curated 43 power grid technology and infrastructure stocks
Seatrium Investment Narrative Recap
To own Seatrium, you need to be comfortable with a contractor whose fortunes hinge on winning and executing large, complex offshore and energy projects, while managing margin risk in a competitive Asian yard market. The key near term swing factor remains execution quality on its sizeable order book, because cost overruns or delays can quickly erode already modest net margins.
The fresh FSRU wins add technical depth and extend workload visibility, but do not radically change the short term picture. The bigger risk still lies in project concentration and timing of client FIDs, especially with revenue forecast to decline annually and Return on Equity expected to stay in single digits.
The Excelerate Energy EPCIC FSRU conversion looks most relevant. It stretches Seatrium further along the value chain, from pure conversion yard to a contractor handling engineering, procurement, construction, installation and commissioning. This increases the potential scope for revenue but also raises execution and cost control demands over a multi year build period.
If this first Excelerate project proceeds smoothly, it could support the existing catalyst narrative around higher quality earnings from complex energy transition work and possibly better margins. Any missteps would feed directly into the standing risks that analysts already flag, such as competition, pricing pressure and reliance on large one off project outcomes.
Seatrium's current analyst narrative points to revenue of SGD 8.8b and earnings of SGD 594.3m by 2029, based on an assumed yearly top line decline of 9.0%. That profile implies earnings today of SGD 552.2m and a value increase of about SGD 42.1m by the 2029 forecast year.
Uncover how Seatrium's fair value indicates a 36% potential upside to its current price before investors close that valuation gap.
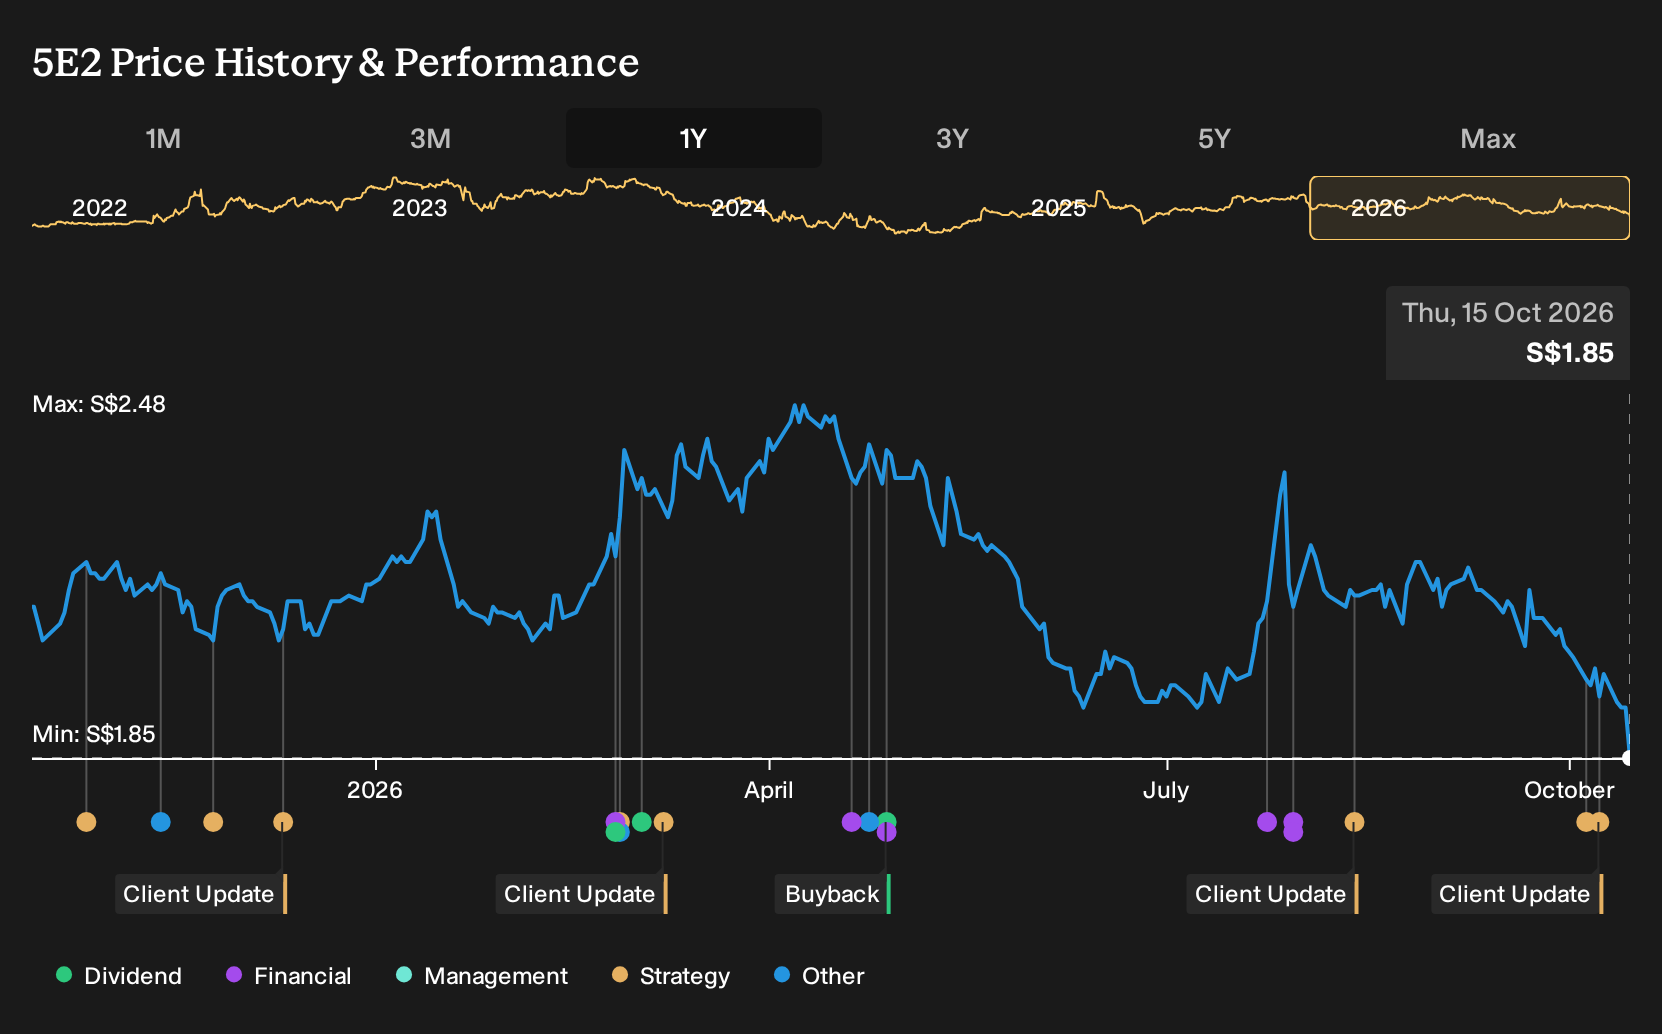
Exploring Other Perspectives
One alternate view leans on recurring FSRU and retrofit work as a possible cushion for Seatrium. Bullish analysts were already pencilling in slower yearly revenue decline of 5.1% and earnings of about SGD 734.2m by 2029, versus SGD 594.3m in the consensus set. Those projections came before these latest conversion awards, so expectations could shift again.
Explore 4 other Seatrium fair value estimates, including one that suggests as much as 181% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own. Seatrium rewards the investor who understands the moving parts, not just the headline contracts.
- A great starting point for your Seatrium research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Seatrium. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Seatrium's overall financial health at a glance.
Looking for more Seatrium sized investment ideas?
If you like the depth of work required to understand Seatrium, you might want a broader watchlist built from companies that already fit the kind of financial profile you prefer. The Simply Wall St Screener can help you filter the market quickly so you spend time analysing, not just searching.
- For investors who want quality and valuation to work together, you can scan a curated set of companies that screen as potential value opportunities through the 200 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, you can start with businesses that already clear a strict financial health bar using the list of solid balance sheet and fundamentals (202 results).
- Those hunting for under the radar opportunities can widen their field beyond Seatrium by reviewing a focused group of under followed companies via the 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com