


Is Analog Devices (ADI) Undervalued On Its Analyst Upgrade And AI Outlook?
Analog Devices (ADI) just picked up a top Zacks Rank upgrade after earnings estimates moved higher, drawing fresh attention to a stock already linked to AI infrastructure demand and high profile technology partnerships.
Despite a softer patch in the last week, with a 7 day share price return of 1.59% and a 1 day move lower of 2.68%, Analog Devices has ridden strong AI and partnership headlines to a 30 day share price gain of 11.79% and a 1 year total shareholder return of 71.58%. This suggests that momentum has been building over both the recent and multi year periods.
Scan for other AI hardware plays riding similar estimate upgrades and momentum with our curated list of 92 AI infrastructure stocks that is tied to data centers and high demand compute build outs.
Analog Devices now trades at a discount to both analyst targets and some peers, even after this AI fueled surge. Is that a genuine margin of safety, or a warning that the market sees risks others are ignoring?
Most Popular Narrative: 14.3% Undervalued
The most followed narrative on Analog Devices pegs fair value at $470.72 using an 11.48% discount rate, compared with a last close of $403.57. That gap frames the recent AI fueled rally as only part of the story rather than the full move already being behind you.
Further uptake of higher value products and disciplined pricing, underlined by non GAAP gross margin at 72.5% in Q3 2026 with guidance to about 74% and trailing 12 month free cash flow at 36% of revenue, suggests scope for Analog Devices to translate incremental sales into outsized net margin and free cash flow contribution as newer designs ramp.
See why 66 investors see Analog Devices as 14% undervalued.
Result: Fair Value of $470.72 (UNDERVALUED)
Still, rising low cost competition and any escalation in US China trade restrictions could challenge Analog Devices and weaken parts of this upbeat AI driven narrative.
Find out about the key risks to this Analog Devices narrative.
Another View: What The P/E Says About Analog Devices
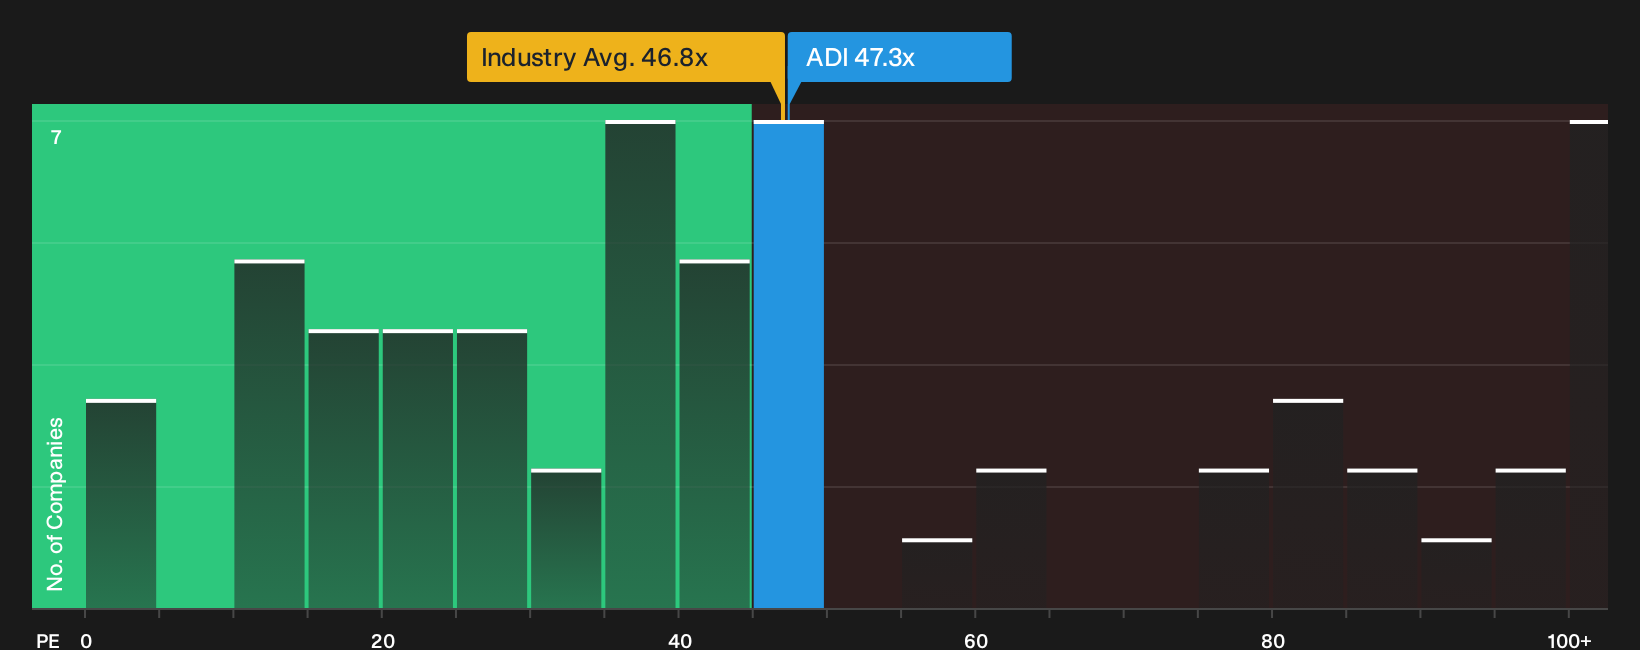
There is a catch to the bullish fair value story on Analog Devices. The stock trades on a P/E of 47.3x, which is above both the US Semiconductor industry at 46.8x and the SWS fair ratio of 32.5x. That richer multiple can signal valuation risk if expectations slip even a little.
For investors who rely on earnings multiples rather than cash flow models, this gap between the current P/E, the industry level, and the fair ratio raises a simple question. Is the premium a reasonable price for the AI and margin narrative, or is it asking you to pay too much for good news already in the price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling pulled between the upbeat AI story around Analog Devices and the valuation questions raised by its P/E and risk flags is completely reasonable. Act quickly by checking the underlying data, weighing both the upside drivers and the pressure points, and then grounding your view in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Analog Devices?
If Analog Devices has sharpened your interest in AI and quality balance sheets, the next smart move is widening your opportunity set with a focused stock search.
- Target resilient companies with cleaner financial risk profiles by scanning 32 resilient stocks with low risk scores that may better match your comfort level when markets turn choppy.
- Pursue value oriented ideas by reviewing the 32 high quality undervalued stocks that combine quality fundamentals with prices that still look reasonable on key metrics.
- Spot potential income workhorses by checking 7 dividend fortresses that pair higher yields with businesses aiming to support ongoing shareholder payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com