


Arcosa (ACA) Stock Looks Fully Valued Based On Current Earnings
Arcosa has seen its share price climb over recent years, and the question for you now is whether that performance is still grounded in the earnings the business is generating.
- Arcosa has returned 181.4% over the past 5 years, which puts a lot of weight on whether its current earnings can continue to support that kind of share price journey.
- The company’s value hinges on how efficiently it can turn its core operations into profit and cash, since that earnings base is what ultimately has to justify the current market valuation.
- Your read on Arcosa is one view; the desks covering it have another. See what analysts think Arcosa's shares could be worth.
The issue now is whether Arcosa’s recent share price, including a last close of US$147.06, is justified by its earnings when compared with the Fair Ratio benchmark.
If you want a wider starting point for research alongside Arcosa, take a look at a focused screen of 32 high quality undervalued stocks.
Has Arcosa Run Too Far on Earnings?
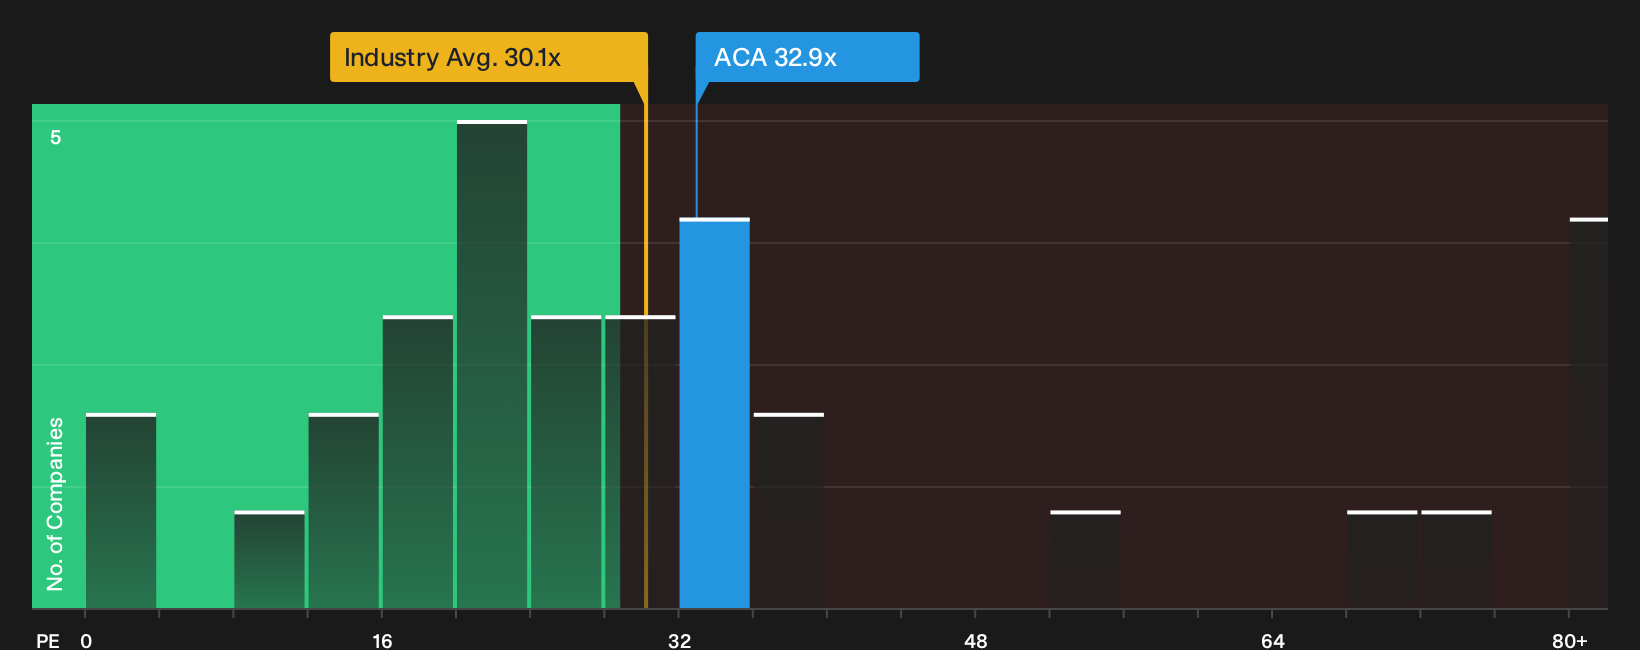
The P/E ratio works well for Arcosa because earnings are a key anchor for how investors frame the construction group’s value. At the moment, the stock trades on about 32.9x earnings, compared with roughly 30.1x for the wider Construction industry. That leaves Arcosa on a richer earnings tag than the sector average, even before looking at any company specific strengths or risks.
Against closer peers, the gap widens. Similar businesses in the space trade nearer 21.1x, while the Fair Ratio model, which folds in Arcosa’s margins, scale and risk profile, points to a lower level than where the shares currently change hands. For you as an investor, that means the market is already placing a premium on Arcosa’s earnings. The key question is whether the underlying business quality and long term prospects justify paying that higher multiple relative to both peers and the tailored benchmark. Explore the numbers behind Arcosa's P/E valuation.
The Arcosa Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the valuation question for Arcosa leaves off by spelling out which paths for future growth, profitability and earnings would need to occur for the shares to trade meaningfully higher or lower than today. Each scenario links a specific set of potential catalysts and risks to a single fair value estimate so you can watch over time which version of Arcosa's story appears to be taking shape.
One of the top community narratives on Arcosa: roughly fairly valued
"The ongoing shift toward sustainability, electrification and climate resilient infrastructure continues to favor Arcosa’s pivot toward Construction Products and Engineered Structures..."
Discover why this Narrative puts Arcosa at roughly fairly valued.
One more Arcosa angle worth your time
Share prices and P/E ratios only tell part of the story, because the people steering Arcosa and the way their pay is structured can strongly shape what happens next for shareholders. See who runs Arcosa and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com