


Seabridge Gold (TSX:SEA) Stock Looks Overvalued Even After Its Pullback
Seabridge Gold has delivered a 144.5% gain over the past three years, yet the recent pullback and fresh project acquisition leave a simple question hanging over the stock: Are investors now paying a price that its earnings can reasonably support?
- Over 3 years the share price is up 144.5%, which puts additional pressure on the current earnings base to justify where Seabridge Gold trades today.
- The purchase of the Slaughterhouse copper gold project in Wyoming adds early stage exploration potential, which can influence how quickly profits might arrive relative to the capital that goes into the ground.
- Your read on Seabridge Gold is one view; the desks covering it have another. See what analysts think Seabridge Gold's shares could be worth.
The stock's next move may depend on whether Seabridge Gold's current earnings stack up against the price investors are now asked to pay.
If you are weighing Seabridge Gold's recent pullback and project expansion against other opportunities in the same theme, it can help to compare it with 35 elite gold producer stocks
Does Seabridge Gold Look Pricey on Earnings?
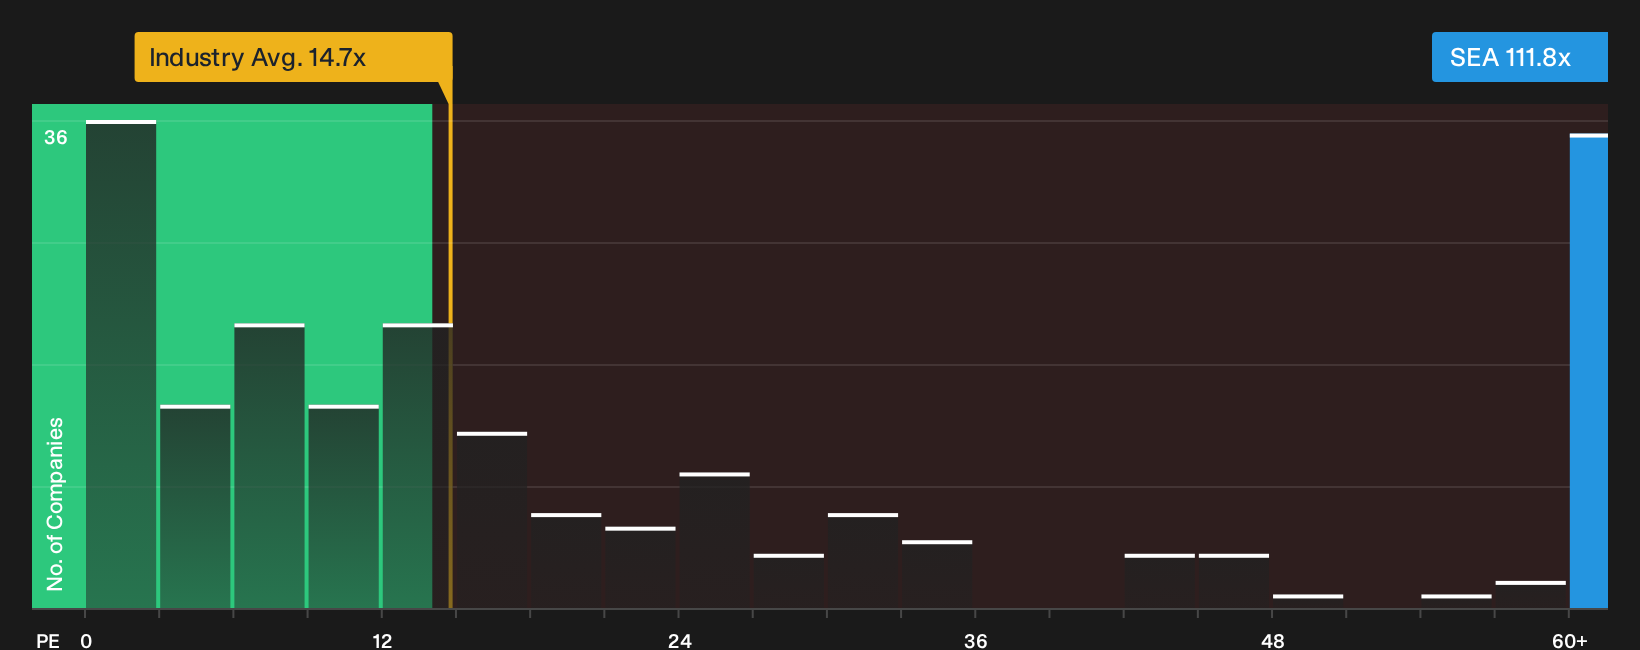
P/E fits Seabridge Gold because earnings, even if modest, are still the anchor for what investors are paying today. The shares trade on a P/E of about 111.8x, compared with roughly 14.7x for the wider metals and mining group and about 9.1x across close peers. That gap means buyers are paying a far richer price for each dollar of current profit than is typical for the sector.
The Fair Ratio framework, which adjusts for factors like growth potential, margins, size and risk, still flags Seabridge Gold as overvalued on earnings. The model heavily penalises the business for its loss profile and risk, so the implied fair level looks more like a warning signal than a precise target. Despite the Slaughterhouse acquisition adding early stage exploration upside, the present multiple already embeds a lot of optimism about what those projects might deliver in future. Explore the numbers behind Seabridge Gold's P/E valuation.
The Seabridge Gold Narrative: What Would Justify Today's Price?
Seabridge Gold's valuation puzzle raises an obvious follow up question, which is what future path for production, margins and earnings would need to unfold for today's P/E to look either restrained or excessive. Simply Wall St Narratives set out those implied futures in plain language on the Community page, turning a single model output into a set of expectations you can watch over time to see whether the story the number rests on continues to hold.
A clear, number-driven narrative on Seabridge Gold gives you a fixed set of assumptions on earnings, valuation and project timing that can be checked as real results emerge over time. With the Slaughterhouse copper gold project now in the mix, a written view also helps frame whether Seabridge Gold's current pricing leaves enough room for the risks and potential rewards tied to that acquisition.
Share your own Narrative for Seabridge Gold and set out the assumptions behind your valuation.
One more angle on Seabridge Gold that could change the picture
Big projects matter for Seabridge Gold, but the people steering those projects and how their rewards line up with your interests can matter just as much. See who runs Seabridge Gold and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com