


SSR Mining (TSX:SSRM) Stock May Still Be A Bargain On Marigold Mine Plan
SSR Mining has rewarded long term holders with a strong multi year run. This now puts a sharper spotlight on whether the current share price lines up with what its earnings can support. Recent news around mine plans and portfolio moves only raises the question of how much of that earnings story is already reflected in the valuation.
- SSR Mining has delivered a 129.4% total return over the past 3 years, which puts real weight on the question of whether its earnings justify that kind of rerating.
- The expanded 20 year plan at the Marigold mine and the planned Roxmore and Converse acquisition may support expectations for future production and cash generation. They also reshape the timing and scale of the earnings investors are effectively paying for today.
- The analysts covering SSR Mining have run their own numbers. See what analysts think SSR Mining's shares could be worth.
The issue now is whether the current SSR Mining share price can be explained by the earnings the business is producing and is expected to produce.
You can test the same earnings question you are asking of SSR Mining against a wider set of elite gold producers by scanning the 35 elite gold producer stocks.
Is SSR Mining a Bargain on Earnings?
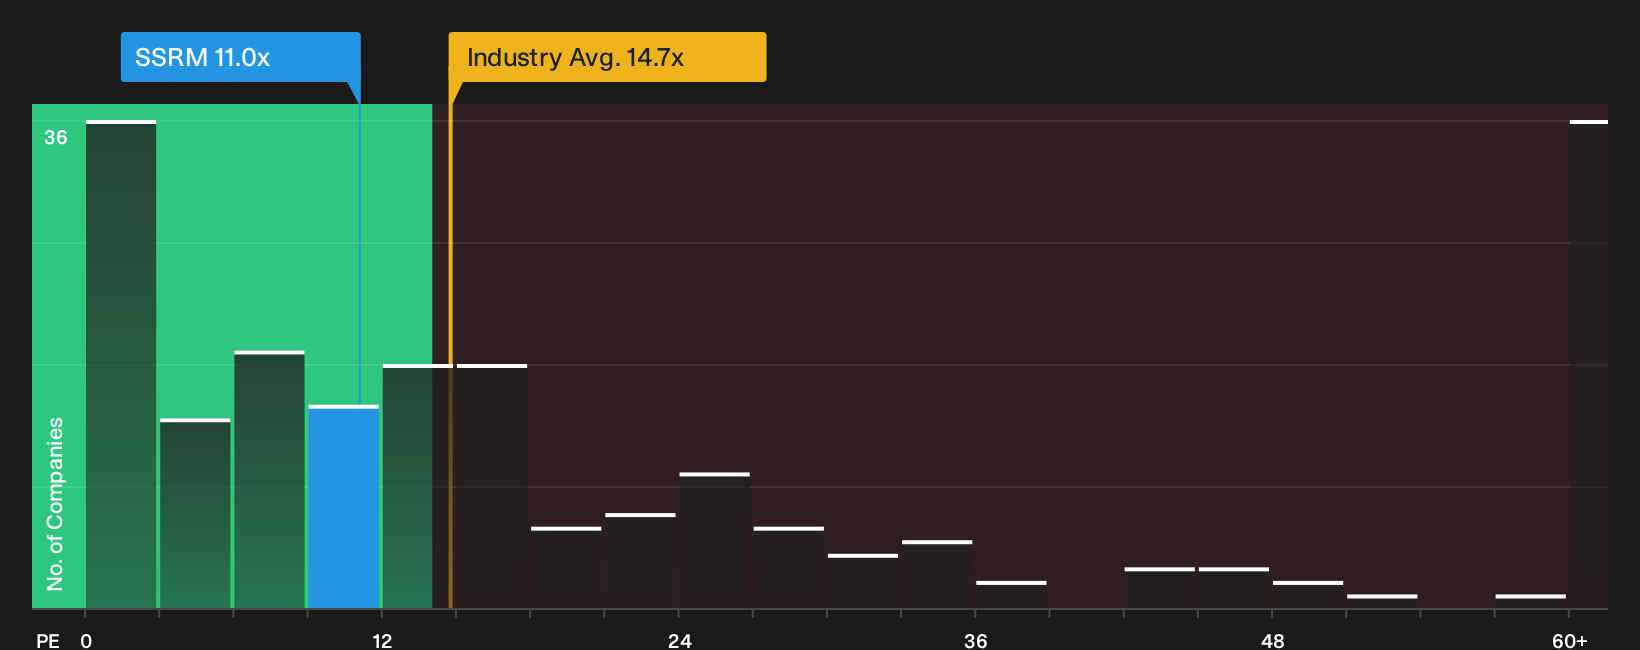
The P/E ratio fits SSR Mining because the business is already earnings generating. On this measure, the stock trades on about 11.0x earnings, which is lower than both the metals and mining industry average of roughly 14.7x and the peer group on about 12.8x. That gap tells you the market is not paying the same headline multiple for SSR Mining as it is for many comparable producers.
Because of the way the fair multiple model links valuation to the company’s growth profile, profitability and risk, SSR Mining’s current P/E screens below the level that framework would imply. This points to the shares pricing in some caution. Despite the long life Marigold plan and the Roxmore and Converse deal sharpening the production outlook, the stock still trades at a discount on earnings terms. That leaves the key question of whether the operational plan and balance sheet moves are enough to close that gap over time in investors’ eyes. Explore the numbers behind SSR Mining's P/E valuation.
The SSR Mining Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where SSR Mining's P/E puzzle leaves off by explaining which earnings, growth and margin paths would need to unfold for the share price to appear meaningfully higher or lower than it is today on the screen. They also tie each scenario to a specific mix of potential catalysts and risks so you can track which version of SSR Mining's story seems to be aligning with reality over time on the Community page.
One of the top community narratives on SSR Mining: 36% undervalued
"With a fortress balance sheet and strong ongoing free cash flow, SSR Mining has the scale and optionality to pursue capital allocation strategies..."
Discover why this Narrative puts SSR Mining at 36% undervalued.
SSR Mining’s valuation still hinges on who is steering the ship
Before you stop at the numbers, it is worth asking how the people running SSR Mining are rewarded and whether their incentives truly align with long term shareholders. See who runs SSR Mining and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com