


Plug Power (PLUG) Hits A 52 Week Low, Is It Still Undervalued?
Plug Power (PLUG) is back in focus after the share price hit a new 52 week low. The slump has drawn attention to its cash burn, short cash runway, and potential dilution risk.
The latest slide brings Plug Power into a wider losing streak, with the share price down 29.6% over the past month and the 1 year total shareholder return falling 62.3%. This signals fading momentum as investors reassess financing risk and cash burn.
Scan beyond Plug Power's slump and compare its risk profile with a hand picked group of companies that score well on balance sheet strength using our list of solid balance sheet and fundamentals (25 results)
Plug Power is pitching a big vision in hydrogen, yet the share price now reflects deep skepticism after the recent slide. So does this look like a mispriced asset, or a fair response to its financing strain?
Most Popular Narrative: 59% Undervalued
On the most followed view, Plug Power's fair value of $3.55 sits well above the last close at $1.45. This valuation places significant emphasis on long term hydrogen execution and policy support actually translating into cash returns.
Recent policy support and operational improvements are driving increased customer adoption, expanding the revenue pipeline, and significantly enhancing margins. Expansion of hydrogen production and supply networks is boosting reliability, lowering costs, and strengthening multi-year growth prospects in both US and international markets.
See why 203 investors see Plug Power as 59% undervalued.
Result: Fair Value of $3.55 (UNDERVALUED)
Still, Plug Power's heavy losses of $1.6b on US$744.1m of revenue and ongoing liquidity pressure mean that execution missteps or funding setbacks could quickly unwind this undervalued narrative.
Find out about the key risks to this Plug Power narrative.
Another View: Plug Power Looks Expensive On Sales
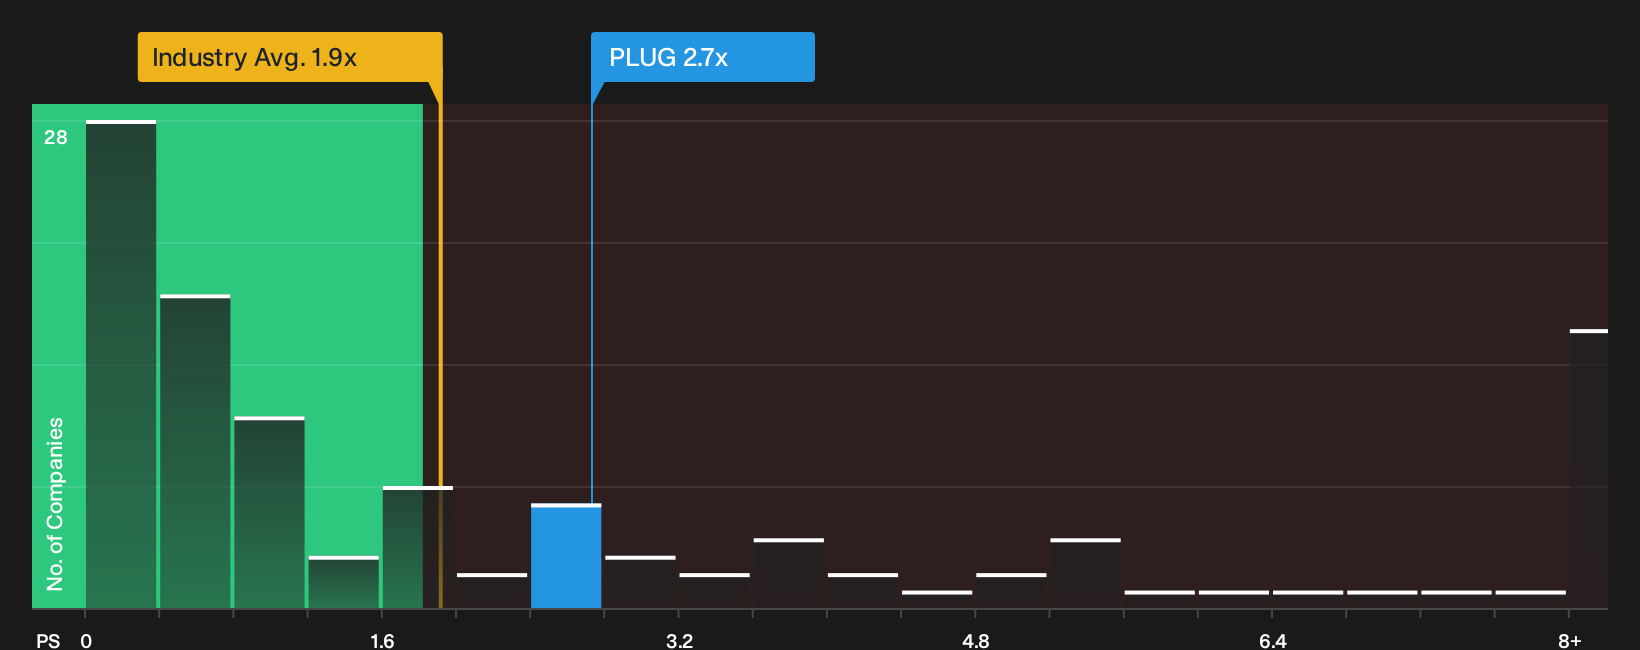
The story flips when you stop at the income statement and look at Plug Power purely on P/S. The shares trade around 2.7x sales, compared with 1.9x for the broader US Electrical group and 2.2x for peers, while the fair ratio sits much lower at 0.6x.
That gap points to meaningful valuation risk if the market leans back toward the fair ratio instead of the richer multiples currently implied. How much conviction do you really have in the optimistic turnaround case?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Plug Power is clearly split, so take this as a cue to review the full risk and reward profile for yourself while the price is moving and weigh the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Plug Power?
Do not stop your research with Plug Power. Fresh opportunities often sit where fewer investors are looking, and you do not want to miss them.
- Target stronger potential value by reviewing companies on our 32 high quality undervalued stocks that combine attractive pricing with solid underlying fundamentals.
- Guard your portfolio against shocks by scanning a 32 resilient stocks with low risk scores that screens for resilient balance sheets and steadier business profiles.
- Get ahead of the crowd by checking a 20 high quality undiscovered gems that highlights quality businesses the broader market may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com