


BrightSpring Health Services (BTSG) Lifts 2026 Outlook Again Following Integration Progress And Valuation Debate
BrightSpring Health Services (BTSG) has twice raised its 2026 outlook, citing strong demand in Pharmacy Solutions and Provider Services, progress integrating Amedisys and LHC branches, and reshaping the portfolio through technology spending and divestitures.
At a share price of $63.35, BrightSpring Health Services has posted a 1-month share price return of 5.06% while the 90-day share price performance is down 7.06%. However, the year-to-date share price return of 64.97% and 1-year total shareholder return of 106.08% point to strong momentum building over the longer stretch as investors reassess the raised outlook, integration progress and portfolio reshaping.
Scan other healthcare operators showing similar guidance momentum and acquisition integration stories with the hand-picked 34 healthcare AI stocks that could sit alongside BrightSpring Health Services in a forward-looking watchlist.
BrightSpring Health Services now looks like a bigger, more focused healthcare platform, yet the share price has already sprinted ahead. Is this a strong franchise at a fair tag, or has enthusiasm run ahead of the math?
Most Popular Narrative: 10.3% Undervalued
Against a last close of $63.35, the most followed narrative pegs BrightSpring Health Services at a fair value of $70.59, framing the current share price as a discount rather than a stretch.
The real business is not home health. It is pharmacy.
Roughly 80% of revenue comes from specialty and institutional pharmacy services:
• Infusion therapies delivered at home (oncology, autoimmune, IV antibiotics)
• Long-term care pharmacy services in assisted living and nursing facilities
• Specialty drug distribution for chronic and rare disease patients
This is where the structural moat exists: patients are not “customers” in the retail sense, they are clinically managed cases. Once a patient enters an infusion or specialty pharmacy program, switching providers is rare because:
• Treatment continuity is medically sensitive
• Coordination with nurses and physicians is embedded
• Insurance authorization is complex and sticky
• Logistics (cold chain, dosing schedules) are specialized
This creates low churn, recurring revenue, and embedded payer relationships. In short: BrightSpring is closer to a healthcare infrastructure platform than a traditional pharmacy company.
See why 9 investors see BrightSpring Health Services as 10% undervalued.
Result: Fair Value of $70.59 (UNDERVALUED)
Still, the BrightSpring Health Services story can break if integration drags, cost savings stall, or pharmacy reimbursement pressure squeezes the economics that investors are banking on.
Find out about the key risks to this BrightSpring Health Services narrative.
Another View: BrightSpring Health Services Looks Expensive On Earnings
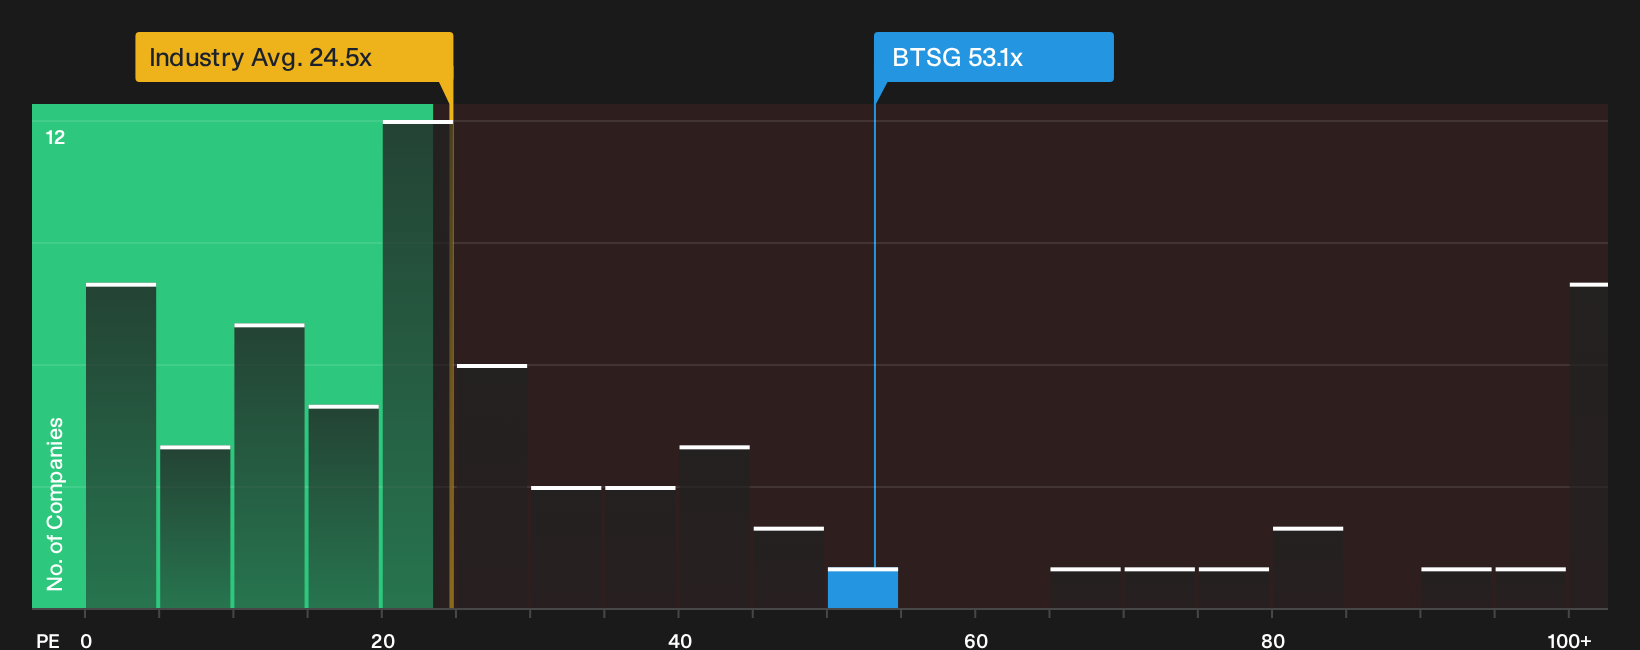
On the flip side, BrightSpring Health Services trades on a P/E of 53.1x, which is more than double the US Healthcare group at 24.5x and well above a fair ratio of 35.4x. That gap signals investors are already paying up. If sentiment cools, how much of that premium holds?
For a numbers driven check on what this pricing gap might mean over time, run BrightSpring Health Services through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on BrightSpring Health Services so far. If the combination of raised guidance and rich valuation has you uncertain, consider acting promptly and stress testing it against your own assumptions with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BrightSpring Health Services?
If BrightSpring Health Services has your attention, do not stop at a single ticker. Broaden your opportunity set with focused screens that surface very different types of potential candidates.
- Target potential upside by scanning a hand picked pool of underpriced quality with the 32 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for companies with robust finances through the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by reviewing the 20 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com